Managing Fixed Assets: Accounting Techniques For Long-Term Success
Fixed assets, often the largest investment for a business, play a vital role in an organization’s financial stability and growth. Managing them properly through well-crafted accounting techniques ensures that they contribute positively to the company’s long-term success. This article will explore various strategies, methods, and best practices for effectively managing fixed assets within an accounting context.
Understanding Fixed Assets
Fixed assets are long-term tangible assets that a business utilizes to generate income, such as buildings, machinery, equipment, and vehicles. Unlike current assets, fixed assets are not intended for sale within the regular business cycle but are instead used over several years. The proper management of these assets is essential for accurate financial reporting and strategic planning.
Depreciation and Amortization
One of the critical aspects of fixed assets accounting is understanding depreciation and amortization. Depreciation is the gradual reduction in a tangible asset’s value over its useful life, while amortization applies to intangible assets like patents or licenses. Calculating and recording depreciation accurately is vital for reflecting the actual value of assets on the balance sheet and for determining tax liabilities.
Implementing Proper Tracking and Control
Effective management of fixed assets requires meticulous tracking and control. This involves regular audits, documentation, and utilization of technology to ensure accuracy.
Asset Tagging and Monitoring
Assigning unique identification tags and employing tracking software helps in monitoring the location, condition, and utilization of assets. Regular physical verification ensures that the records align with actual assets, preventing discrepancies and fraud.
Integration with Accounting Systems
Fixed assets accounting must be seamlessly integrated with the overall accounting system. This allows for automated updates, reducing manual errors and providing real-time insights into the assets’ status.
Ensuring Compliance and Reporting
Compliance with various regulatory standards and accurate reporting are paramount in fixed assets accounting. Adherence to guidelines such as Generally Accepted Accounting Principles (GAAP) and International Financial Reporting Standards (IFRS) ensures transparency and builds trust with stakeholders.
Regular Review and Reconciliation
Regular review of fixed asset registers, reconciliation with financial statements, and adherence to legal requirements ensure that the organization is compliant with all relevant laws and regulations. This not only minimizes legal risks but also provides an accurate representation of the company’s financial health.

Investing in Technology and Training
In today’s fast-paced business environment, investing in the right technology and training personnel is essential for efficient fixed assets accounting.
Utilizing Fixed Assets Management Software
Advanced fixed assets management software offers features like automated depreciation calculation, asset tracking, and reporting. Investing in a system that fits the organization’s needs simplifies the management process and enhances accuracy.
Training and Development
Ensuring that the team responsible for fixed assets accounting is well-trained and updated with the latest industry standards and regulations is equally important. Regular training sessions, workshops, and certifications enhance competency and foster a culture of continuous improvement.
Selecting the Right Fixed Assets Accounting Method
Choosing the appropriate accounting method for fixed assets is a crucial decision that can have a lasting impact on financial reporting and tax liabilities. Various methods can be applied, each with its own set of rules and implications. Selecting the right method depends on several factors such as the nature of the asset, the industry, and the financial goals of the organization.
Here’s a list of common accounting methods used for fixed assets:
- Straight-Line Method: This method spreads the asset costs equally over its useful life, providing a persistent expense in depreciation every year.
- Double Declining Balance Method: This approach accelerates depreciation, with higher expenses in the earlier years of the asset’s life.
- Sum-of-the-Years-Digits Method: A more complex method that also front-loads depreciation but at a different pace compared to the double declining balance.
- Units of Production Method: Depreciation is calculated based on the asset’s actual usage or production. It is suitable for machinery or equipment with variable usage.
Understanding the advantages and disadvantages of each method, aligning them with the company’s operational dynamics, and seeking professional guidance if necessary, ensures that the chosen method reflects the economic reality of the fixed assets, complies with relevant accounting standards, and supports the organization’s strategic objectives.
Conclusion
Fixed assets accounting is more than just numbers on a balance sheet; it’s a strategic component that directly impacts an organization’s long-term success. Every aspect contributes to effective management, from understanding depreciation to implementing robust tracking systems, ensuring compliance, and investing in technology and training.
By adopting best practices and staying abreast of changes in regulations and technology, businesses can leverage fixed assets as valuable resources, driving growth, stability, and success in an increasingly competitive market landscape.
Read Also:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
Which Describes A Type Of Tax That Funds City Programs? – Let’s Find Out
Which describes a type of tax that funds city programs? – The answer is local income tax or local tax. These taxes are mostly meant to fund local public services. These include education, maintenance, etc. These taxes also come in many forms for employees and businesses. Businesses need to perform tax planning accordingly to withhold the income tax of employees and also file the tax for business earnings as well. In this article, you will learn about the essential details of local income tax and how it works in the United States. Next up, you will also learn about the types of local taxes that are applicable. Furthermore, you will also learn about the types of state and local taxes one must pay. Hence, to learn more about the local tax, read on through to the end of the article. Which Describes A Type Of Tax That Funds City Programs? Local tax is the tax that funds city programs. According to Investopedia, “A local tax is an assessment by a state, county, or municipality to fund public services ranging from education to garbage collection and sewer maintenance. Local taxes come in many forms, from property taxes and payroll taxes to sales taxes and licensing fees. They can vary widely from one jurisdiction to the next. Taxes levied by cities and towns are also referred to as municipal taxes.” Most states impose income taxes on employees and businesses. In the case of employees, businesses withhold the taxes and file those taxes with the help of Forms W2 and W4. Local taxes also include those taxes that states and cities impose on goods and services. Apart from that, the property tax bill is also a type of local tax that homeowners pay to the local government. However, TaxFoundation.org states – “Cities, counties, school districts, and other localities that have instituted taxes on their residents’ incomes have done so either to reduce other taxes or to raise more revenue for local services. These may be laudable goals on paper, but local income taxes come with more undesired consequences than other local revenue sources, both for taxpayers and the governments that rely on these revenue streams.” How Does Local Tax Work In The United States? As per the Constitution of the United States, the federal government and the state governments have the authority and right to impose taxes on US residents. According to TaxPolicyCenter.org, “The individual income tax base in most states is similar to the federal tax base. Most states start with federal adjusted gross income, but a few start with federal taxable income. Alternatively, a handful of states use their own definition of income, but even these states rely heavily on federal rules when establishing their tax base. Even the states that start with the federal tax base, however, often apply different rules for certain types of income.” With the help of these taxes, local government fund government services. These services include police, health, fire services, education, maintenance of the locality, etc. Apart from that, with the help of these taxes, local governments also create projects that benefit various communities at large. Apart from that, there are also services that receive federal funds using grants. Local taxes include state, county, and municipal taxes. These taxes are not under federal taxes. When it comes to levying taxes, municipalities face a constant balancing act. They do not keep those taxes high. This is because high taxes face resistance from the public. However, low taxes mean that there are cutbacks in essential services. On a side note, if you want to learn more about tax refund tips, click on the given link. What Are The Types Of Local Taxes? Most of the states in the US impose taxes like personal income tax, estate tax, corporate income tax, fuel tax, and sales tax. The following are the common types of local taxes: Property Tax The property tax is the largest tax that most people (homeowners) receive. The value of the tax depends on the value of the home, which depends on a variety of factors. In each state, there is a guideline under which local governments of the state impose property taxes. Miscellaneous Taxes Local income taxes are imposed by states and cities. The government allows businesses and organizations to withhold those taxes from the wages of employees. Furthermore, there are local wage taxes that a total of sixteen states permit. School district tax is a local tax that you can find in Ohio and Pennsylvania. Sales taxes are for goods and services that residents of a state or municipality purchase. This is a type of regressive tax, as all customers pay the same percentage of tax regardless of their income. However, sales taxes are not applicable to states like Alaska, Montana, Delaware, Oregon, and New Hampshire. Other Government Funding Sources There are other ways through which governments fund capital projects in the community. One of the most common techniques they use is to issue bonds. Investors buy those municipal bonds. As a result, they are lending money to the government. The government, in return, is repaying the principal on a future date along with a set amount of interest. To pay its debt or to fulfill interest and repay the principal, the municipal government might issue a new tax or increase the percentage of the local tax. What Is The Importance Of Local Taxes? It is important to pay your tax bill, especially the local taxes. Municipalities and state governments use these taxes to pay the salaries in public services and to fund other costs of running society. They fund social programs, education, maintenance, local infrastructure, and more. Wrapping Up Which describes a type of tax that funds city programs? – The answer is local tax. Hope this article was helpful for you in getting a better understanding of what local tax is and how it works for governments. Do you have more information to add regarding local taxes? Share your information with us in the comments section below. Get More Financial Issue By Clicking Below!! Stakeholder Theory: What Is It, Working, Benefits, Challenges, And More What Is An Endowment? – Working, Purpose, Types, And More What Is a Bear Hug? Let’s Discuss The Benefits
Dec 08, 2023
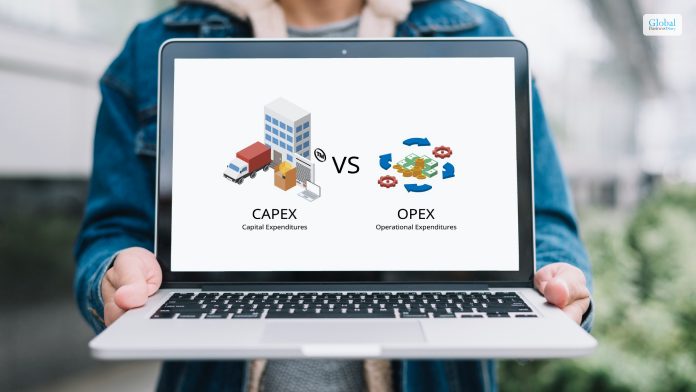
Capex Vs Opex: Essential Points Of Difference
A company has to pay off different kinds of expenses to run its business smoothly. Capex vs Opex is one of the popular expense differentiation you must know. Among them, two kinds of expenditures are quite prominent in this regard. First is the Capex, and second is the operating expenses. Most of the time, these costs can be one, and sometimes they can take the shape of recurring expenses. You must follow the correct process that can assist you in getting things done in perfect order. Micromarketing techniques can work well here. The capital expenditure of a company will occur once, while the operating expenses will keep on occurring all the time. If you are a business owner, you must know the core points of differences between the two concepts. Essential Points Of Difference Between Capex vs Opex There are several points of difference between Capex vs Opex. It will offer you the complete insight once you go through the complete article. You need to know the reality while making the differentiation between the two concepts of business./ 1. Nature Of Expenses Capex vs Opex has some core differences in the nature of their expense model. Capital expenditures or Capex are investments in assets that provide long-term benefits to a company. These expenses are typically for acquiring, improving, or maintaining assets such as property, equipment, machinery, or infrastructure. Operating expenditures are day-to-day expenses incurred in running a business. These include costs for salaries, utilities, rent, marketing, repairs, and other ongoing operational expenses. You must consider these facts from your end while making the differences between the two concepts. 2. Duration Of Benefit Capital expenditures provide benefits over an extended period, usually beyond one fiscal year. They contribute to the company's future productivity, efficiency, or revenue generation. Capex vs Opex has some significant points of differences that you must know while you make the comparison. Operating expenditures are incurred for immediate use and provide short-term benefits. They are essential for maintaining regular business operations and generating immediate revenue. It will give short-term and regular benefits to your company. 3. Treatment In Financial Statements Capital expenditures are recorded as assets on the balance sheet and depreciated or amortized over their useful life. Depreciation or amortization expense is then reported on the income statement over time. Operating expenditures are immediately shown on the income statement in the period they are incurred. They directly impact the company's net income for that period. You need to identify the perfect solution that can make things easier for you to reach your goals with ease. 4. Tax Treatment Capital expenditures might be eligible for tax benefits such as depreciation or amortization deductions over time, reducing taxable income. Capex vs Opex, you must consider things at your end while reaching your objectives. Operating expenditures are fully deductible in the year they are incurred, providing immediate tax benefits. You should get through this difference to have a better idea of it. Ensure that the scope of errors is as low as possible. 5. Impact On Profitability & Cash Flow While CapEx affects profitability indirectly through depreciation expenses. It has a significant impact on cash flow at the time of purchase or investment. You cannot afford to make things work in the wrong direction from your counterpart. On the other hand, Operating expenditures directly affect profitability by reducing net income and also impact cash flow in the period they occur. Effective planning can boost the chances of reducing the expenses of your business. 6. Decision Making & Budgeting Capital expenditures involve strategic decisions as they impact the company's long-term growth and productivity. Budgeting for CapEx requires careful planning and consideration of future benefits. You should know the core points of differences between Capex vs Opex. It will assist you in attaining your goals with complete ease. Operating expenditures are part of routine budgeting and are necessary for maintaining day-to-day operations. They are generally more predictable and recurring. Without proper application of the strategies, things can turn worse for you. Examples Of Capex Expenditure There are several examples of Capex expenditure that you should know at your end. It will help you to get a better insight into it. Let’s find out some of the core examples of the Capex Expenditure that can make things easier for you. Machinery, manufacturing plants, and equipment. Computers. Building Improvements. Trucks and vehicles. The contribution margin of the company plays a vital role here. You should pay it from your end to meet all the expenditure. Examples Of Opex Expenditure There are several examples present for Opex expenditure that you must know at your end. Some of the core examples of it are as follows:- Salaries and wages. Rent and Utilities Legal and accounting fees. Overhead costs. Business travel. Property expenses. Interest on debt. Research and development expenses. You can easily make the market segmentation with the help of the differences between capex vs opex to meet the requirements. How To Reduce Capital Expenditure? There are several techniques you can employ to reduce the capital expenditure of your company to a great extent. You must follow the correct process in this regard to have a better idea of it. 1. Evaluate The Asset Needs Conduct a thorough assessment of current assets to determine if there are underutilized or redundant assets. Selling or repurposing such assets can free up capital and reduce the need for new investments. 2. Leasing Vs Buying Consider leasing equipment or assets instead of purchasing them outright. Leasing can lower initial costs and shift maintenance and upgrade responsibilities to the lessor. 3. Prioritize Essential Investment Focus on essential investments that directly contribute to core business operations or strategic growth. Prioritize projects that offer the highest return on investment (ROI) and align with long-term business goals. 4. Implement Of Efficient Technology Invest in technology that streamlines processes, reduces manual work, and improves efficiency without significant capital outlay. Cloud-based solutions or software-as-a-service (SaaS) models often have lower upfront costs. 5. Outsource Non-Core Functions Consider purchasing refurbished or used equipment instead of new. Often, these options come at a lower cost while still providing adequate performance and reliability. Final Take Away Hence, if you are making the differences between the two concepts of capex vs opex, then the mentioned points can prove to be useful for you. Try to reduce your expenses as much as possible. It will reduce your debts to a great extent. You can share your views and opinions in our comment box. It will help us to know your take on this matter. Once you follow the correct process, things are going to be easier for you. The application of the correct strategy can make things work for you. Continue Reading For More Business-Related News!! How To Buy An LLC? – Steps To Follow How To Become A Strategy Consultant? Roles & Responsibilities What Is A Sales And Purchase Agreement For Business? – Let’s Find Out
Nov 26, 2023
What Will Happen If You Do Not Pay Your Tax Bill? What Are The Next Steps?
There's a saying in life: only two things are certain – death and taxes. Yet, while everyone knows they need to pay their taxes, some people either cannot or choose not to do so. What happens if you don't pay your taxes, and what are the next steps if you find yourself in this predicament? In this blog post, we will explore this issue in depth. Initial Notices And Letters If you haven't paid your tax bill, the first thing you'll receive is letters from the tax authority in your country (the Internal Revenue Service (IRS) in the US, for instance). These letters are typically polite reminders telling you that you owe taxes and providing instructions for payment. Should you fail to respond to these reminders or choose to ignore them, the letters will progressively become more serious and insistent. Don’t underestimate the importance of these letters – they are an official record of your debt and could have severe legal implications down the line. It's best to consult a tax professional or attorney if you receive these letters to understand what your next steps should be. Remember, you can always find out here about dealing with these notices. Interest And Penalties It's not just the initial tax bill you'll need to worry about if you don't pay your taxes. The amount you owe will continue to grow due to penalties and interest. The IRS, for example, typically adds a failure-to-pay penalty of 0.5% of the total unpaid taxes for every month or portion of the month the tax is left unpaid. Furthermore, this penalty can build up to as much as 25% of your entire unpaid taxes. Tax Liens If your unpaid tax debt continues to grow and remains unresolved, the tax authority may place a tax lien on your assets. This means they have a legal claim to your property, including your house and car, which they can seize to settle your tax debt. A tax lien can wreak havoc on your credit score, making it difficult for you to secure loans or credit in the future. Wage Garnishment And Asset Seizure In extreme cases, if you continue to ignore your tax debt, the tax authority has the power to garnish your wages or even seize your assets, such as bank accounts, to pay off the debt. This is a last resort measure and usually follows several attempts by the tax authority to collect the debt voluntarily. Criminal Charges While rare, it's possible to face criminal charges for not paying taxes. Tax evasion is a serious crime and can lead to fines or imprisonment. However, the tax authority usually reserves this for egregious cases or when they suspect deliberate fraud. Next Steps If You Can't Pay Your Tax Bill So, what can you do if you're unable to pay your tax bill? Don’t panic – there are several options available. 1. Installment Agreements Many tax authorities, including the IRS, offer installment agreements for taxpayers who cannot pay their tax bills in full. This lets you pay tax debts over time in smaller, more manageable amounts. 2. Offer-In-Compromise An OIC or Offer in Compromise refers to an agreement between the tax authority and a taxpayer that stabilizes the tax liabilities of the taxpayer for a reduction from the complete amount owed. However, this is not a guarantee, as the tax authority will take into account your ability to income, pay, expenses, and asset equity. 3. Temporary Delay If the tax authority determines that you're unable to pay the tax debt you own, they may temporarily delay collection until your financial condition improves. In Conclusion While not paying your tax bill can lead to serious consequences, there are options and resources available if you find yourself unable to pay. Remember, the worst thing you can do is ignore your tax bill. It's essential to communicate with your tax authority and seek professional advice if you're having trouble. Remember, the sooner you address your tax issues, the less severe the penalties are likely to be. So, take action now before a manageable issue turns into a financial nightmare. Read Also: Maximizing Tax Refunds: Tips And Tricks For Canadians Seven Potential Tax Credits Available To Small Businesses In 2023 Business Deductions And Tax Planning: Two Critical Steps To Save Money
Jul 03, 2023
Common Personal Loan Myths You Should Not Believe: A Complete Guide:
Personal loans are currently one of the most popular loans. You can use it for any purpose. You may be wondering why so many individuals prefer personal loans. Personal loans provide several advantages to borrowers. However, they are only sometimes the best solution for everyone. A personal loan has many benefits. It includes fast approval, easy qualifying requirements, speedy disbursement, and flexible payback terms. In all kinds of cash crunches, the loan can assist you. Despite the benefits, there are several myths that one should not believe. What Are The Pros Of A Personal Loan? Because interest rates are often much lower, a personal loan is usually cheaper. It is cheaper than using a credit card or receiving a payday loan. Also, payday loans must be repaid in full. Hence a personal loan is a more convenient alternative. Most personal loans are small and can be as much as $100,000. Have you considered applying for a personal installment loan but are still determining if it is wise? This article will help you with it. Moreover, if you want a personal loan, sorting payroll is essential. However, you can use a paystub generator for smooth working. A personal loan might be an excellent solution depending on your financial condition. It will assist you in making your payments. Continue reading to learn about the common myths about personal loans. Myths About Personal Loans: Read on to learn about seven common myths about personal loans. You will also be able to see the reality behind it. It will help you to apply for one. A low credit score results in loan denial: Many consumers believe they will not get their loans approved because of poor credit scores. An individual's credit score is not the only thing that banks consider. When determining loan eligibility, other variables take priority over a poor credit score. Besides an individual's credit score, financial organizations also consider other factors. It includes the borrower's income and ability for repayment. Personal loans have a lengthy processing: Borrowers avoid applying for a personal loan because they expect a longer processing time. They also believe that there is a need for more approval procedures. Personal loans are not secure. So they do not need collateral. You can issue them within 2-7 working days. You need to file the loan application with small documentation. Moreover, some lenders offer to provide same-day personal loans. Huge interest rates: The most widely held assumption about personal loans is their high-interest rates. In practice, these loans may be cheaper than other unsecured loans. Remember that having a fantastic credit score is the key to qualifying for low-interest rates. If you want a personal loan, shop with other lenders to check interest rates. Understanding what different lenders have to offer will help you get the best personal loans. It also helps individuals with bad credit to get a loan at the best interest rate. It does not have to be a stressful or time-consuming procedure. You may compare interest rates and personal loan lenders easily and quickly. It is hard to get approval: Another common myth about personal loans is that they are challenging to get. This is arguably the most common myth that is simple to believe and qualifies but is incorrect. Obtaining this form of loan nowadays is as simple. It is as simple as completing an online application and waiting for approval. Applying for a personal loan is simpler than obtaining a house or a vehicle loan. It begins with a simple online comparison of your loan possibilities with fixed and variable interest rates. The Only Lenders Are Banks: Before the internet age, banks were the sole providers of personal loans. There is a growing popularity and renown of internet lenders. Consumers today have several possibilities for obtaining a personal loan. Cooperating with an internet lender might provide you with several perks and advantages. Most significantly, the personal loan application procedure is simple and quick. You may receive an instant response to your application. You can use the loan only for personal reasons: It may be confusing to you since the term implies "personal." Many people believe that the loan is for personal purposes. Other lending organizations, unlike banks, are not concerned with how or where you use the money. They will not interfere with your plan to spend the money. You only must make monthly payments on schedule. You must show a serious commitment to return the loan amount. It is up to you how you intend to use it. You may also use it as extra funding for your business. Perhaps you need it for an emergency, such as repairing a broken automobile or home. There are so many ways where you can use a personal loan. Personal loans are available to salaried persons: It is generally believed that only people with a regular income stream are eligible to apply for personal loans. It is just another misconception about personal loan applications. When there is a consistent income stream, it is simpler for salaried workers to get their loan applications authorized. Those who are self-employed can also get personal loans. The individual's credit history determines the approval of the loan amount. But the amount approved may differ. NOTE: Many people find personal loans to be an attractive source of money. Unfortunately, most need to familiarize themselves with the many components of personal loans. There are various myths or misconceptions. You should not trust them. To take advantage of personal loans, you must first verify your beliefs. The list will help you determine what is true and what is not. Understanding these myths can help you on your loan journey. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Mar 17, 2023