





Business Continuity Plan – What Is It, And How Does It Work?
Your business can come across a disaster or a host of negative situations for the business, which negatively affect the work processes of the business. In such cases, business continuity planning is one of the most necessary things to have. A business continuity plan will enable you to stay prepared for any kind of negative situation for the business. This shall further ensure that the business is able to work the same.
In this article, you will learn about a business continuity plan and what are its major features. In addition to that, you will also learn how a business continuity plan works for a business. Furthermore, we will also discuss the major benefits of having a business continuity plan for your business. Finally, we will guide you with a step-by-step procedure on how to create such a plan for your business and stay prepared.
What Is A Business Continuity Plan?
According to Hubspot.com,
“A business continuity plan outlines directions and procedures that your company will follow when faced with a crisis. These plans include business procedures, names of assets and partners, human resource functions, and other helpful information that can help maintain your brand’s relationships with relevant stakeholders.”
The major goal of a business continuity plan is to deal with the situations that disrupt the business. These disruptions can be both minor and full-blown threats. The plan allows you to plan for contingencies ahead of time.
Such plans, as well as preparations according to those plans, can allow your business to continue operations even at times of high risk. Having a plan will help you to deal with the risks and either prevent or mitigate them.
Some of the major disruptions that can affect the business include a natural disaster, a man-made disaster, a network breakdown, a cyber attack, and various other factors. These situations are large enough to disrupt organizations of any size. In such situations, a business continuity plan benefits the business by providing it with a procedure, processes, and tools. These will help the business to operate properly and recover within a short span of time.
Read More: What Is a Franchise, And How Does It Work? – Examples, Benefits & More
How Does A Business Continuity Plan Work?
According to VMWare.com,
“Business continuity planning is critical because without it, an organization faces downtime and other problems that could damage its financial health. In major disasters, a lack of a business continuity plan could cause irreparable financial harm that might ultimately force a company to permanently close.”
In a business continuity plan, the business defines all the risks that can affect the operations of the organization. Hence, the plan becomes an important part of the risk management processes of the business. Some of the major risks include disasters, network breakdowns, cyberattacks, and more.
Since threats and disruptions include a loss of revenue and higher costs for the business, it can lead to a loss of business profits. Furthermore, it is also not a great thing for your business to rely on insurance alone. Also, since the business does not cover all the necessary costs, as well as the ones associated with customers, a business continuity plan is necessary to deal with such situations.
What Are The Benefits Of Having A Business Continuity Plan?
The disasters in a business can be of any size and degree and can even be catastrophic for the business. Hence, a business continuity plan is one of the most essential things you can have for your business. The plan will help you to identify all the major risks that can affect the work processes of your company.
According to Investopedia,
“BCP is typically meant to help a company continue operating in the event of threats and disruptions. This could result in a loss of revenue and higher costs, which leads to a drop in profitability. And businesses can’t rely on insurance alone because it doesn’t cover all the costs and the customers who move to the competition.”
The following are some of the major benefits of a business continuity plan:
- It helps to continue operating even in times of disaster. However, it is different from a disaster recovery plan.
- Helps in improving risk management of the company.
- It can stop disruptions in the organization from spreading.
- Helps to mitigate downtime of business technology and networks.
- It helps to save a lot of money, time, and resources.
Business Continuity Plan – Steps To Create
Here are some of the major steps you will need to follow if you want to create a business continuity plan:
1. Business Impact Analysis
According to Investopedia,
“An important part of developing a BCP is a business continuity impact analysis. It identifies the effects of disruption of business functions and processes. It also uses the information to make decisions about recovery priorities and strategies.”
Here, your business managers will need to identify the functions of the plan as well as related resources for the business, especially the ones that are sensitive to time.
2. Recovery
In this portion of the plan, the planner will need to identify the steps and implement them. This will include the steps for recovery as well.
3. Continuity Team
You will need to create a continuity team here. The job of the team will be to devise a plan to manage the disruption of the plan.
4. Continuity Training
You will need to train and test the continuity team here. The members of the team will also need to complete various exercises for the application of the plan.
Read More: Intrapreneurship – Definition, Importance, Duties, And Responsibilities
Summing Up
Hope this article was helpful for you in getting a better idea of what a business continuity plan is and how it can allow your organization to recover quickly from disasters or, in the best cases, prevent them. The plan is a great option to keep your personnel prepared, save your assets, and ensure the business starts functioning fast.
However, you will need to test your business continuity plan from time to time to ensure that there are no gaps in it. To find out gaps, you can create dummy situations or drills with your employees. Do you have any more recommendations on how to create the best business continuity plan? Share your ideas with us in the comments section below.
Read Also:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
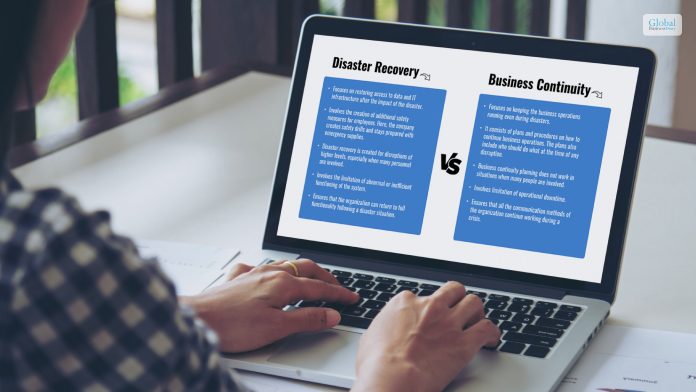
Disaster Recovery Vs Business Continuity – What Are The Differences?
Disaster recovery vs business continuity: Which one is important? - The short answer is “Both.” It depends on the situation you are dealing with. Most companies operate by assuming that their workplaces will maintain their consistent state with changing times. Hence, they try to find comfort in daily routines and rhythm of work. However, there are certain events when a business might face disruption. Hence, businesses need to have a disaster recovery plan and a business continuity plan in place to ensure that the business recovers faster when it comes across a negative situation. In this article, you will learn about disaster recovery and business continuity in general. However, the focus of the article will be on the differences between the two. Apart from those differences, we will also discuss the major similarities between them as well. In addition to this, we will, in brief, share with you how each of these works and how to implement them. Hence, to learn more, read on through to the end of the article. Disaster Recovery Vs Business Continuity – What Are They? If you want to prepare for disruptions in business, you will need to create various strategies and plans, following which you will be able to ensure that the core business functions are intact. This can help the business to come back faster from the uncertain negative consequences it just faced. What Is Disaster Recovery? Amazon Web Services defines disaster recovery as such - “Disaster recovery is the process by which an organization anticipates and addresses technology-related disasters. The process of preparing for and recovering from any event that prevents a workload or system from fulfilling its business objectives in its primary deployed location, such as power outages, natural events, or security issues.” To measure the targets of disaster recovery, two factors are taken - Recovery Point Objectives (RPO) and Recovery Time Objectives (RTO). The failures for which companies make disaster recovery plans are mostly larger-scale disaster events. The plan includes various procedures and policies for the company so that it can recover quickly from the disaster by following them. What Is Business Continuity? According to the Business Continuity Institute, “Business continuity is about having a plan to deal with difficult situations so your organization can continue to function with as little disruption as possible. Whether it’s a business, public sector organization, or charity, you need to know how you can keep going under any circumstances.” You will need a business continuity plan, too, in case of a disaster situation. However, the continuity plan is to deal with the disaster situation so that the organization is able to continue its functioning with little to no disruption. However, you will need to understand here that a business continuity plan does not work at times of a large program or a disaster, which affects the company a lot. It also does not work when a large number of people are associated with a single plan. Hence, many big companies make business continuity plans for each of their departments. This makes each department implement the plan as per its needs. Disaster Recovery Vs Business Continuity – Major Differences Disaster RecoveryBusiness ContinuityFocuses on restoring access to data and IT infrastructure after the impact of the disaster.Involves the creation of additional safety measures for employees. Here, the company creates safety drills and stays prepared with emergency supplies.Disaster recovery is created for disruptions of higher levels, especially when many personnel are involved.Involves the limitation of abnormal or inefficient functioning of the system.Ensures that the organization can return to full functionality following a disaster situation.Focuses on keeping the business operations running even during disasters.It consists of plans and procedures on how to continue business operations. The plans also include who should do what at the time of any disruption.Business continuity planning does not work in situations when many people are involved.Involves limitation of operational downtime.Ensures that all the communication methods of the organization continue working during a crisis. You can see from this table that both disaster recovery and business continuity are complementary to each other. Businesses need to combine both plans to ensure they are prepared for disastrous events. Disaster Recovery Vs Business Continuity – Major Similarities The following are some of the major similarities that you will find between disaster recovery and business continuity: Both are proactive strategies that enable a business to stay prepared for uncertain and disastrous events. Both plans allow the company to minimize the effects of the disaster before it actually occurs and affects the business. Both work quite well in situations of natural and man-made disasters. However, the result of their implementation depends on the situation. Professionals need to review both plans on a regular basis, and some of them need revision with the evolving situation of the organization. How Do Disaster Recovery And Business Continuity Work? According to the University of Central Florida, “Having business continuity and disaster recovery plans in place can help companies minimize the consequences of a catastrophic event. They can also provide peace of mind; employees and business owners alike may feel more comfortable in a work setting where there are clear policies for how to respond to disasters.” To implement these plans for the recovery of the business, the organization needs to create/hire crisis management professionals. These professionals will be responsible for developing and implementing such plans. Apart from that, they are also responsible for evaluating and revising them as per needs and training the employees of the organization to stay prepared. Final Thought Disaster recovery vs business continuity: Hope this article was helpful for you in getting a better idea of both of these terms and how they operate in the organizational setting. Disaster recovery works in situations when the disruption is big and many people are involved. On the other hand, business continuity planning is to ensure business operations are continued in disruptions. Do you have any more recommendations regarding when and how to implement a business continuity plan and a disaster recovery plan? Share your thoughts and ideas with us in the comments section below. Read More: Entrepreneur : Who Coined The Term ‘Entrepreneur’? Intrapreneurship – Definition, Importance, Duties, And Responsibilities What Is a Franchise, And How Does It Work? – Examples, Benefits & More
Sep 11, 2023

The Rising Importance Of Vape Detectors In Business Environments
As the trend of vaping continues to grow, businesses are increasingly concerned about its impact on their premises. Vaping, while often perceived as a less harmful alternative to smoking, still presents various challenges in public and private settings. This concern has led to the rising importance of vape detectors in businesses, a technology that’s becoming crucial in maintaining health standards, adhering to regulations, and ensuring a comfortable environment for all patrons and employees. Addressing Health and Safety Concerns The primary reason businesses are turning to vape detectors is to address health and safety concerns. Vaping can release aerosols and chemicals that may affect indoor air quality and potentially harm non-vaping individuals, particularly in enclosed spaces. This is especially concerning in environments like restaurants, offices, or stores, where maintaining a clean and safe atmosphere is crucial for both employees and customers. By installing vape detectors, businesses can quickly identify and address vaping incidents, thereby ensuring a healthier environment. Complying with Regulations and Company Policies Another significant factor is compliance with regulations and company policies. Many places have strict no-smoking policies that include vaping, but enforcing these rules can be challenging without the right tools. Vape detectors help businesses ensure that these policies are adhered to effectively. They serve as a deterrent against policy violations and provide a means to enforce rules consistently. Benefits of Implementing Vape Detectors in Businesses BenefitDescriptionImpact on BusinessImproved Air QualityReduces aerosols and chemicals from vapingCreates a healthier environmentPolicy EnforcementAids in upholding no-smoking/vaping policiesEnsures compliance and reduces liabilityEnhanced Customer ExperienceMaintains a comfortable environment for allIncreases customer satisfactionEmployee Well-beingProtects employees from second-hand vaping effectsBoosts morale and productivityTechnological DeterrentServes as a deterrent against vapingReduces frequency of vaping incidents This table illustrates the benefits of implementing vape detectors in business environments, highlighting how they contribute to overall health, policy compliance, customer satisfaction, and employee well-being, and act as a technological deterrent. The Role of Vape Detectors in Customer and Employee Satisfaction Customer and employee satisfaction are paramount for any business. Vape detectors play a crucial role in ensuring that both these groups enjoy a comfortable, vape-free environment. For customers, especially those who are health-conscious or sensitive to aerosols, a vape-free environment can significantly enhance their experience. For employees, working in a vape-free environment means a cleaner, safer workplace, which can lead to increased job satisfaction and productivity. Related: Enhancing Employee Retention And Engagement With An Effective Appreciation Program Navigating the Challenges of Vaping in Shared Spaces In addition to the direct benefits of installing vape detectors, businesses must also navigate the broader challenges of vaping in shared spaces. Vaping, often less detectable than traditional smoking, can be a discreet activity, making it difficult to monitor and control in public areas. This presents a unique challenge for businesses that strive to maintain a certain standard and atmosphere in their premises. Vape detectors provide a solution to this challenge by discreetly monitoring the environment and alerting management to any vaping activity. This technology allows businesses to proactively manage their space without constant physical oversight, ensuring that all patrons and employees can enjoy a comfortable and respectful environment. It represents a balance between respecting individual choices and upholding the collective well-being of all those within a shared space. Conclusion The integration of vape detectors in businesses is a response to the evolving landscape of public health and safety concerns associated with vaping. By ensuring cleaner air quality, adhering to health regulations, enhancing customer and employee satisfaction, and effectively enforcing no-vaping policies, vape detectors are becoming an essential component of modern business operations. As vaping continues to be a prevalent habit, the use of such technology will likely become more widespread, underscoring businesses’ commitment to creating safe and comfortable environments for everyone. Read Also: 8 Best Practices For Managing Remote Teams The Importance Of Keeping Your HR Team Certified Seven Potential Tax Credits Available To Small Businesses In 2023
Dec 07, 2023

LLC VS Sole Proprietorship: Major Differences That You Need To Know
LLC Vs Sole Proprietorship: What is right for you? - Whether you are starting a new business or an online store, you will need to choose the right legal structure for your business based on your choice and needs. Both LLCs and sole proprietorships are quite common. The business model you choose might have a big impact on how you run your company, especially as seen from the tax, legal, and management perspectives. In this article, you will learn about two major types of business structures - LLC and Sole Proprietorship. We will first discuss each of these business structures individually in brief. Finally, we will share the major differences between the two in regard to structure, function, role of the owner(s), etc. Hence, to learn more about these two types of business structures, read on through to the end of the article. What Is An LLC? According to Investopedia, “A limited liability company (LLC) is a business structure in the U.S. that protects its owners from personal responsibility for its debts or liabilities. Limited liability companies are hybrid entities that combine the characteristics of a corporation with those of a partnership or sole proprietorship.” The LLC is basically a corporate structure where the owners of the organization protect their place from the liabilities of the company. Here, the company is a different entity from that of the owner. In case of debts, liabilities, and lawsuits, the structure of the organization protects the owners by making them limitedly liable. However, what the regulation of the LLC is depends on the state in the US where your business is located. Apart from banks and insurance companies, any individual or entity can be a member of an LLC. Whatever profits LLCs make, they do not pay taxes directly on the profits. The profits and losses of the LLC are passed through to members of the organization, that report on their individual tax returns. Read More: Micro vs Macro Economics: What’s The Difference? What Is A Sole Proprietorship? According to the Forbes Advisor, “A sole proprietorship is an unincorporated business that’s owned by the individual running it. A sole proprietorship is the default choice for anyone who runs a business but hasn’t set up another formal business structure like an LLC. As a sole proprietor, there’s no separation between your personal and business assets and expenses. You are personally responsible for all your business’s debts and obligations.” This is the simplest form of business. It is basically an unincorporated business with only one owner. Apart from that, this business is also the least expensive to form. A business, by default, is a sole proprietorship if an individual operates the business on his own. For example, if you are an individual shopkeeper, freelancer, retailer, or online business owner, you automatically become a sole proprietor of the business. In this case, you will not need to adopt a business structure from the first. Furthermore, if the name of the business is the same as the name of the owner, then the business is typically a sole proprietorship. However, any sole proprietorship can also operate under a trade name or a brand name. The best thing about a sole proprietorship is that the business and the business owner are not legally separate. Hence, if the business incurs debts, the owner of the business is personally responsible for making the payments for the debt. LLC Vs Sole Proprietorship: What Are The Differences? The major difference is rightly noted by Wall Street Mojo - “LLC is a separate legal entity run by its members having limited liability, and it is mandatory for an LLC to get registered, whereas sole proprietorship is a sort of business arm of an individual which is not separate from its owner; hence its liabilities are not limited, and there is no need to register sole proprietor.” The following are the major differences between LLCs and sole proprietorships: Limited Liability CompanySole ProprietorshipThe company has more than one owner.A single owner of the business runs a single unit.The business and the members are separate entities in an LLC structure.The business and the owner are not separate in a sole proprietorship.The members of the business need to register as per state regulations if they want to form an LLC.The owner of a sole proprietorship needs to ensure that the business name is not the same as another business in the state.It costs around $100 to $800 to form an LLC.There are no costs to form a sole proprietorship.The taxation method is single. A single applicable rate is charged to the members.The taxes of the sole proprietorship are charged from the income of the sole owner. The owner’s taxes and the business taxes are the same here.The members of the LLC are liable only as far as their investments and shares in the business.The owner of a sole proprietorship is fully responsible for the entire business. Furthermore, the owner also does not get liability protection.There is little paperwork to be done.There is no paperwork involved. The best option for you, if you are starting out as a business owner, is to go with a sole proprietorship. If you want to grow a bit more, then changing the structure of your business to an LLC will be a better option. Read More: Vertical vs Horizontal Integration: What Are The Key Differences? Final Thoughts LLC vs Sole proprietorship - Hope you have understood the differences between these two types of business structures. If you are starting out as a business owner, consultant, or freelancer, then sole proprietorship is the easiest and simplest option for you. The paperwork that is required is very minimal, and there are no big costs associated. However, if the business grows bigger and you need legal protection for yourself and your personal assets, LLC is the option to go for. In case of bankruptcy or a legal lawsuit against the business, you do not get involved. Furthermore, there is tax flexibility too. What do you think is the better option of the two? Share your opinions with us in the comments section below. Discover More Business Insights Below! What Is Net Operating Income? How To Calculate NOI? Vertical vs Horizontal Integration: What Are The Key Differences? What Is A Holding Company? – Importance, Operation, And Pros & Cons
Oct 25, 2023
What Is Risk Management? – Find Out How To Manage Risks in Business
What is risk management? - Simply put, it is the process by which businesses identify, assess, and control the various risks that threaten the growth, capital, and earnings of the organization. The risks for the organization can come from a variety of sources, both internal and external. These can be financial problems, legal problems, management errors, accidents, tech issues, economic problems, disasters, and many more. In this article, you will learn about risk management in general and will get a good understanding of its essentiality in business. Furthermore, you will also learn the importance of risk management and how it can shape a business. Finally, we will share with you some of the best practices of risk management, with the help of which you can ensure a proper risk management system in place. What Is Risk Management? According to IBM.com, “Risk management is the process of identifying, assessing and controlling financial, legal, strategic and security risks to an organization’s capital and earnings. These threats, or risks, could stem from a wide variety of sources, including financial uncertainty, legal liabilities, strategic management errors, accidents, and natural disasters.” Risk management is important for situations when an unforeseen event (internal or external) pushes the organization into a threatening situation. It can also be an economic situation where an unexpected surprise in the market can heavily impact your business. Hence, having a risk management framework for your business is really essential. The risk management framework will help you mitigate the risks in a better manner. Even if the risk affects your business, the risk management system will enable you to deal with that risk better. External risks are out of your control, and you cannot do a lot to receive the impact of the risks. However, you can do many things to stop and mitigate the internal risks for your business. You will need to anticipate and prepare for the risks, despite the size of the business or the level of impact of the risk in the business. Read More: Intrapreneurship – Definition, Importance, Duties, And Responsibilities Why Is Risk Management Important? According to Investopedia, “Risk management has always been an important tool in running any business, particularly when a market experiences a downturn. In any economic environment, an unexpected surprise can destroy your business in one fell swoop if you don’t have the right risk management strategies in place to prevent, or at least mitigate, the damage from that risk.” There are many risks that have enough potential to destroy the business and its operations. Hence, as a manager or CEO of the organization, you will need to identify what are the risks that pose threats to the operations of your business. It does not matter whether the business is a startup or an established one. Risks can impact the business a lot. Even if a risk starts impacting a business, a business that is well-prepared can minimize the impact of the risk on the business’s earnings. With the impact of the risk, the business can also lose a lot of time, productivity, and even customers. Hence, the identification of the risks of the business should be a key part of the business’s strategy and planning. You can identify risks in a number of ways once you implement a proper risk management system in the organization. What strategies you will employ to identify those risks should rely on the specific business activities of the company. What Are The Best Ways To Manage Risks? Having a proper risk management system in place is one of the major necessities. However, people still have their own biases. According to Harvard Business Review, “Multiple studies have found that people overestimate their ability to influence events that, in fact, are heavily determined by chance. We tend to be overconfident about the accuracy of our forecasts and risk assessments and far too narrow in our assessment of the range of outcomes that may occur.” Here are the steps that you will need to take to ensure that you have a proper risk management system in place: 1. Risk Prioritization If you have multiple risks, prioritizing the top ones will help you to deal with them as per their impact and possibility of impact. 2. Having A Business Insurance Once you purchase insurance, you are transferring the risks of the company to insurance companies. Furthermore, you are not paying a lot of costs. 3. Becoming An LLC If you do not want to be personally liable for the debts of the company, change your company’s structure to a Limited Liability Company (LLC) or a Corporation. 4. Quality Assurance Quality assurance of products and services will help your business in increasing its reputation. Ensure to test them before customers purchase them. This will allow you to make all the necessary adjustments beforehand. Also, ensure that your testing methods are foolproof. 5. Get Away From High-Risk Customers Implement a policy in your organization that the company will not entertain customers with poor credit. Even if the company deals with them, the customer must pay ahead of time. This shall lower the complications for the business in the long run. 6. Growth Control Training your employees is of the highest importance here. To sell your products and services, if you set big goals for your employees, they shall be tempted to take uncalculated risks. This can make things go wrong and damage your company’s reputation. 7. Risk Management Team Apart from paying an outside company to manage the risks in your business, consider having a risk management team of your own. To do this, you can appoint some of your current and experienced employees to work in risk management. Read More: Entrepreneur : Who Coined The Term ‘Entrepreneur’? Final Thought What is risk management? - Risk management basically creates insurance for the company from within and is really important to ensure the success of the organization. If you want to implement a system within your company, consider following the aforementioned steps. To shape a better strategy for your business, you will need to get a better idea of the business and the industry by diving deeper. Do you have any more recommendations regarding better risk management strategies? In that case, consider sharing your thoughts and views with us in the comments section below. Read Also: What Is Social Entrepreneurship? – Steps To Become A Successful Social Entrepreneur Business Entrepreneurship – What Should You Know Before You Start A Business? What Is a Franchise, And How Does It Work? – Examples, Benefits & More
Sep 02, 2023