Financial Planning Tips For Different Stages Of Life

Let us tell you something that can change your perspective on handling finances. It may sound cliché, but it has never been truer than ever – planning always pays off regardless of where you are in your life right now.
Did you know that taking control of your hard-earned cash at every stage of your life could greatly impact where you want to be financially? That’s right; we are talking about the concept of financial planning for different stages of your life. From embracing adulthood to reaching old age, here’s why it matters so much!
You go through different stages in your life and might encounter new challenges and goals at various points along the way. So, whether you are a government employee, just graduated from school, hit mid-life stability, or are getting ready to kick back in old age, understanding the nuances of your journey will help you make smarter decisions when it comes to your finances. And guess what? We have got you covered with all things related to financial planning across these distinct life phases. Are you ready to take charge and start building your roadmap to prosperity? Buckle up because our next stop is where the magic happens!
1. Employment
The nature of your job plays a crucial role in financial planning. Every organization offers different benefits, including insurance options and provident funds. However, financial planning for Govt. Employees may involve in some particular issues. You might have chosen this career path due to the attractive benefits packages offered, including comprehensive healthcare coverage and generous pensions. Still, you may also confront special financial issues specific to government employment. Let’s take a closer look at some crucial variables to bear in mind when budgeting your money.
A. Benefits Evaluation (Healthcare & Pension Plans):
When comparing private sector positions to government jobs, the latter typically offers competitive salaries alongside robust benefits packages. Adequately assessing all possibilities within healthcare and pension options allows for customization to fit individual circumstances.
B. Retiree Status Planning:
Reaching retirement age marks a significant milestone for anyone. For civil servants, there are particular guidelines that must be followed to attain retirement status. Determining the correct timeframe and milestones will enable the optimal use of certain benefits like annuities and deferred compensation.
C. CSRS vs. FERS Comparison:
As a government employee, you fall under either CSRS (Civil Service Retirement System) or its successor program, FERS (Federal Employee Retirement System). Each system has advantages and disadvantages; understanding their differences is crucial for selecting the most suitable option.
D. Young Adult Life
As you enter adulthood, the world opens up like a freshly blossomed flower, offering myriad possibilities. You might find yourself navigating entry-level jobs while trying to build a solid credit score. With little experience and even less knowledge, managing money becomes an intimidating task. However, this is the time when smart financial choices set you apart from others. Starting with simple steps such as crafting a basic budget, monitoring expenditures, and setting aside cash for unexpected events, lays the groundwork for a secure future.
2. The power of compounding interests
So, have you paid off those hefty student loans yet? Well, hang tight because now begins the arduous battle against the burden of repayment. Remember, a thorough approach to tackling debt includes exploring multiple income sources, setting realistic targets, prioritizing expenses wisely, and seeking advice when needed.
The beauty lies in exploiting the power of compounding interests, i.e., allowing your money to grow exponentially over time. Plus, who doesn’t love having extra cash stashed away for a rainy day? Beginning to save diligently helps avoid potential financial disasters down the line.
Leverage low risks
With time comes the luxury of witnessing your investments yield rich dividends. Don’t wait until you reach midlife to jumpstart your portfolio; instead, leverage low risks early on. Learning about asset allocation, balancing stocks vs. bonds, researching companies, and other complex investment techniques form the basis of successful long-term growth.
3. Mid-Career Professionals
This stage brings stability and predictable routines but requires consistent monitoring of finances. Reflect on previous errors and stay committed to ensuring similar pitfalls don’t arise in the near future. Analyzing well-thought-out long-term plans and assessing whether they have been met serves as an excellent reality check. It’s never too late to pivot or adjust said objectives.
Budgetary reviews now include higher net worth and larger monthly savings than before. Savvy savers will focus on boosting retirement accounts through maximized employer matches, IRA contributions, Roth conversion opportunities, and after-tax investments. Umbrella liability insurance coverage can help guard against legal issues triggered by unexpected events.
High-interest credit card balances often get transferred to home equity lines, reducing interest charges owed by consolidating obligations. College savings plans also demand careful consideration to secure the best possible educational options for loved ones. With careful deliberation and expert guidance, one can navigate this stage with relative ease and confidence while maintaining momentum toward meeting established fiscal targets.
4. Old-age
Retirement represents the culmination of lifelong hard work and dedication. However, it is crucial to ensure adequate preparation has occurred beforehand to avoid any unwanted surprises. At this stage, carefully evaluate the value of accumulated assets and the potential impact of inflation or market volatility on net worth.
Importance of Estate Planning and Retirement Decision-Making
Now more than ever, having up-to-date estate plans in place becomes paramount, especially if looking to distribute inheritance among heirs in an orderly manner. Carefully contemplate the decision to continue working or transition fully into retirement, including decisions surrounding when to start receiving Social Security benefits to optimize lifetime payouts.
Maximizing Retirement Resources: Identifying Potential Shortfalls and Preparing for Healthcare Needs
Additionally, take stock of expected post-retirement spending requirements and compare those figures against currently projected financial resources to identify potential shortcomings. Pay attention to Medicare enrollment and appropriate Part D prescription drug coverage choices.
Building a Lasting Legacy
Lastly, focusing efforts on legacy building through means such as philanthropy or intergenerational wealth transfers will help create lasting impressions beyond mere monetary measures alone. By addressing these critical areas, entering old age provides a solid foundation for living happily and purposefully during this exciting chapter of life.
Conclusion
As the old saying goes, “Failing to plan is planning to fail.” That couldn’t be more true when it comes to managing our finances through every stage of our lives. From young adulthood to retirement and beyond, having retirement planning services and plans is crucial to achieving both short-term and long-term goals.
Remember that it’s never too late to start fresh and implement positive changes. Make a habit of regularly reviewing and updating your financial blueprint to adapt to evolving needs and goals. By staying organized and proactive, you’ll enjoy greater peace of mind, stronger overall stability, and happier days ahead.
Read Also:
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
Reducing Bad Debt: 5 Debt Collection Strategies You Must Implement
Debt and dues collection are crucial for B2B organizations because they rely on credit for their operations. Debt collection entails obtaining payments from clients in accordance with a pre-established payment schedule for the goods or services delivered. However, effective debt collection methods are required because several factors may impede the collection process. These methods can include precautions and solutions for when a debt becomes problematic, and no payments are made. It is crucial to recover customer debts because the money made from debt collection can be used for everyday operations. Businesses that don't timely collect debts risk suffering sizable losses from bad debts. The improvement of cash flow and the development of stronger client relationships both depend on a strict debt collection strategy. Two of the most difficult parts of revenue cycle management (RCM) are bad debt and collections. What Are The Challenges Faced By Debt Collection Teams? Managing past-due accounts while taking care of all the accounts on their work list presents difficulties for collectors. Unreliable and out-of-date data can result in time loss, strained customer relationships, and high DSO. Inadequate communication is essential for customer collaboration, but collectors might give non-critical clients more attention than those who need it. Moreover, in cases of international debt collection, the differences in policies and currencies can often stand as a hurdle in the way of repaying debts. As static parameters like due dates and invoice values may not be adequate to handle dynamic changes in a customer's accounts payable functions, improper customer prioritization is another issue. To ensure effective operations and maintain a strong customer relationship, finance leaders must continuously evaluate the maturity of the collections process. Strategies To Overcome The Challenges Of Debt Collection Given below are some of the most sought-after strategies used by a company and commercial debt collection agency— 1. Timely Invoices To guarantee a successful collection, sending timely and accurate invoices is crucial, giving customers enough time to plan and gather their finances. Being proactive can significantly reduce waiting time and improve productivity. Although automated debt collection software can speed up the process, it's essential for the sales and collections teams to collaborate and avoid duplication of effort to improve client satisfaction. To prevent errors that could delay payment, verifying every detail of an invoice before sending it is necessary. Double-check the unit price and rates, the appropriate person's address, the items and descriptions, and the contact information. This will help reduce errors that could cause payment delays and ensure a smoother collection process. Implementing these strategies can decrease your collection costs, increase customer satisfaction, and save time. 2. Prevent Communication Gaps Rather than chasing after bad debt, focusing on preventing it is crucial. This can be achieved by implementing responsible credit policies that will reduce defaults and increase collections. Before making any credit-based sales, it's vital to ensure that your sales team is well-informed about the credit policy and the necessary procedures for credit terms. Open communication between the sales and collection teams is essential to improve collaboration and collections. Patients can also contribute to reducing bad debt and increasing collections by staying informed about their bills and payment options. To facilitate this, reminders, statements, and notices can be sent through various channels such as phone calls, emails, texts, or portals. It's crucial to explain any charges, discounts, or adjustments and address any questions that may arise. To accommodate patients, consider offering flexible payment options, such as credit cards, online or mobile payments, payment plans, or financial aid. Patient education and communication can foster engagement and satisfaction, ultimately leading to better collections. 3. Planning Ahead Two ways businesses can increase collections are by prioritizing customers and keeping an eye on accounts' aging and the amount owed. AI-based collections software can assist businesses in scheduling and prioritizing customer calls, accelerating the recovery of receivables by identifying high-risk clients, predicting payment schedules, and providing specialized dunning strategies. Patients' bills and payment options can be explained to them, lowering bad debt and increasing collections. Giving patients flexible payment options can increase their satisfaction and engagement. Higher collections may also result from patient education and communication initiatives. Software for automated accounts receivable collections can aid in simplifying this issue. By helping to develop collection strategies based on customer payment history and behavior, AR automation software can save time and help collection agents know where to go, speeding up the collection process. Businesses can increase collections and patient satisfaction by prioritizing accounts and implementing patient communication and education. 4. Effective Documentation Improving coding and documentation practices is key to reducing bad debt and increasing collections. This can be achieved by using standardized codes, following coding standards, gathering relevant clinical data, and reviewing claims before submission. By doing so, it's possible to increase reimbursement rates and lower the amount of money owed. Moreover, lenders can make use of CRM to effectively track and follow up with defaulters, predict recovery, and facilitate faster debt collection. Keeping accurate records is crucial for tracking unpaid debts, prioritizing debt recovery efforts, and identifying critical dates such as the last payment dates, which help determine whether a debt is statute-barred. Dishonest clients often deny their debts, so recording transactions at every stage is essential to avoid such tactics and ensure accurate debt collection. 5. Sign Up Contracts And Agreements Many small businesses avoid using service agreements and contracts with their customers because they worry it might put them off. However, leaving disputes unresolved can result in significant legal and financial liabilities. Although contracts can be complex legal documents, they are essential in safeguarding both parties by ensuring they understand and fulfill their obligations. Service agreements, on the other hand, are less formal and may not be enforceable in court if a dispute arises. Having a written agreement signed by both parties is best because it clearly outlines the terms of the agreement. Contracts and service agreements are crucial for maintaining a positive working relationship with customers while also safeguarding the interests of both parties. Role Of A Debt Collection Agency A commercial debt collection agency is a company that helps lenders recover overdue or unpaid debts. They work closely with lenders to create payment schedules, locate debtors, and negotiate debt payments. Collection specialists, also known as collections agents, act as intermediaries between creditors and customers. They keep a close eye on accounts to identify past-due payments, report collection activities, respond to client inquiries, and establish repayment plans. They may also discuss debt settlements for repayable debts. Read Also: contribution margin: what is it, overview, examples, and more business risks – how to identify, manage, and reduce them? the best risk mitigation techniques for your business
Oct 02, 2023
Capex Vs Opex: Essential Points Of Difference
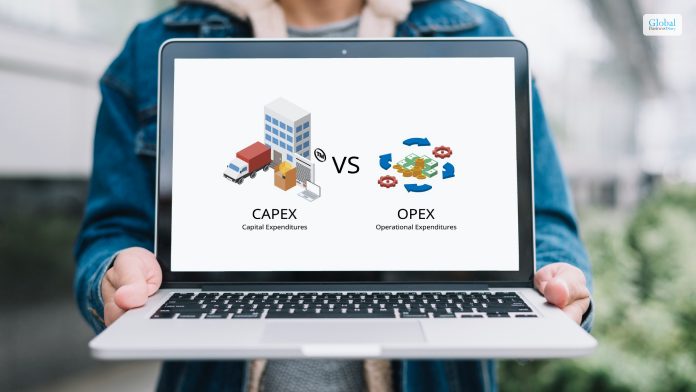
A company has to pay off different kinds of expenses to run its business smoothly. Capex vs Opex is one of the popular expense differentiation you must know. Among them, two kinds of expenditures are quite prominent in this regard. First is the Capex, and second is the operating expenses. Most of the time, these costs can be one, and sometimes they can take the shape of recurring expenses. You must follow the correct process that can assist you in getting things done in perfect order. Micromarketing techniques can work well here. The capital expenditure of a company will occur once, while the operating expenses will keep on occurring all the time. If you are a business owner, you must know the core points of differences between the two concepts. Essential Points Of Difference Between Capex vs Opex There are several points of difference between Capex vs Opex. It will offer you the complete insight once you go through the complete article. You need to know the reality while making the differentiation between the two concepts of business./ 1. Nature Of Expenses Capex vs Opex has some core differences in the nature of their expense model. Capital expenditures or Capex are investments in assets that provide long-term benefits to a company. These expenses are typically for acquiring, improving, or maintaining assets such as property, equipment, machinery, or infrastructure. Operating expenditures are day-to-day expenses incurred in running a business. These include costs for salaries, utilities, rent, marketing, repairs, and other ongoing operational expenses. You must consider these facts from your end while making the differences between the two concepts. 2. Duration Of Benefit Capital expenditures provide benefits over an extended period, usually beyond one fiscal year. They contribute to the company's future productivity, efficiency, or revenue generation. Capex vs Opex has some significant points of differences that you must know while you make the comparison. Operating expenditures are incurred for immediate use and provide short-term benefits. They are essential for maintaining regular business operations and generating immediate revenue. It will give short-term and regular benefits to your company. 3. Treatment In Financial Statements Capital expenditures are recorded as assets on the balance sheet and depreciated or amortized over their useful life. Depreciation or amortization expense is then reported on the income statement over time. Operating expenditures are immediately shown on the income statement in the period they are incurred. They directly impact the company's net income for that period. You need to identify the perfect solution that can make things easier for you to reach your goals with ease. 4. Tax Treatment Capital expenditures might be eligible for tax benefits such as depreciation or amortization deductions over time, reducing taxable income. Capex vs Opex, you must consider things at your end while reaching your objectives. Operating expenditures are fully deductible in the year they are incurred, providing immediate tax benefits. You should get through this difference to have a better idea of it. Ensure that the scope of errors is as low as possible. 5. Impact On Profitability & Cash Flow While CapEx affects profitability indirectly through depreciation expenses. It has a significant impact on cash flow at the time of purchase or investment. You cannot afford to make things work in the wrong direction from your counterpart. On the other hand, Operating expenditures directly affect profitability by reducing net income and also impact cash flow in the period they occur. Effective planning can boost the chances of reducing the expenses of your business. 6. Decision Making & Budgeting Capital expenditures involve strategic decisions as they impact the company's long-term growth and productivity. Budgeting for CapEx requires careful planning and consideration of future benefits. You should know the core points of differences between Capex vs Opex. It will assist you in attaining your goals with complete ease. Operating expenditures are part of routine budgeting and are necessary for maintaining day-to-day operations. They are generally more predictable and recurring. Without proper application of the strategies, things can turn worse for you. Examples Of Capex Expenditure There are several examples of Capex expenditure that you should know at your end. It will help you to get a better insight into it. Let’s find out some of the core examples of the Capex Expenditure that can make things easier for you. Machinery, manufacturing plants, and equipment. Computers. Building Improvements. Trucks and vehicles. The contribution margin of the company plays a vital role here. You should pay it from your end to meet all the expenditure. Examples Of Opex Expenditure There are several examples present for Opex expenditure that you must know at your end. Some of the core examples of it are as follows:- Salaries and wages. Rent and Utilities Legal and accounting fees. Overhead costs. Business travel. Property expenses. Interest on debt. Research and development expenses. You can easily make the market segmentation with the help of the differences between capex vs opex to meet the requirements. How To Reduce Capital Expenditure? There are several techniques you can employ to reduce the capital expenditure of your company to a great extent. You must follow the correct process in this regard to have a better idea of it. 1. Evaluate The Asset Needs Conduct a thorough assessment of current assets to determine if there are underutilized or redundant assets. Selling or repurposing such assets can free up capital and reduce the need for new investments. 2. Leasing Vs Buying Consider leasing equipment or assets instead of purchasing them outright. Leasing can lower initial costs and shift maintenance and upgrade responsibilities to the lessor. 3. Prioritize Essential Investment Focus on essential investments that directly contribute to core business operations or strategic growth. Prioritize projects that offer the highest return on investment (ROI) and align with long-term business goals. 4. Implement Of Efficient Technology Invest in technology that streamlines processes, reduces manual work, and improves efficiency without significant capital outlay. Cloud-based solutions or software-as-a-service (SaaS) models often have lower upfront costs. 5. Outsource Non-Core Functions Consider purchasing refurbished or used equipment instead of new. Often, these options come at a lower cost while still providing adequate performance and reliability. Final Take Away Hence, if you are making the differences between the two concepts of capex vs opex, then the mentioned points can prove to be useful for you. Try to reduce your expenses as much as possible. It will reduce your debts to a great extent. You can share your views and opinions in our comment box. It will help us to know your take on this matter. Once you follow the correct process, things are going to be easier for you. The application of the correct strategy can make things work for you. Continue Reading For More Business-Related News!! How To Buy An LLC? – Steps To Follow How To Become A Strategy Consultant? Roles & Responsibilities What Is A Sales And Purchase Agreement For Business? – Let’s Find Out
Nov 26, 2023
StashFin Personal Loan Review – Interest Rates, Loan Amount, Eligibility, And More
StashFin offers instant personal loans at interest rates of 11.99%, with loan amounts reaching up to 5 lakhs INR. The loan offers are available for up to 4 years of time. The best part is that you can get an instant personal loan as fast as 4 hours of time. Only minimal documentation is required to get a loan. However, these factors are applicable when you are eligible for the loan. In this article, you will get to know about StashFin personal loans and the variety of necessary details about the loan provider. The details will include the rates of interest, eligibility, and other important information related to loan offerings by the company. Finally, we will give you some details of customer reviews which can be helpful for you to get a better idea of StashFin. Hence, to get a full idea of the loan offerings of this company, read on through to the end of the article. StashFin – What Do They Offer? StashFin is a platform that offers personal loans to salaried and self-employed individuals. You can apply for loans both through the website and also the StashFin personal loan app. The types of loans offered by StashFin include Marriage loans, Cash loans, Small loans, Medical loans, Travel Loans, Home Renovation loans, Shopping loans, Personal loans, and Debt Consolidation loans. Loan AspectsWhat StashFin Offers You?Loan AmountUp to INR ₹ 10 lakhLoan TenureIt can be up to 4 years, depending upon eligibility and the loan amount.Rate of Interest On Loans11.99% – 59.99% p.a. (per year) depending on the type of loan borrowed.Loan Processing FeesProcessing fees depend upon the loan amount. However, it can extend up to 10% (excluding GST) of the amount on each loan.- 0% – 10%, excluding GST (Borrowers should pay a processing fee on the withdrawn amount every time they load their StashFin Card using the StashFin App).Collateral or MortgageDepends on the type of loan applied for.Bounce Charges₹ 500 on every bounced cheque, NACH, or failed EMI payment.Loan Review TimeIt can be as less as 4 hours.Late Payment Of The LoanA loan default or a late payment will not allow a borrower to redeem rewards.Loan RepaymentThe repayment period is up to 36 months. All loan payments are made through EMIs via electronic payments. Read More: GGP Share Price Forecast: Everything You Should Know How To Apply For A Loan From StashFin? If you want to apply for StashFin loans, you will just need to download the official app or visit the website and hit the "Apply Now" button. Once you click the button, you will get to a page where you will need to enter your name, mobile number, pin code, and PAN. Later, you will need to fill up a form and provide all your proofs. Once your documents and your credit record are verified, you can get a loan as quickly as 4 hours. StashFin – What Is The Loan Eligibility? The following are the major eligibility requirements that a borrower needs to comply with to avail of loans from StashFin: Loan RequirementsEligibilityAge of the borrowerMinimum 18 yearsStashFin credit scoreA better credit score (that is, above 750 for CIBIL TransUnion) can help a loan applicant to avail of personal loans at lower rates of interest.Type of EmploymentSalaried or self-employed.Minimum monthly income₹ 15,000 per monthWork ExperienceDepends on the type of loan applied for.Required DocumentsFor Salaried- ID proof – PAN Card- Address Proof – Aadhaar Card- Copy of a cheque for the salary bank account- Salary slips for the last 3 months- Bank statements for the last 6 months For Self-Employed- Income Tax returns- GST Returns- Proof of business ownership and continuity- Bank statements for the last 6 months- Audited financial statements for the last 2 years- Office address proof Read More: PooCoin Stock Forecast: Everything You Should Know StashFin – Top Customer Reviews The following are some of the top customers reviews that we have found from some of the famous review platforms on the internet. Hope these customer reviews can be helpful for you to get a better idea of the services and loan offerings of StashFin: Source Source Source Summing Up Hope this article was helpful for you to get an understanding of the offerings of StashFin. The company offers loans at reasonably good interest rates in return for their services and loan amounts. If you are a small-wage earner and in need of a loan, you can borrow loans easily from StashFin. We did not find many negative reviews on StashFin. However, it is also recommended to read the negative reviews by going to various review websites to find out what can go wrong. Always borrow loans when you are fully sure. Do you know of any better loan providers that offer loans at good interest rates? Share some of them with us in the comments section below. Read Also: What Is Stockinvest? Is It Legit And Working mPokket: Information, Eligibility Criteria, Interest Rates, Review & More Medplus Health IPO News, Allotments, And Updates You Should Be Aware Of
May 06, 2023
Which Describes A Type Of Tax That Funds City Programs? – Let’s Find Out
Which describes a type of tax that funds city programs? – The answer is local income tax or local tax. These taxes are mostly meant to fund local public services. These include education, maintenance, etc. These taxes also come in many forms for employees and businesses. Businesses need to perform tax planning accordingly to withhold the income tax of employees and also file the tax for business earnings as well. In this article, you will learn about the essential details of local income tax and how it works in the United States. Next up, you will also learn about the types of local taxes that are applicable. Furthermore, you will also learn about the types of state and local taxes one must pay. Hence, to learn more about the local tax, read on through to the end of the article. Which Describes A Type Of Tax That Funds City Programs? Local tax is the tax that funds city programs. According to Investopedia, “A local tax is an assessment by a state, county, or municipality to fund public services ranging from education to garbage collection and sewer maintenance. Local taxes come in many forms, from property taxes and payroll taxes to sales taxes and licensing fees. They can vary widely from one jurisdiction to the next. Taxes levied by cities and towns are also referred to as municipal taxes.” Most states impose income taxes on employees and businesses. In the case of employees, businesses withhold the taxes and file those taxes with the help of Forms W2 and W4. Local taxes also include those taxes that states and cities impose on goods and services. Apart from that, the property tax bill is also a type of local tax that homeowners pay to the local government. However, TaxFoundation.org states – “Cities, counties, school districts, and other localities that have instituted taxes on their residents’ incomes have done so either to reduce other taxes or to raise more revenue for local services. These may be laudable goals on paper, but local income taxes come with more undesired consequences than other local revenue sources, both for taxpayers and the governments that rely on these revenue streams.” How Does Local Tax Work In The United States? As per the Constitution of the United States, the federal government and the state governments have the authority and right to impose taxes on US residents. According to TaxPolicyCenter.org, “The individual income tax base in most states is similar to the federal tax base. Most states start with federal adjusted gross income, but a few start with federal taxable income. Alternatively, a handful of states use their own definition of income, but even these states rely heavily on federal rules when establishing their tax base. Even the states that start with the federal tax base, however, often apply different rules for certain types of income.” With the help of these taxes, local government fund government services. These services include police, health, fire services, education, maintenance of the locality, etc. Apart from that, with the help of these taxes, local governments also create projects that benefit various communities at large. Apart from that, there are also services that receive federal funds using grants. Local taxes include state, county, and municipal taxes. These taxes are not under federal taxes. When it comes to levying taxes, municipalities face a constant balancing act. They do not keep those taxes high. This is because high taxes face resistance from the public. However, low taxes mean that there are cutbacks in essential services. On a side note, if you want to learn more about tax refund tips, click on the given link. What Are The Types Of Local Taxes? Most of the states in the US impose taxes like personal income tax, estate tax, corporate income tax, fuel tax, and sales tax. The following are the common types of local taxes: Property Tax The property tax is the largest tax that most people (homeowners) receive. The value of the tax depends on the value of the home, which depends on a variety of factors. In each state, there is a guideline under which local governments of the state impose property taxes. Miscellaneous Taxes Local income taxes are imposed by states and cities. The government allows businesses and organizations to withhold those taxes from the wages of employees. Furthermore, there are local wage taxes that a total of sixteen states permit. School district tax is a local tax that you can find in Ohio and Pennsylvania. Sales taxes are for goods and services that residents of a state or municipality purchase. This is a type of regressive tax, as all customers pay the same percentage of tax regardless of their income. However, sales taxes are not applicable to states like Alaska, Montana, Delaware, Oregon, and New Hampshire. Other Government Funding Sources There are other ways through which governments fund capital projects in the community. One of the most common techniques they use is to issue bonds. Investors buy those municipal bonds. As a result, they are lending money to the government. The government, in return, is repaying the principal on a future date along with a set amount of interest. To pay its debt or to fulfill interest and repay the principal, the municipal government might issue a new tax or increase the percentage of the local tax. What Is The Importance Of Local Taxes? It is important to pay your tax bill, especially the local taxes. Municipalities and state governments use these taxes to pay the salaries in public services and to fund other costs of running society. They fund social programs, education, maintenance, local infrastructure, and more. Wrapping Up Which describes a type of tax that funds city programs? – The answer is local tax. Hope this article was helpful for you in getting a better understanding of what local tax is and how it works for governments. Do you have more information to add regarding local taxes? Share your information with us in the comments section below. Get More Financial Issue By Clicking Below!! Stakeholder Theory: What Is It, Working, Benefits, Challenges, And More What Is An Endowment? – Working, Purpose, Types, And More What Is a Bear Hug? Let’s Discuss The Benefits
Dec 08, 2023