Trial Balance: Definition, Working, Importance, And More

In a trial balance, the report of the ending balances of different ledgers of a particular company are available. It is the first statement you will need to prepare as an accountant to check the correctness of the double entry of any business accounts. To ensure that the accounts of a business are correct, having good knowledge of trial balance is necessary. Basically, with the help of trial balance you can minimize the errors in the company’s financial statements.
In this article, you will learn about wha trial balance is, and what are its constituents. Apart from that, you will also learn how a trial balance works in general. Next, we will show a step-by-step procedure of how to prepare a trial balance with respect to your company’s financial statements. Finally, you will learn some rules to follow while preparing a trial balance. Hence, to learn more, read on through to the end of the article.
What Is Trial Balance? – Definition
According to Investopedia,
“A trial balance is a bookkeeping worksheet in which the balances of all ledgers are compiled into debit and credit account column totals that are equal. A company prepares a trial balance periodically, usually at the end of every reporting period. The general purpose of producing a trial balance is to ensure that the entries in a company’s bookkeeping system are mathematically correct.”
The trial balance basically consists of the test of the fundamental aspect of a set of accounting records (that is debit and credit). Only after the trial balance process, you will be able to move to more complex and detailed analyses.
Read More: What Is An Angel Investor, And How Does Angel Investing Work?
How Does Trial Balance Work?
Basically, the trial balance is a tool that you, as an accountant, is using to check the accuracy of the general accountant ledger. Apart from that, it also helps you to ensure that the errors in the financial statement are minimal. The internal financial reports through the trial balance can help you to verify the double-entry accounting system’s accuracy. In addition to that, you can also identify eros before the issuing of the critical external financial statements.
The Wall Street Mojo adds here –
“Trial Balance is the report of accounting in which ending balances of the different general ledgers of the company are available; For example, utility expenses during a period include the payments of four different bills amounting to $ 1,000, $ 3,000, $ 2,500, and $ 1,500, so in the trial balance, single utility expenses account will be shown with the total of all expenses amounting $ 8,000.”
How To Prepare A Trial Balance?
In general, accountants create a trial balance manually. However, with the coming of various accounting software systems, accountants use them as well, when it comes to several transactions and investments. If you want to prepare a trial balance, make sure to take the following steps:
1. Make Sure to Balance The Ledger Accounts
Here, you will need to record all your transactions as journal entries, and make entries in respective ledger accounts. Then, calculate the closing balances of each ledger account. You will have to take these to the trial balance.
2. Prepare A Worksheet
Create three separate columns – one to contain the names of each ledger account, one for debit balances, and the last one for credit balances. You can also optionally enter account numbers and other details.
3. Complete The Worksheet
In the worksheet, fill the names of each account that you are loading in the worksheet. Apart from that, enter the total debits and credits for each ledger account for the accounting period. Make sure all the information is correct.
4. Add Values In The Columns
After you have filled up both the columns, you should add up the values in each column to find the total in each case. If the ledgers are correct, then the totals of both the columns should be equal.
5. Close The Trial Balance
If the values in both the credit and debit column are equal, you can close the trial balance. If they are not equal, consider finding the common errors, and rectify them.
Preparing A Trial Balance – A Few Things To Consider
According to Indeed.com,
“While computing the trial balance, you input the balances of these ledgers into debit or credit account lists in separate columns. It is necessary that the total amount in each column is equal. To ensure that bookkeeping entries are continuously correct and balanced, businesses typically perform trial balances at the end of each accounting period.”
Here are a few rules to consider if you are preparing a trial balance so as to avoid any errors:
- Make sure all the liabilities are in the credit column and all assets are in the debit column.
- Make sure the gains and revenues are on the credit side of the balance.
- The losses and expenses for the investment should go on the debit side of the balance.
- While preparing the trial balance, make sure to consider the nominal, personal, and real accounts.
- If a ledger shows zero balance, avoid it.
- Include the opening stock figure in the profit and loss account.
- You can show the sales and returns in two ways. The first way is to show them as reductions from the original purchase and sales ledger. The second way is to show them as separate line items in the trial balance.
- At the end of the trial balance, the debit and credit balance need to be identical.
Read More: What Is A Venture Capitalist, And What Are Their Functions?
Wrapping Up
Hope this article was helpful for you in getting an idea of what trial balance is, and how it works. It is basically a worksheet where you will get two columns – one for credit and the other for debit. By matching the balances of these two columns, you can ensure that your company’s bookkeeping is mathematically correct. The debits and credits are the company’s transactions.
All the debits and credits of the company over a given time must tally so as to ensure that there is no error in calculation. However, there could still be mistakes or errors in the accounting system. Do you have any suggestions for preparing a trial balance report? Share your ideas and info with us in the comments section below.
Read Also:
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
Are ISAs Still Worth It?
Yes, ISAs are still worth it, especially for higher-rate taxpayers or those with significant savings, as they offer a valuable way to protect your money from UK income tax, capital gains tax, and dividend tax. As the new year draws ever nearer, many households are using the allure of a fresh calendar to consider a fresh start for their finances. After what has been an undeniably difficult year for the vast majority of families across the country, it is only right that many are seeking to regain control of their financial situation in the new year. There are many ways in which this can be done, but almost all of them require some knowledge or learning about our country’s financial system, and the various boons that may or may not be available to us through certain schemes or financial products. The ISA is one such financial product – or rather, a family of such financial products –, and is commonly misunderstood or even overlooked by people seeking to re-address their household’s financial situation. ISAs have seen their praises sung many times over in newspapers and on TV, but are they still worth it? And how might they be? Whether an ISA is the best option depends on your specific financial situation and goals: Cash ISAs vs. Traditional Savings Accounts For many people, a standard, non-ISA savings account with a high interest rate is sufficient due to the Personal Savings Allowance (PSA), which lets you earn a certain amount of interest tax-free each year: Basic (20%) rate taxpayers: Can earn up to £1,000 in interest tax-free annually. Higher (40%) rate taxpayers: Can earn up to £500 in interest tax-free annually. Additional (45%) rate taxpayers: Get no PSA. ISAs are a good idea if: You are a higher or additional rate taxpayer, as your PSA is lower or non-existent. Your savings are large enough that the interest earned will exceed your PSA. You are concerned that future interest rate rises or an increase in your income could push you over your allowance in the future. You simply want the peace of mind that all interest earned is permanently tax-free, regardless of future changes to tax laws. Stocks and Shares ISAs For long-term goals (typically 5+ years), Stocks & Shares ISAs can be very valuable as they offer the potential for higher returns than cash over time and shield investment growth and dividend income from tax. Tax benefits: You are exempt from Capital Gains Tax (CGT) on profits when you sell investments and do not pay tax on dividend income. Risk: The value of investments can go down as well as up, so your capital is at risk, unlike in a cash ISA. Specialized ISAs 1. Lifetime ISAs (LISAs): Offer a 25% government bonus on savings up to £4,000 per year to help you buy your first home (up to £450,000) or save for retirement (accessible from age 60). A hefty penalty is charged for withdrawing money for any other reason. 2. Junior ISAs (JISAs): Allow you to save up to £9,000 per year tax-free for a child, which they can access at age 18. The Types of ISA First, it is important to understand that ISAs come in numerous different shapes and sizes, each of which can offer something unique to you as a saver. Knowing the difference between them, and knowing how best to utilize them, is key to getting the most out of them. The most common form of ISA used is the cash ISA, which essentially acts like a regular savings account. The core USP of the Cash ISA is that any interest earned within it is exempt from taxation. For many, this means little; there is a Personal Savings Allowance that enables you to ‘earn’ up to £1000 in interest annually tax-free. However, as you start to accrue more savings, and thanks to compound interest, this can soon wick away savings you could otherwise keep. There is also the Stocks and Shares ISA, which offers the same protection but instead from Capital Gains Tax, on stocks and shares traded within it. Here, the tax exemption makes more sense, as bigger stock market ‘wins’ can bring big influxes of capital gains. One of the most useful ISAs, though, is the Lifetime ISA, or LISA. LISAs are limited-access but provide a 25% bonus annually on up to £4000. The caveat is that the bonus can only be received if the money saved is spent on a first home, or on retirement. Protection from Failure All ISAs – at least, all that are offered legally – are FSCS (Financial Services Compensation Scheme)-compliant. This means that in the event of a banking institution going bust, the value of the money saved is protected up to £85,000. As such, ISAs are no less safe than any other savings account and offer more in return. Key Considerations In order to make the most of ISAs, you need to understand some of the central rules around using them. For one, there is a cap on how much you can store away in ISAs annually; at the time of writing, it is £20,000 per year. For another, you can only have one of each type of ISA, and each balance contributes to your personal ISA allowance. Shop around for the best interest rates or investment platforms, as rates vary between providers. Use your full annual allowance: The current total ISA allowance is £20,000 per tax year. Unused allowance doesn't roll over, so "use it or lose it". Transfer correctly: If moving money between ISAs, ask your new provider to handle the transfer to avoid losing the tax benefits. In summary, ISAs remain a core part of effective financial planning due to their robust tax advantages, particularly as your savings grow or your income increases over time. Read Also: Strategies For Maximising Value In Mergers And Acquisitions: A Comprehensive Guide Are Quick Loan Payoffs Possible? Let’s Explore! How To Start A Business In Houston
Dec 15, 2023
Capex Vs Opex: Essential Points Of Difference
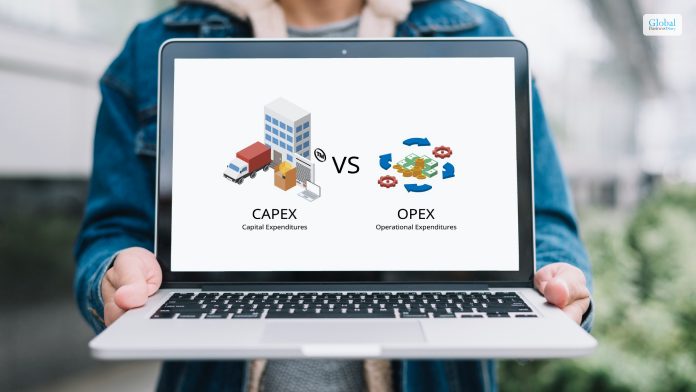
A company has to pay off different kinds of expenses to run its business smoothly. Capex vs Opex is one of the popular expense differentiation you must know. Among them, two kinds of expenditures are quite prominent in this regard. First is the Capex, and second is the operating expenses. Most of the time, these costs can be one, and sometimes they can take the shape of recurring expenses. You must follow the correct process that can assist you in getting things done in perfect order. Micromarketing techniques can work well here. The capital expenditure of a company will occur once, while the operating expenses will keep on occurring all the time. If you are a business owner, you must know the core points of differences between the two concepts. Essential Points Of Difference Between Capex vs Opex There are several points of difference between Capex vs Opex. It will offer you the complete insight once you go through the complete article. You need to know the reality while making the differentiation between the two concepts of business./ 1. Nature Of Expenses Capex vs Opex has some core differences in the nature of their expense model. Capital expenditures or Capex are investments in assets that provide long-term benefits to a company. These expenses are typically for acquiring, improving, or maintaining assets such as property, equipment, machinery, or infrastructure. Operating expenditures are day-to-day expenses incurred in running a business. These include costs for salaries, utilities, rent, marketing, repairs, and other ongoing operational expenses. You must consider these facts from your end while making the differences between the two concepts. 2. Duration Of Benefit Capital expenditures provide benefits over an extended period, usually beyond one fiscal year. They contribute to the company's future productivity, efficiency, or revenue generation. Capex vs Opex has some significant points of differences that you must know while you make the comparison. Operating expenditures are incurred for immediate use and provide short-term benefits. They are essential for maintaining regular business operations and generating immediate revenue. It will give short-term and regular benefits to your company. 3. Treatment In Financial Statements Capital expenditures are recorded as assets on the balance sheet and depreciated or amortized over their useful life. Depreciation or amortization expense is then reported on the income statement over time. Operating expenditures are immediately shown on the income statement in the period they are incurred. They directly impact the company's net income for that period. You need to identify the perfect solution that can make things easier for you to reach your goals with ease. 4. Tax Treatment Capital expenditures might be eligible for tax benefits such as depreciation or amortization deductions over time, reducing taxable income. Capex vs Opex, you must consider things at your end while reaching your objectives. Operating expenditures are fully deductible in the year they are incurred, providing immediate tax benefits. You should get through this difference to have a better idea of it. Ensure that the scope of errors is as low as possible. 5. Impact On Profitability & Cash Flow While CapEx affects profitability indirectly through depreciation expenses. It has a significant impact on cash flow at the time of purchase or investment. You cannot afford to make things work in the wrong direction from your counterpart. On the other hand, Operating expenditures directly affect profitability by reducing net income and also impact cash flow in the period they occur. Effective planning can boost the chances of reducing the expenses of your business. 6. Decision Making & Budgeting Capital expenditures involve strategic decisions as they impact the company's long-term growth and productivity. Budgeting for CapEx requires careful planning and consideration of future benefits. You should know the core points of differences between Capex vs Opex. It will assist you in attaining your goals with complete ease. Operating expenditures are part of routine budgeting and are necessary for maintaining day-to-day operations. They are generally more predictable and recurring. Without proper application of the strategies, things can turn worse for you. Examples Of Capex Expenditure There are several examples of Capex expenditure that you should know at your end. It will help you to get a better insight into it. Let’s find out some of the core examples of the Capex Expenditure that can make things easier for you. Machinery, manufacturing plants, and equipment. Computers. Building Improvements. Trucks and vehicles. The contribution margin of the company plays a vital role here. You should pay it from your end to meet all the expenditure. Examples Of Opex Expenditure There are several examples present for Opex expenditure that you must know at your end. Some of the core examples of it are as follows:- Salaries and wages. Rent and Utilities Legal and accounting fees. Overhead costs. Business travel. Property expenses. Interest on debt. Research and development expenses. You can easily make the market segmentation with the help of the differences between capex vs opex to meet the requirements. How To Reduce Capital Expenditure? There are several techniques you can employ to reduce the capital expenditure of your company to a great extent. You must follow the correct process in this regard to have a better idea of it. 1. Evaluate The Asset Needs Conduct a thorough assessment of current assets to determine if there are underutilized or redundant assets. Selling or repurposing such assets can free up capital and reduce the need for new investments. 2. Leasing Vs Buying Consider leasing equipment or assets instead of purchasing them outright. Leasing can lower initial costs and shift maintenance and upgrade responsibilities to the lessor. 3. Prioritize Essential Investment Focus on essential investments that directly contribute to core business operations or strategic growth. Prioritize projects that offer the highest return on investment (ROI) and align with long-term business goals. 4. Implement Of Efficient Technology Invest in technology that streamlines processes, reduces manual work, and improves efficiency without significant capital outlay. Cloud-based solutions or software-as-a-service (SaaS) models often have lower upfront costs. 5. Outsource Non-Core Functions Consider purchasing refurbished or used equipment instead of new. Often, these options come at a lower cost while still providing adequate performance and reliability. Final Take Away Hence, if you are making the differences between the two concepts of capex vs opex, then the mentioned points can prove to be useful for you. Try to reduce your expenses as much as possible. It will reduce your debts to a great extent. You can share your views and opinions in our comment box. It will help us to know your take on this matter. Once you follow the correct process, things are going to be easier for you. The application of the correct strategy can make things work for you. Continue Reading For More Business-Related News!! How To Buy An LLC? – Steps To Follow How To Become A Strategy Consultant? Roles & Responsibilities What Is A Sales And Purchase Agreement For Business? – Let’s Find Out
Nov 26, 2023

What Do the 2026 SALT, Senior Bonus, and Standard Deduction Changes Mean for Your Taxes?
In high-tax states, taxpayers have waited seven years for meaningful SALT relief. As of 2026, that wait ends now. This is due to the One Big Beautiful Bill Act. This act was signed into law in July 2025. It brings in the most significant overhaul to federal deductions in nearly a decade. Also, there are updated tax brackets, IRA limits, and 401(k) contribution caps. Basically, all these changes entirely reshape the outlook for 2026 wealth management. At the outset, homeowners, retirees, and middle-income earners stand to benefit. That part is clear enough. But it only works if the changes are understood properly and the positioning follows accordingly. Your State Tax Bill Finally Gets Federal Recognition Since 2018, homeowners in places like New York, California, and New Jersey have been dealing with the fallout. In fact, that was when the Tax Cuts and Jobs Act imposed the $10,000 SALT cap, which tightened things more than expected. That effectively penalized residents of high-tax states who previously deducted far more. Meanwhile, the new legislation quadruples that limit. The SALT deduction cap rises to $40,400 for 2026. Also, there are annual 1% increases through 2029. Consider a married couple in New Jersey. State income taxes are at $25,000, and property taxes are another $15,000. That totals $40,000, now fully deductible, which wasn’t the case earlier. Back then, the cap stopped everything at $10,000, cutting off the rest without much room to adjust. There’s a catch, though. High earners start losing the benefit. In 2026, the expanded cap phases down once income crosses $500,000. Around $600,000, it drops back to $10,000, almost like a reset. The provision isn’t permanent either. It sunsets in 2030 unless extended. All of this shifts the calculation. Itemizing starts to matter again, so revisiting earlier assumptions becomes necessary. A Fresh Tax Break Lands Exclusively for the 65-and-Over Crowd Retirees get the flashiest piece here. Maybe the most talked about, too. A new deduction shows up, $6,000 for those 65 and older. Married couples where both qualify can claim $12,000, which feels substantial at first glance, almost unusually generous. It doesn’t come alone. The deduction stacks, which is where things get interesting. Seniors already receive an extra standard deduction, $2,050 for single filers and $1,650 per qualifying spouse. Add the base deduction, and the numbers climb quickly. A single senior can shield $24,150. Joint filers, both over 65, can reach $47,500. The scale shifts quietly but significantly. Data from the White House Council of Economic Advisers suggests 88% of seniors receive Social Security benefits. That’s about 51.4 million people, a wide sweep, though outcomes will still vary. Of course, there are limits to this. In fact, the full deduction phases out above $75,000 for single filers. Meanwhile, for joint fillers, it is $150,000. Moreover, it disappears entirely at $175,000 and $250,000, respectively. Basically, that cutoff matters more than it first appears. One detail stands out. The deduction applies whether itemizing or not. That flexibility changes planning decisions. Seniors with medical expenses or charitable contributions still qualify, and the provision runs through 2028, leaving a narrow window to act. Small Gains Stack Up Over Time With inflation, the standard deduction goes upward for 2026. Although the shift isn’t dramatic, it is still there. Joint filers can claim $32,200, while singles get $16,100. Meanwhile, heads of household earn $24,150. These numbers might feel routine on paper, but they still matter. Individually, the increases seem minor. Easy to overlook, honestly. But they stack over time, slowly, almost quietly. Around 90% of taxpayers take the standard deduction, per IRS data. Over decades, these small adjustments start adding up, shaping outcomes more than expected. Why These Changes Demand a Longer View The first instinct is simple. Take the deduction, lock in the savings, move on. But that approach rarely holds up over time. Durable strategies need a slower, more deliberate kind of thinking. The interaction between provisions complicates things. A senior in a high-tax state now faces multiple pathways: the expanded SALT cap, the $6,000 bonus, and a higher standard deduction. The choice between itemizing and the standard deduction isn’t straightforward anymore. It carries more weight now. Nothing here is permanent. The SALT expansion sunsets in 2030. The senior bonus fades after 2028. Flexibility matters, maybe more than precision, especially with deadlines approaching. Q&A 1. Should I switch from the standard deduction to itemizing in 2026? It comes down to totals, really. Itemizable expenses, all of them together. SALT is now capped at $40,400, not the old $10,000, which changes the math quite a bit. Taxpayers in high-tax states need to recalculate.Itemizing starts to make more sense if the following factors exceed the standard deduction:1. State taxes2. Property taxes3. Mortgage interest4. Charitable contributions. 2. Can seniors who itemize still claim the new $6,000 deduction? Yes. This part stands out a bit. The senior bonus applies either way, itemizing or not. Retirees with high medical costs or charitable giving can claim both, which shifts the calculation slightly. 3. What happens when these provisions expire? When these provisions expire, the SALT cap reverts to $10,000 in 2030. The senior bonus ends after 2028. Building strategies that account for these sunsets makes more sense than assuming Congress will extend them. 4. How do these deductions interact with retirement planning? Timing matters more than it seems. Actually, deductions shift taxable income. This then nudges contribution limits and even Social Security thresholds. When planning connects across these areas, outcomes tend to improve. Read Also: What Is A Schedule 1 Tax Form? What Is Safe Harbor 401K? Benefits And Types Which Describes A Type Of Tax That Funds City Programs? – Let’s Find Out Seven Potential Tax Credits Available To Small Businesses Need Help with Tax Debt? Check Out These Relief Options
Mar 24, 2026
Pipeline In Finance: What Is It, Working, Importance, And More
A pipeline in finance is a series of discrete stages that describe progress toward a long-term goal. However, the definition of the term changes with different organizations, as they have their own variations on the term. Based on the company, it can be a sales pipeline, R&D pipeline, acquisition pipeline, etc. The term also applies to those companies that faced restructuring so as to avoid double taxation. In this article, you will learn about pipelines in finance and how it works for businesses. Here, you will also learn about how different types of businesses deal with their own pipelines. Apart from that, we will also discuss the meaning of the sales pipeline and the various stages of the sales pipeline in business. Hence, to learn more about pipelines, read on through to the end of the article. What Is Pipeline in Finance? Investopedia states – “In finance, the term pipeline is used to describe progress toward a long-term goal that involves a series of discrete stages. For example, private equity (PE) firms will use the term “acquisition pipeline” to refer to a series of companies they have flagged as potential acquisition targets. This pipeline would include several stages, such as industry research, lead generation, negotiations, due diligence, and closing.” The pipeline works as per the pipeline theory. The theory works with the idea that any investment firm or a company that passes all its returns to its clients must not pay taxes like regular companies. This theory is also known as conduit theory, and these types of companies are called conduits. For example, if a particular investment firm passes its income directly to its investors, then the investors pay taxes like individuals. Hence, if the government (or IRS) taxes the company again, then it would be taxing the same income twice. The pipeline theory states that those companies must not be considered for taxation. However, in other cases, regular companies face double taxation. They pay taxes in the case on the company’s income and also the income on distributions they pay to shareholders. Hence, this issue comes under considerable debate from time to time. Pipeline in Finance: How Does It Work? As already discussed, in most cases, the company’s pipeline in finance works as per the pipeline theory. According to Investopedia, “The pipeline theory sustains the idea that an investment firm that passes all returns on to clients should not be taxed like regular companies. Capital gains, interest, and dividends as returns are key concepts to understand the pipeline theory. The pipeline theory is also referred to as the conduit theory.” Companies that seek tax advantages as per the pipeline theory are also called pipeline companies. If the company passes all its returns to its shareholders, they must not come under taxation like regular companies. If a company adheres to this standard, they get an exemption from corporate income taxes. The premise they use is that they are effectively an investment pipeline. This is because the company passes its income directly to its investors. In other cases, experts use the pipeline as a metaphor for describing the progress of a company toward achieving its long-term goal. Hence, it describes the ongoing process of the company. Consider the acquisition pipeline of a private equity firm. In this case, the pipeline might not end because it is always facing new deals once the old ones face completion. What Is A Sales Pipeline? (A Popular Pipeline In Finance) According to HubSpot.com, “A sales pipeline is a representation of how a prospect moves through every stage of your sales process. A prospect moves through your sales pipeline by completing specific actions which are depicted visually in your CRM.” For every company, there sales processes are different. The processes also change with differences in products. Hence, every company needs a unique sales pipeline that reflects the buyer’s journey in the best way possible. The company makes each prospect move through the sales pipeline at different rates. They do it by considering the level of urgency, interest, and the amount of research behind a product or service. In some cases, certain prospects even skip stages in the pipeline. In cases like these, you will need to skip stages to deal with the prospect as well. Hence, with the help of a proper sales pipeline, you will also be able to determine what stage of the sales process your prospects are at. Furthermore, you will also be able to find out the number of sales you will be able to close within a given timeframe. Here, the sales pipeline allows representatives and managers to forecast revenue better. What Are The Stages Of Sales Pipeline? The following are the major stages of a sales pipeline: 1. Prospecting: With this process, the business lets potential customers discover the company and its products and services. The business uses ads, promotional activities, and public relations. 2. Lead Qualification: The company offers resources and information to the lead to move them downstream. If the prospect wants to learn more, the company offers more lead magnets. 3. Demonstration or Meeting: Later, the sales reps schedule a demo or meeting with the prospect of the product or the service. Here, the business evaluates whether there is a strong case for the business to close the sale or not. 4. Proposal: Here, the company makes its case about how it can address the needs and demands of the customers. 5. Commitment and Negotiation: Here, the company discusses the expanding or shrinking scope of work. In this case, the company adjusts prices to manage expectations. The goal is to come to an agreement at last. 6. Closing the Sale: Here, the salesperson closes the sale and makes way for order fulfillment. 7. Post-Purchase Interaction: This includes offering exceptional service even after the sale, like customer service or asking the customer for feedback and other services. Wrapping Up Hope this article was helpful for you in getting a better idea of how a pipeline in finance works. You can see that the term has different meanings in different cases, based on the situation of the business. Do you have more information to offer? Consider sharing them with us in the comments section below. For More Business Related Article Click Below!! NetReputation Reviews: Is It Good For Your Business? What Are Distribution Channels In The Context Of Business? What Is Wholesale Distribution? – Importance, Benefits, And Examples
Dec 30, 2023