Are Quick Loan Payoffs Possible? Let’s Explore!
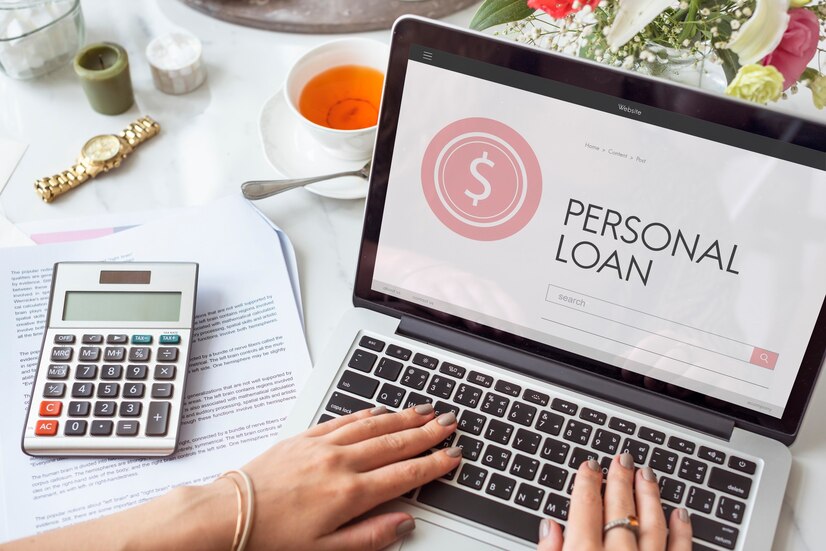
In the fast-paced world of personal finance, the quest to pay off loans quickly is a common pursuit. Whether you’re dealing with a personal loan, credit card debt, or considering options for early loan repayment, understanding the dynamics is crucial.
In this article, we’ll delve into the possibilities of quick loan payoffs and unravel the intricacies associated with this financial endeavor. Let’s explore various aspects, tips, and considerations to empower you in managing your loans effectively.
How Loan Terms Affect Your Credit Score?
Taking out a loan is a financial decision that often involves careful consideration of terms such as loan amount, interest rates, and repayment periods.
To embark on a journey towards quick loan payment, it’s essential to grasp the fundamentals of loan structures and devise effective repayment strategies.
The Impact Of Credit Scores On Loan Terms
Your credit score plays a pivotal role in determining the interest rates and terms of your loan. A good credit score can unlock favorable conditions, while a lower credit score may lead to higher interest rates.
Understanding this dynamic is crucial when strategizing how to pay off a personal loan early, or any other loan type, without incurring excessive costs.
Unveiling The World Of Personal Loans
Personal loans offer flexibility for various financial needs. Exploring the nuances of personal loans, including their average amounts and typical repayment periods, can guide you in making informed decisions about paying off the loan early. Here’s what reliable lenders have to say – https://www.my-quickloan.co.uk/how-to-pay-off-a-loan-faster/.
Pros And Cons Of Paying Off A Personal Loan Early
The Pros Of Paying Off Your Loan Early
Paying off a loan ahead of schedule has its advantages. Lowering the overall interest paid and gaining financial freedom sooner are among the perks. However, it’s essential to navigate potential pitfalls, such as prepayment penalties and the impact on credit scores.
The Cons And Considerations
While the benefits of early loan repayment are evident, it’s crucial to weigh the potential drawbacks. Some loans come with prepayment penalties, and understanding how this could affect your financial situation is vital. Moreover, delving into the impact on your credit score is crucial.
Strategies For Early Loan Payment
Utilizing Tools – Loan Calculators And Credit Monitoring
In the digital age, financial tools can be invaluable. Exploring loan calculators to understand the implications of different repayment scenarios and leveraging credit monitoring services, such as Experian’s free credit monitoring service, can provide insights into your credit health.
Consolidation As A Strategic Move
Debt consolidation loans can be a game-changer in the quest for paying off your loan early. Understanding how to consolidate high-interest debt and save on overall interest payments is a crucial strategy for managing financial obligations efficiently.
Establishing A Solid Repayment Plan
Crafting a repayment plan is the cornerstone of successful loan payoffs. Tailoring the plan to your financial circumstances, utilizing extra money for repayments, and staying consistent are vital components.
Lowering Interest Rates Strategically
Exploring opportunities to lower interest rates, either through negotiations with lenders or by refinancing, can significantly impact how you can pay off your loan.
My Quick Loan – A Provider Perspective
My Quick Loan distinguishes itself by offering loans ranging from £100 to £5,000 with flexible payback periods of 1 to 36 months. Connecting applicants with multiple FCA-approved lenders ensures that individuals find the best loan with a lower interest rate.
Understanding the representative interest rate of 79.5% APR (Variable) is key to making informed decisions. It’s crucial to evaluate how this rate aligns with your financial goals and explore ways to minimize interest payments.
FAQs On Repaying Loan Off Early
How Does Early Loan Repayment Affect My Credit Score?
Early loan repayment can impact your credit score. While it may positively affect your credit history, closing a credit account could impact your credit mix, which plays a role in your overall credit report.
Are There Prepayment Penalties For Paying Off A Loan Early?
Some loans have prepayment penalties, so it’s crucial to review your loan agreement. My Quick Loan strives to provide transparent terms, minimizing surprises for borrowers.
What Sets My Quick Loan Apart From Other Lenders?
My Quick Loan distinguishes itself by offering a wide range of loan amounts, flexible repayment periods, and connecting applicants with FCA-approved lenders, ensuring competitive interest rates.
Final Words On Paying Off Your Loan
In the quest to achieve quick loan payoffs, knowledge is power. Understanding the intricacies of loans, credit scores, and repayment strategies empowers individuals to make informed decisions.
While navigating the landscape of personal finance, My Quick Loan stands out as a provider committed to facilitating efficient and affordable financial solutions.
Read Also:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
What You Should Know Before Committing To A Cash Buyer
Cash buyers are becoming increasingly popular in the real estate market. They can make the process of buying or selling a home faster and easier than traditional buyers due to their ability to purchase properties with cash instead of having to go through the lengthy process of getting a loan approved. However, if you're considering working with a cash buyer, there are some things you should know before committing. Benefits of Working with a Cash Buyer Working with a cash buyer has many benefits. The most obvious benefit is that they can help you sell your house fast. They can often close deals more quickly than traditional buyers who may take weeks or months to get financing from a bank or other lender. Also, cash buyers typically have fewer contingencies as part of their offer, which can make it less likely for an agreement to fall through at the last minute due to issues with financing or appraisals. Finally, working with a cash buyer may help you avoid the hassle and expense of commissions, closing costs, and other fees associated with traditional sales. What You Need To Know Before Signing Before signing any agreement with a cash buyer, it's important that you do your research and understands what you're getting into. Here are some key considerations: Make sure that the cash buyer has enough financial resources available to purchase your property in full and on time. Ask for proof of funds such as bank statements or verification from an escrow company before entering into any agreement. Understand all terms and conditions included in the offer including any deadlines for completion or conditions that must be met prior to closing. Make sure these terms are clearly spelled out in writing so there is no ambiguity later on. Ask about the buyer’s track record in completing similar transactions in the past and inquire about references so you can check up on their credibility and reputation within the industry. Ask for an estimate of how long it will take for all paperwork required for closing to be completed, as this will help you plan accordingly for when funds will become available after the completion of the sale. Be aware of any potential tax consequences associated with selling your property quickly at discount prices—this could increase your overall liability so consult your accountant before signing anything! Consider consulting legal counsel if needed—an experienced attorney can ensure all legal documents associated with the sale are properly drafted and signed off on by both parties involved before money changes hands. Final Thoughts Cash buyers can be an excellent option if you need quick access to capital without going through the hassle of finding financing from banks or other lenders—just make sure that you understand all terms associated with the sale beforehand! Doing your research ahead of time by asking questions about their history and experience dealing in similar transactions will help ensure everything goes smoothly during the negotiation process as well as upon completion of the sale itself! Read Also: How Sustainability Sets Up Real Estate Developers For Success Profitable Business Ideas To Start In UAE What Is The Defeasance Clause?-Everything You Need To Know
Mar 09, 2023
Maximizing Your Home Loan Options: Finding The Best Fit For Your Financial Goals
The home loan process begins with a pre-approval, followed by house hunting. Once a home is chosen, an application is submitted to the lender. The lender then appraises the property, reviews the application, and, if approved, funds are released for purchase. Understanding the steps for a successful transaction is crucial in any business. Choose Loan Market Canberra to ensure efficiency, reduce the risk of errors, and promote trust between trading parties. It fosters smooth operations, and customer satisfaction, and ultimately, boosts profitability. Assessment Of Personal Finances Evaluation of the current financial status is essential in understanding one's economic stability. It involves assessing income, expenses, assets, and liabilities, followed by creating balanced budgets and financial goals for a secure future. Determining the affordability of a house involves analyzing your monthly income, expenses, and potential mortgage payments. Factors such as down payment, interest rates, and property taxes can significantly influence home affordability. Always plan wisely to avoid financial stress. Having a good credit score is crucial as it influences lenders' confidence in your ability to repay loans. It can dictate mortgage rates, insurance costs, and even employment opportunities. High credit scores potentially offer better loan terms, lower interest rates, and greater financial opportunities. Understanding Different Types Of Home Loans Conventional loans are a type of mortgage loan not insured by any government agency. These are typically offered by private lenders and banks, and often require stringent criteria such as good credit rating and a substantial down payment from borrowers. Government-insured loans are financial borrowings backed by a government agency. These loans, like FHA and VA loans, provide lenders with a safeguard against borrower default, thereby enabling lenders to offer favorable loan terms, such as lower interest rates or reduced down payments. Fixed-rate and adjustable-rate mortgages are two primary options for homebuyers. Fixed-rate holds a consistent interest rate throughout the life of the loan, ensuring predictable payments. Adjustable rates initially offer lower rates, but these can fluctuate over time, potentially increasing repayments. Preparing Important Documents To apply for a home loan, various documents are needed. These include proof of income, credit history, employment verification, tax returns for two years, bank statements, and identification proof. Each lender might require additional specific documents. Collecting all financial documents beforehand is crucial for accuracy and efficiency in financial management. It helps in proper bookkeeping, eases audit processes, prompts decision-making, and avoids legal issues. Moreover, it ensures transparency and accountability in financial dealings. The process of getting pre-approved for a loan involves assessing your creditworthiness and financial capabilities. It's significant because it provides a preliminary indication of how much you can borrow, thereby helping you set a realistic budget when buying a home or car. Making The Home Loan Application The home loan application process involves several stages. Initially, a borrower completes an application with a lender, providing financial and personal information. Next, the lender evaluates this information to determine the borrower's ability to repay the loan. Approval may include specific loan terms and conditions. Common mistakes to avoid during applications include submitting incomplete or inaccurate information, overlooking instructions, providing irrelevant details, not customizing the application for certain roles, late submission, and neglecting to proofread, which results in spelling and grammar errors. Home Appraisal And Inspection A home appraisal is a professional's unbiased evaluation of a home's market value. It's vital during a sale or refinancing process, as it helps in determining an accurate selling price or loan value, ensuring a fair transaction, and preventing overpayment. The necessity of a home inspection can't be overstated. It provides the potential homeowner with vital information about the property's current state, helping to identify any serious issues or needed repairs. This informs buying decisions and helps prevent future complications. During the inspection, if potential issues surface, ascertain their severity. Prioritize those requiring immediate attention. Seek professional advice if necessary and initiate corrective actions. Document findings proposed solutions, and track progress until resolution, ensuring efficient communication with relevant stakeholders. Financial Aspects Of Closing On The Home Closing costs are expenses over the property price that buyers and sellers incur to complete a real estate transaction. Understanding and signing closing documents is crucial during property transactions. These documents typically contain significant agreements, including mortgage terms, payment details, and property details. Carefully reviewing each clause before signing can prevent future disagreements or disputes. Once your home loan has been approved, the lender will send a formal approval letter outlining the loan amount, terms, and repayment schedule. You now need to complete further paperwork, like signing mortgage documents, before proceeding to the property settlement and finally moving in. Conclusion Obtaining a home loan involves several steps. First, assess your budget and determine how much you can afford. Then, research potential lenders, and compare interest rates and loan terms. Submit a loan application, and provide necessary documents. Lastly, finalize the loan upon approval. Informed decision-making is essential throughout any process to ensure successful outcomes. It entails gathering extensive, relevant information, and analyzing and interpreting it accurately. This not only reduces uncertainty and risks but also enhances productivity, efficiency, and overall success. Significant entry into homeownership can feel overwhelming but don't be daunted. Start your home loan journey today. Each step forward brings you closer to owning your dream home. Empower yourself with research and seek professional advice. Your perfect home awaits you. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Jan 05, 2024
8 Ways To Prepare For Your Retirement
As we all dream about the golden years of retirement, it's crucial to remember that careful planning is the key to a worry-free and enjoyable post-work life. Did you know that the average life expectancy has reached 72 years globally, according to the World Bank? This means people now have more time to cherish their retirement years, but it also highlights the need for a solid financial strategy to maintain a comfortable lifestyle. This article will explore nine essential steps to help you prepare for your retirement. From crafting a budget to fine-tuning your investment portfolio, these practical tips will enable you to embrace your golden years with confidence and tranquility. Assess Your Retirement Needs The first step towards successful retirement planning involves getting a clear picture of your financial needs. Start by estimating your future expenses, considering essential aspects such as housing, healthcare, and recreational pursuits. Online calculators can be invaluable tools for projecting the income necessary to sustain your preferred lifestyle and helping you pinpoint ideal retirement savings wealth management goals. By taking the time to assess your individual retirement needs, you can make informed decisions that will contribute to a secure and comfortable future, allowing you to truly enjoy your well-deserved golden years. Invest In Tax-Free Retirement Accounts Saving for retirement can sometimes feel overwhelming, but with the right approach, it's easier than you think. One smart strategy is to invest in tax-free retirement accounts, which can help you boost your savings. Options like Roth IRAs offer a fantastic opportunity for your investments to flourish tax-free, ultimately enhancing your long-term gains. By carefully selecting tax-advantaged financial instruments, you can keep a larger portion of your hard-earned wealth to relish during your retirement years. Remember, every dollar saved on taxes is a dollar that can help you enjoy the lifestyle you've always envisioned, so make the most of these tax-free opportunities. Diversify Your Investment Portfolio Building a diverse investment portfolio is essential in managing risk and enhancing returns during your journey toward retirement. By spreading your investments among different asset classes—such as stocks, bonds, and real estate—you can achieve a more balanced mix that safeguards your financial future. It's important to regularly evaluate and fine-tune your portfolio, ensuring that it aligns with your preferred level of diversification and risk tolerance. By taking a proactive approach toward managing your investments, you'll be better prepared to weather any financial storm. Pay Off High-Interest Debts Before you enter the realm of retirement, it's vital to tackle high-interest debts that can eat away at your income and limit your ability to save and invest. Prioritize clearing credit card balances, personal loans, and other high-interest liabilities as soon as possible. By doing so, you'll not only strengthen your financial standing but also alleviate the stress that often accompanies mounting debts. Developing a plan to systematically pay off these obligations can help you stay on track and remain motivated. Consider strategies such as the debt avalanche method, where you focus on the debt with the highest interest rate first, or the debt snowball method, where you target the smallest debt first to build momentum. As you head towards your well-earned retirement, being debt-free will allow you to fully enjoy your golden years without the burden of financial obligations looming over you. Plan For Healthcare Expenses As you look forward to your retirement years, it's essential to consider healthcare expenses, which can often become a considerable financial burden. Start by exploring Medicare coverage options and evaluating whether you might need supplemental insurance to bridge any coverage gaps. Remember, it's always better to be prepared than to face unforeseen medical costs without a safety net. To further safeguard your financial well-being, consider setting up a health savings account (HSA) that allows for tax-free withdrawals to cover qualified medical expenses. By planning ahead and allocating funds for healthcare, you can have the peace of mind that you'll be well-equipped to handle any health-related expenses during your retirement. Maximize Social Security Benefits Optimizing your social security benefits is a crucial aspect of retirement planning, as it can make a substantial difference in your overall income during your golden years. By delaying your benefits until you reach full retirement age or even later, you can secure higher monthly payments, providing you with a more stable financial foundation. When determining the best time to claim your benefits, take into account factors such as your health, life expectancy, and financial requirements. Weighing these considerations carefully will help you make an informed decision that aligns with your unique circumstances and long-term goals. Maintain An Emergency Fund Establishing an emergency fund is an invaluable way to ensure financial stability during your retirement years. Strive to accumulate a reserve equal to three to six months' worth of living expenses, stored in a liquid account that's easily accessible when needed. This safety net will enable you to address unforeseen expenses, such as home maintenance or medical bills, without tapping into your retirement savings. By building and maintaining this emergency fund, you'll have the peace of mind that comes with knowing you're prepared for life's unexpected twists and turns. This financial cushion can help you weather any financial storm and preserve your hard-earned retirement nest egg, allowing you to fully enjoy your golden years with confidence and serenity. Stay Informed And Adapt Remember, retirement planning is a dynamic process that demands continuous attention and fine-tuning. Staying informed about changes in tax regulations, new investment opportunities, and economic shifts is essential to maintaining a successful retirement strategy. Regularly reassess your plan, taking into account any relevant developments, and make the necessary adjustments to stay on course for a secure and rewarding retirement. By adopting a proactive approach and adapting to the ever-changing financial landscape, you'll be better equipped to handle any challenges that may arise. This ongoing vigilance will help you preserve your financial well-being and ensure that your retirement years are as enjoyable and fulfilling as you've always imagined. Conclusion Embracing these eight practical steps will pave the way for a financially secure and fulfilling retirement. As you embark on this exciting new chapter in your life, you can do so with confidence, knowing that you've taken the necessary precautions to safeguard your financial future. Remember, thorough preparation is key to enjoying your golden years with the peace of mind you deserve. Read Also: A Brief Guide To Business Integrated Planning Maximizing Tax Refunds: Tips And Tricks For Canadians Seven Potential Tax Credits Available To Small Businesses In 2023
Apr 27, 2023
Navigating Home Financing: A Deep Dive Into Non-Qm Mortgage Loans
In the realm of mortgage financing, Non-QM (Non-Qualified Mortgage) loans have emerged as a flexible and inclusive option for individuals who may not fit the traditional lending criteria. This comprehensive guide aims to shed light on the intricacies of Non-QM mortgage loans, exploring their definition, eligibility criteria, benefits, and considerations for those seeking alternative paths to homeownership. If you're curious about Non-QM loans and want to learn more, click here. Understanding Non-QM Mortgage Loans What Are Non-Qm Loans? Non-QM loans fall outside the guidelines set by government-sponsored entities like Fannie Mae and Freddie Mac. Unlike traditional Qualified Mortgages (QM), Non-QM loans provide a more inclusive approach to lending by considering a broader range of borrower profiles. Eligibility Criteria For Non-Qm Mortgage Loans 1. Credit Flexibility Non-QM loans are designed to accommodate borrowers with unique credit profiles. Individuals with a recent bankruptcy, foreclosure, or fluctuating income may find Non-QM loans more accessible. 2. Debt-To-Income Ratio Variation While conventional mortgages often adhere to strict debt-to-income ratios, non-QM loans allow for greater flexibility. Borrowers with higher debt-to-income ratios may still qualify based on other compensating factors. 3. Alternative Documentation Traditional mortgages often require extensive documentation to verify income and employment. Non-QM loans, however, may accept alternative forms of documentation, making them more suitable for self-employed individuals or those with non-traditional income sources. 4. Unique Property Types Non-QM loans can be more lenient when it comes to financing unique property types. This flexibility is beneficial for borrowers looking to invest in non-traditional homes or properties. Benefits Of Non-Qm Mortgage Loans 1. Accessibility For Non-Traditional Borrowers Non-QM loans provide an alternative for borrowers who don't meet the stringent criteria of conventional mortgages. This inclusivity extends to self-employed individuals, retirees, and those with unique financial circumstances. 2. Flexible Underwriting Criteria The flexibility of non-QM loans allows lenders to consider a broader range of factors beyond the traditional credit score and debt-to-income ratio, providing more opportunities for approval. 3. Unique Property Financing Borrowers interested in financing unique or non-traditional properties may find Non-QM loans more accommodating than traditional mortgages. 4. Credit Repair Opportunities For individuals with recent credit challenges, Non-QM loans can serve as a stepping stone to homeownership while providing an opportunity to rebuild credit over time. Considerations And Drawbacks 1. Higher Interest Rates Non-QM loans typically carry higher interest rates in contrast to conventional mortgages. It's crucial for potential borrowers to thoroughly assess the long-term financial implications. 2. Potential For Larger Down Payments Some Non-QM lenders may require larger down payments, impacting the initial financial commitment for borrowers. 3. Limited Regulatory Protections Non-QM loans are not subject to the same regulatory protections as Qualified Mortgages. Borrowers should carefully review loan terms and conditions. 4. Variable Loan Terms Non-QM loans may come with variable terms and conditions. Borrowers must understand and assess the specific terms offered by lenders. The Non-Qm Mortgage Loan Application Process 1. Pre-Application Consultation Prospective borrowers should engage in a pre-application consultation with a Non-QM lender. During this phase, the lender will assess the borrower's unique financial situation and discuss available loan options. 2. Documentation Submission Borrowers will be required to submit documentation to support their application. This may include alternative income documentation, proof of assets, and other relevant financial information. 3. Underwriting And Approval The lender will conduct a thorough underwriting process, considering the borrower's unique circumstances. Upon approval, the borrower will receive a loan offer with specific terms and conditions. 4. Property Appraisal As with any mortgage, a property appraisal may be required to determine its value and suitability for financing. 5. Closing And Homeownership Upon completing the necessary steps and meeting any remaining conditions, borrowers can proceed to the closing. This involves signing the required paperwork, officially making them homeowners. Conclusion Non-QM mortgage loans offer a valuable alternative for individuals who may not fit within the parameters of traditional lending. While they come with certain considerations and potential drawbacks, the inclusivity and flexibility of Non-QM loans make them a viable option for a diverse range of borrowers. As with any significant financial decision, thorough research, consultation with non-QM lenders, and a clear understanding of the terms are crucial. If you're intrigued by the possibilities of Non-QM mortgage loans and want to explore more, click here for additional information. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Dec 04, 2023