What Is The Leverage Ratio And How to Calculate It?

Leverage ratio is a tool for businesses that helps to determine the extent to which a particular business depends on debt to purchase assets and build capital. On the one hand, it helps businesses determine their own capability to secure funding. On the other hand, the leverage ratio helps investors and lenders evaluate the ability of a business to meet its financial obligations after securing capital.
In this article, you will learn about leverage ratio in general and how it works for businesses as well as investors and lenders alike. We will also share with you details on how to calculate the leverage ratio formula of different types of leverage ratios. Finally, you will learn about the importance of the leverage ratio and how it applies to businesses. Hence, to learn more, read on through to the end of the article.
What Is The Leverage Ratio?
According to Investopedia,
“A leverage ratio is any one of several financial measurements that look at how much capital comes in the form of debt (loans) or assesses the ability of a company to meet its financial obligations. The leverage ratio category is important because companies rely on a mixture of equity and debt to finance their operations, and knowing the amount of debt held by a company is useful in evaluating whether it can pay off its debts.”
Basically, the leverage ratio is a set of ratios with the help of which you can highlight the financial leverage of a business when it comes to assets, liabilities, and equities. The ratio gives you an idea of how much of the capital of a business comes from its debt. Hence, you will get a good idea of whether the business makes well for its financial obligations.
Read More: Network Marketing: What Is It? Is It The Right Option For You?
How Does Leverage Ratio Work?
According to Hubspot.com,
“A higher financial leverage ratio indicates that a company is using debt to finance its assets and operations — often a telltale sign of a business that could be a risky bet for potential investors. It can mean that earnings will be inconsistent, it could be a while before shareholders can see a meaningful return on their investment, or the business could soon be insolvent.”
These metrics are really useful for creditors and investors to find out whether they should extend credit to or invest in the business. If the financial leverage ratio of a company is very high, it means that the company is allocating most of its cash flow to pay off its debts and is more prone to default on loans.
On the other hand, if the financial leverage ratio of a business is low, it shows that the business is financially responsible and has a steady stream of revenue. Even if a company is in significant debt, having a good financial leverage ratio shows that there are minimal risks for investors and creditors, and the business is likely worth an investment.
Leverage Ratio – How To Calculate It?
The following are the different formulae of leverage ratios based on the type of ratio you want to choose:
1. Operating Leverage Ratio

You can calculate it using this formula:
| Operating Leverage Ratio = Percentage change in EBIT (earnings before interest and taxes) / Percentage change in Sales |
2. Net Leverage Ratio

Here is the formula to calculate this ratio:
| Net Leverage Ratio = (Net Debt – Cash Holdings) / EBITDA (Earnings before Interest, Taxes, Depreciation, and Amortization) |
3. Debt-to-EBITDAX
You can calculate EBITDAX using this formula:
| EBITDAX (Earnings before Interest, Taxes, Depreciation, and Amortization before Exploration Expenses) = EBIT (Earnings before Interest and Taxes) + Depreciation + Amortization + Exploration Expenses |
4. Debt-to-Equity Ratio
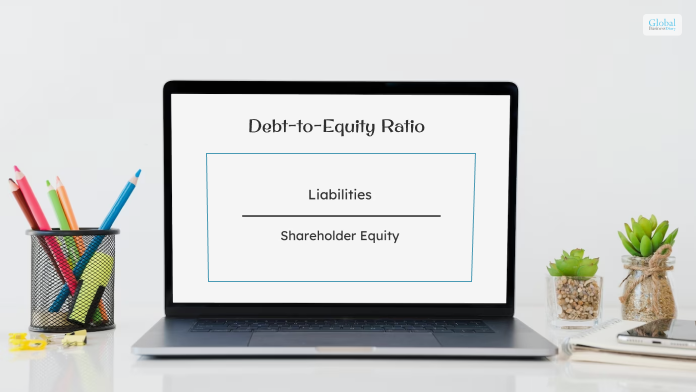
Here is the formula to calculate this ratio:
| Debt-to-Equity Ratio = Liabilities / Stockholders’ Equity |
5. Debt-to-Capital Ratio
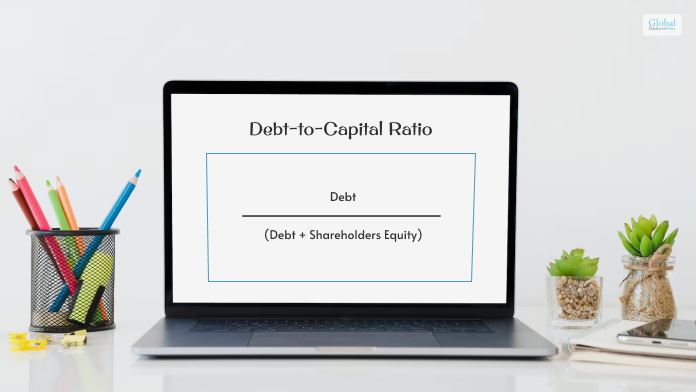
You can calculate it using this formula:
| Debt-to-Capital Ratio = Debt / (Debt + Shareholders Equity) |
6. Debt-to-Capitalization
Here is the formula to calculate this ratio:
| Debt-to-Capitalization Ratio = (Short-term Debt + Long-term Debt) / (Short-term Debt + Long-term Debt+ Shareholder Equity) |
7. Interest Coverage Ratio

You can calculate it using this formula:
| Interest Coverage Ratio = Operating Income / Interest Expenses |
8. Fixed-Charged Coverage Ratio
Here is the formula to calculate this ratio:
| Fixed-Charged Coverage Ratio = EBIT (Earnings before Interest and Taxes) / Interest Expense of Long-term Debt |
By having a good idea of your leverage ratios related to a business, you might understand how the business can run in the near future.
Why Is Leverage Ratio Important?
According to the Wall Street Mojo,
“Leverage ratios are important as they allow investors to assess a company’s financial position with respect to its financial obligations. Though firms have an option of using their equity to purchase assets and resources for undertaking different business activities, they go for taking up loans to finance their capital building. The reason is one – the cost of debt or cost of borrowing is way less than the cost of equity.”
The different types of leverage ratios help investors get a better idea of how the business’s capital flow is structured. By calculating these ratios, you can have information about a company in regard to whether it can take advantage of its leverage or not.
For example, if the company you want to invest in or lend credit to has taken too much debt, it is obviously risky for you. On the other hand, if the leverage ratio is too low and the company does not have any debt, it will be able to pay off too much cost of capital and reduce its earnings in the long run. Hence, consider your choices carefully.
Read More: Project Management: What Is It? – Major Types, Examples, And More
Wrapping Up
Hope this article was helpful for you in getting an understanding of how a leverage ratio works. You can see here that this is one of the major financial tools with the help of which you can assess a company’s ability to meet its financial obligations. By using it to measure operating expenses, you can get an idea of how differences in output can change operating income.
The debt-equity ratio, equity multiplier ratio, degree of financial leverage, and consumer leverage ratio are some of the common leverage ratios. Do you have any more information to add regarding how to calculate the leverage ratio? Share your ideas and opinions with us in the comment section below.
Read More:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
Navigating Home Financing: A Deep Dive Into Non-Qm Mortgage Loans
In the realm of mortgage financing, Non-QM (Non-Qualified Mortgage) loans have emerged as a flexible and inclusive option for individuals who may not fit the traditional lending criteria. This comprehensive guide aims to shed light on the intricacies of Non-QM mortgage loans, exploring their definition, eligibility criteria, benefits, and considerations for those seeking alternative paths to homeownership. If you're curious about Non-QM loans and want to learn more, click here. Understanding Non-QM Mortgage Loans What Are Non-Qm Loans? Non-QM loans fall outside the guidelines set by government-sponsored entities like Fannie Mae and Freddie Mac. Unlike traditional Qualified Mortgages (QM), Non-QM loans provide a more inclusive approach to lending by considering a broader range of borrower profiles. Eligibility Criteria For Non-Qm Mortgage Loans 1. Credit Flexibility Non-QM loans are designed to accommodate borrowers with unique credit profiles. Individuals with a recent bankruptcy, foreclosure, or fluctuating income may find Non-QM loans more accessible. 2. Debt-To-Income Ratio Variation While conventional mortgages often adhere to strict debt-to-income ratios, non-QM loans allow for greater flexibility. Borrowers with higher debt-to-income ratios may still qualify based on other compensating factors. 3. Alternative Documentation Traditional mortgages often require extensive documentation to verify income and employment. Non-QM loans, however, may accept alternative forms of documentation, making them more suitable for self-employed individuals or those with non-traditional income sources. 4. Unique Property Types Non-QM loans can be more lenient when it comes to financing unique property types. This flexibility is beneficial for borrowers looking to invest in non-traditional homes or properties. Benefits Of Non-Qm Mortgage Loans 1. Accessibility For Non-Traditional Borrowers Non-QM loans provide an alternative for borrowers who don't meet the stringent criteria of conventional mortgages. This inclusivity extends to self-employed individuals, retirees, and those with unique financial circumstances. 2. Flexible Underwriting Criteria The flexibility of non-QM loans allows lenders to consider a broader range of factors beyond the traditional credit score and debt-to-income ratio, providing more opportunities for approval. 3. Unique Property Financing Borrowers interested in financing unique or non-traditional properties may find Non-QM loans more accommodating than traditional mortgages. 4. Credit Repair Opportunities For individuals with recent credit challenges, Non-QM loans can serve as a stepping stone to homeownership while providing an opportunity to rebuild credit over time. Considerations And Drawbacks 1. Higher Interest Rates Non-QM loans typically carry higher interest rates in contrast to conventional mortgages. It's crucial for potential borrowers to thoroughly assess the long-term financial implications. 2. Potential For Larger Down Payments Some Non-QM lenders may require larger down payments, impacting the initial financial commitment for borrowers. 3. Limited Regulatory Protections Non-QM loans are not subject to the same regulatory protections as Qualified Mortgages. Borrowers should carefully review loan terms and conditions. 4. Variable Loan Terms Non-QM loans may come with variable terms and conditions. Borrowers must understand and assess the specific terms offered by lenders. The Non-Qm Mortgage Loan Application Process 1. Pre-Application Consultation Prospective borrowers should engage in a pre-application consultation with a Non-QM lender. During this phase, the lender will assess the borrower's unique financial situation and discuss available loan options. 2. Documentation Submission Borrowers will be required to submit documentation to support their application. This may include alternative income documentation, proof of assets, and other relevant financial information. 3. Underwriting And Approval The lender will conduct a thorough underwriting process, considering the borrower's unique circumstances. Upon approval, the borrower will receive a loan offer with specific terms and conditions. 4. Property Appraisal As with any mortgage, a property appraisal may be required to determine its value and suitability for financing. 5. Closing And Homeownership Upon completing the necessary steps and meeting any remaining conditions, borrowers can proceed to the closing. This involves signing the required paperwork, officially making them homeowners. Conclusion Non-QM mortgage loans offer a valuable alternative for individuals who may not fit within the parameters of traditional lending. While they come with certain considerations and potential drawbacks, the inclusivity and flexibility of Non-QM loans make them a viable option for a diverse range of borrowers. As with any significant financial decision, thorough research, consultation with non-QM lenders, and a clear understanding of the terms are crucial. If you're intrigued by the possibilities of Non-QM mortgage loans and want to explore more, click here for additional information. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Dec 04, 2023
Common Personal Loan Myths You Should Not Believe: A Complete Guide:
Personal loans are currently one of the most popular loans. You can use it for any purpose. You may be wondering why so many individuals prefer personal loans. Personal loans provide several advantages to borrowers. However, they are only sometimes the best solution for everyone. A personal loan has many benefits. It includes fast approval, easy qualifying requirements, speedy disbursement, and flexible payback terms. In all kinds of cash crunches, the loan can assist you. Despite the benefits, there are several myths that one should not believe. What Are The Pros Of A Personal Loan? Because interest rates are often much lower, a personal loan is usually cheaper. It is cheaper than using a credit card or receiving a payday loan. Also, payday loans must be repaid in full. Hence a personal loan is a more convenient alternative. Most personal loans are small and can be as much as $100,000. Have you considered applying for a personal installment loan but are still determining if it is wise? This article will help you with it. Moreover, if you want a personal loan, sorting payroll is essential. However, you can use a paystub generator for smooth working. A personal loan might be an excellent solution depending on your financial condition. It will assist you in making your payments. Continue reading to learn about the common myths about personal loans. Myths About Personal Loans: Read on to learn about seven common myths about personal loans. You will also be able to see the reality behind it. It will help you to apply for one. A low credit score results in loan denial: Many consumers believe they will not get their loans approved because of poor credit scores. An individual's credit score is not the only thing that banks consider. When determining loan eligibility, other variables take priority over a poor credit score. Besides an individual's credit score, financial organizations also consider other factors. It includes the borrower's income and ability for repayment. Personal loans have a lengthy processing: Borrowers avoid applying for a personal loan because they expect a longer processing time. They also believe that there is a need for more approval procedures. Personal loans are not secure. So they do not need collateral. You can issue them within 2-7 working days. You need to file the loan application with small documentation. Moreover, some lenders offer to provide same-day personal loans. Huge interest rates: The most widely held assumption about personal loans is their high-interest rates. In practice, these loans may be cheaper than other unsecured loans. Remember that having a fantastic credit score is the key to qualifying for low-interest rates. If you want a personal loan, shop with other lenders to check interest rates. Understanding what different lenders have to offer will help you get the best personal loans. It also helps individuals with bad credit to get a loan at the best interest rate. It does not have to be a stressful or time-consuming procedure. You may compare interest rates and personal loan lenders easily and quickly. It is hard to get approval: Another common myth about personal loans is that they are challenging to get. This is arguably the most common myth that is simple to believe and qualifies but is incorrect. Obtaining this form of loan nowadays is as simple. It is as simple as completing an online application and waiting for approval. Applying for a personal loan is simpler than obtaining a house or a vehicle loan. It begins with a simple online comparison of your loan possibilities with fixed and variable interest rates. The Only Lenders Are Banks: Before the internet age, banks were the sole providers of personal loans. There is a growing popularity and renown of internet lenders. Consumers today have several possibilities for obtaining a personal loan. Cooperating with an internet lender might provide you with several perks and advantages. Most significantly, the personal loan application procedure is simple and quick. You may receive an instant response to your application. You can use the loan only for personal reasons: It may be confusing to you since the term implies "personal." Many people believe that the loan is for personal purposes. Other lending organizations, unlike banks, are not concerned with how or where you use the money. They will not interfere with your plan to spend the money. You only must make monthly payments on schedule. You must show a serious commitment to return the loan amount. It is up to you how you intend to use it. You may also use it as extra funding for your business. Perhaps you need it for an emergency, such as repairing a broken automobile or home. There are so many ways where you can use a personal loan. Personal loans are available to salaried persons: It is generally believed that only people with a regular income stream are eligible to apply for personal loans. It is just another misconception about personal loan applications. When there is a consistent income stream, it is simpler for salaried workers to get their loan applications authorized. Those who are self-employed can also get personal loans. The individual's credit history determines the approval of the loan amount. But the amount approved may differ. NOTE: Many people find personal loans to be an attractive source of money. Unfortunately, most need to familiarize themselves with the many components of personal loans. There are various myths or misconceptions. You should not trust them. To take advantage of personal loans, you must first verify your beliefs. The list will help you determine what is true and what is not. Understanding these myths can help you on your loan journey. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Mar 17, 2023
Fixed Annuities: What They Are And How They Work
Fixed annuities offer a low-risk option for retirement planning. Individuals who want to receive regular payments throughout their retirement years can invest their money now, earn interest on these funds, and defer taxes until the annuity pays out. If you're looking for a safe and effective way to provide for your needs during your retirement years, a fixed annuity is worth considering. What Is a Fixed Annuity? A fixed annuity guarantees an ongoing stream of income at a fixed rate of return for a set period of time. Individuals can make a single lump sum payment into their annuity or they can contribute to the annuity through a series of scheduled payments. Fixed annuities are most commonly used to generate retirement income. After you've fully funded the annuity, you're guaranteed returns that have increased at the fixed rate over the life of the annuity. How Does a Fixed Annuity Work? Fixed annuities are a straightforward investment option that provides tax-deferred growth. They're not indexed to stock market performance, so they provide a steady rate of return. This protects you against potential market losses, but it may limit possible gains when the market is up. The rate of return does not account for inflation, so you'll need to consider projected inflation rates when evaluating your contributions and return. Every annuity has slightly different terms. The annuity may begin to pay out immediately or the payments can commence at a future date. Annuities with a lifetime payout option will deliver fixed payments until the investor passes away. Some will pay out through the lifetime of the investor's spouse, allowing both partners to draw on the income. A period of a certain annuity provides a set number of payments. The investor may outlive these payments. If they do not, the annuity's continuing payments can go to their estate or to a set beneficiary. Fixed vs Variable Rate Annuities Fixed annuities are low-risk products with a set rate of return, which protects you from the potential volatility of the stock market. These differ from variable rate annuities, which deliver returns based on the performance of the investments in the annuity's portfolio. A variable rate annuity has the potential to accelerate the growth of your holdings, but it comes with a higher rate of risk as well. A variable rate annuity is best used in conjunction with other lower-risk investments like an IRA. Understanding Accumulation and Payout Terms Annuities go through two phases. While you're paying money into the annuity, it's in its accumulation phase. When the annuity begins to deliver payments, it transitions into the payout phase, also known as the annuitization phase. It's important to understand the terms associated with both phases so you can handle your finances appropriately. The accumulation terms specify: The period of time over which contributions are made. The number of contributions the investor will make. How much each contribution will be. The rate of return on the investment. The payout terms will specify: The minimum age at which you can start receiving payments. The withdrawal penalty for taking payments early. How long the payments will continue. Whether another beneficiary can receive payments in the event of the original investor's death. Types of Fixed Annuities Fixed annuities can come in several different forms, each with slightly different terms. Traditional Fixed: A traditional fixed annuity, as discussed here, provides a fixed interest rate over a specific period of time. Fixed Index: A fixed index annuity bases some or all of the interest rate on the market index. Though the interest rate will never fall below zero, it can fluctuate. A fixed index annuity caps the maximum return at a percentage of the actual return rate on the index. Multi-Year Guaranteed Annuity (MYGA): An MYGA uses a fixed interest rate for a set period of time, which is typically between three and ten years. At this point, you can cash out the annuity or renew the contract under new terms. Who Can Benefit From a Fixed Annuity? A fixed annuity is a simple investment option that provides an effective way to fund your retirement. This type of investment is ideal for: Risk-averse investors who prioritize stability and security. Individuals looking for a more profitable alternative to a CD or savings account. Those who want to make a predictable retirement budget. Investors who want tax-deferred growth for their money. Whether you're setting up your first retirement fund or looking for a low-risk way to round out your retirement investments, a fixed annuity can provide an excellent option. Read Also: Financial Planning Tips For Different Stages Of Life 10 Best Investment Apps For 2021 – Globalbusinessdiary Business Deductions And Tax Planning: Two Critical Steps To Save Money
May 02, 2023

Trading Options Using Iron Condors
For options traders looking to find a reliable and consistent way to capitalize on the markets with low risk, Iron Condors are an ideal choice. This options trading strategy allows traders to collect rewards no matter which direction the market shifts; however, it can be challenging to get started if you don't have the experience or knowledge of what goes into making an iron condor successful. In this article, we'll look at how exactly iron condors work and provide tips and strategies from experienced options traders on maximizing your advantages when utilizing these options trades. What Are Iron Condors? An Iron Condor is a type of option spread trading strategy used in the stock market. It is suited to volatile markets, as it attempts to exploit fluctuations while still reducing risk. An Iron Condor can generate significant opportunities with limited downside when executed well. The way it works is that the trader buys and sells two different calls or puts of the same underlying asset, creating both a bull and bear spread at once. By simultaneously entering into four separate trades – two puts and two calls – risk is minimized by limiting the maximum loss. All traders should be aware that there are still risks associated with this strategy, as any adverse shift in the underlying price will cause losses that can quickly escalate. However, Iron Condors offer many advantages over more traditional options strategies when used correctly. If you want to learn more about it, Saxo broker Saudi Arabia offers more details. What Are The Advantages Of Trading Iron Condors? When trading Iron Condors, the trader can take advantage of the volatility in the market. Unlike traditional options strategies, where a single option can be advantageous or not depending on whether it expires in or out of the money, an Iron Condor gives traders two different ways to do well. It means that even if one option expires out of the money, as long as the other option does well, it will still be successful overall. It allows traders to enter trades with significantly less risk than they typically have when trading options alone. Another advantage is that Iron Condors allow traders to benefit from both large and small moves in price without taking on excessive risk. Iron Condors are ideal for traders who are not looking to take on large amounts of risk but still want the potential for significant returns. Read Also: ACTC Stock – Present Price, Forecast, Statistics – Should You Invest In It In 2022? What Are The Risks Involved With Iron Condors? Although Iron Condors can provide traders with a low-risk way to trade, it is essential to remember that there are still risks associated with this strategy. Because the Iron Condor involves buying and selling options of the same underlying asset at different strike prices, any adverse movement in the underlying asset price will cause losses. Because of this, traders need to be aware of the potential for losses and should ensure that they are placing appropriate stop-loss orders to limit their losses if the market moves against them. Additionally, Iron Condors also involve complex strategies, so traders must have an understanding of how options work before attempting these trades, as well as have access to reliable sources of information about current market conditions. How To Set Up An Iron Condor Trade? When setting up an Iron Condor, the trader must decide which options they wish to use. It means researching underlying assets and finding ones that meet their volatility and potential return criteria. Once these have been identified, the trader must place four separate trades – two puts and two calls of the same underlying asset at different strike prices. It is important to note that when trading Iron Condors, you should always ensure that the strike prices are within a range where both options will likely expire in the money. For example, if you are trading a put option with a strike price of $50, your call option should also have a strike price within this range, as out-of-the-money options are likely to expire with no value. Once the trades have been placed, managing the Iron Condor will largely depend on the current market conditions and how they affect your options. If one of your options is at risk of expiring out of the money, then it may be necessary to make adjustments by closing out some or all of the trades and re-entering them at different strike prices. Strategies For Success When Trading Iron Condors As with any trading, success when trading Iron Condors will depend mainly on having a sound strategy. It means understanding how the underlying asset you are trading behaves and assessing the potential risks and rewards before entering the trades. It is also important to remember that Iron Condors involve four separate options contracts, so it is crucial to monitor them carefully, as each can affect your overall earnings or loss. Additionally, traders should always use appropriate stop losses to limit their risk exposure and avoid significant losses if market conditions move against them. #Disclaimer: The information provided on this blog is for educational and informational purposes only and should not be construed as financial advice. I am not a licensed financial advisor. Any investment decision you make is at your own risk, and you should consult with a qualified financial advisor before making any investment decisions. This site may contain affiliate links, and I may earn a commission at no additional cost to you. Read Also: BNKU Stock: MicroSectors US Big Banks Index 3X Leveraged ETNs TUI Share Price Forcast: Everything You Should Know PooCoin Stock Forecast: Everything You Should Know
Mar 01, 2023