Capex Vs Opex: Essential Points Of Difference
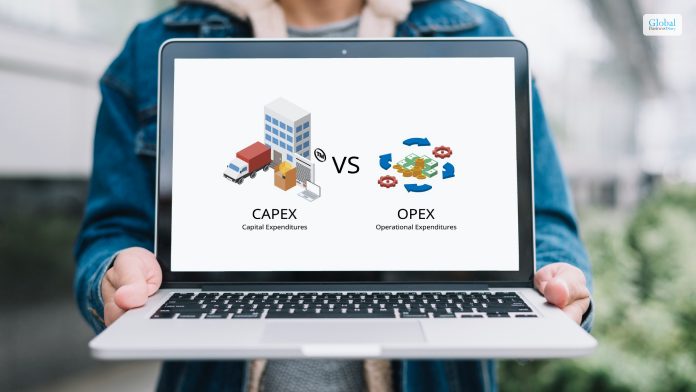
A company has to pay off different kinds of expenses to run its business smoothly. Capex vs Opex is one of the popular expense differentiation you must know. Among them, two kinds of expenditures are quite prominent in this regard. First is the Capex, and second is the operating expenses.
Most of the time, these costs can be one, and sometimes they can take the shape of recurring expenses. You must follow the correct process that can assist you in getting things done in perfect order. Micromarketing techniques can work well here.
The capital expenditure of a company will occur once, while the operating expenses will keep on occurring all the time. If you are a business owner, you must know the core points of differences between the two concepts.
Essential Points Of Difference Between Capex vs Opex
There are several points of difference between Capex vs Opex. It will offer you the complete insight once you go through the complete article. You need to know the reality while making the differentiation between the two concepts of business./
1. Nature Of Expenses
Capex vs Opex has some core differences in the nature of their expense model. Capital expenditures or Capex are investments in assets that provide long-term benefits to a company. These expenses are typically for acquiring, improving, or maintaining assets such as property, equipment, machinery, or infrastructure.
Operating expenditures are day-to-day expenses incurred in running a business. These include costs for salaries, utilities, rent, marketing, repairs, and other ongoing operational expenses. You must consider these facts from your end while making the differences between the two concepts.
2. Duration Of Benefit
Capital expenditures provide benefits over an extended period, usually beyond one fiscal year. They contribute to the company’s future productivity, efficiency, or revenue generation. Capex vs Opex has some significant points of differences that you must know while you make the comparison.
Operating expenditures are incurred for immediate use and provide short-term benefits. They are essential for maintaining regular business operations and generating immediate revenue. It will give short-term and regular benefits to your company.
3. Treatment In Financial Statements
Capital expenditures are recorded as assets on the balance sheet and depreciated or amortized over their useful life. Depreciation or amortization expense is then reported on the income statement over time.
Operating expenditures are immediately shown on the income statement in the period they are incurred. They directly impact the company’s net income for that period. You need to identify the perfect solution that can make things easier for you to reach your goals with ease.
4. Tax Treatment
Capital expenditures might be eligible for tax benefits such as depreciation or amortization deductions over time, reducing taxable income. Capex vs Opex, you must consider things at your end while reaching your objectives.
Operating expenditures are fully deductible in the year they are incurred, providing immediate tax benefits. You should get through this difference to have a better idea of it. Ensure that the scope of errors is as low as possible.
5. Impact On Profitability & Cash Flow
While CapEx affects profitability indirectly through depreciation expenses. It has a significant impact on cash flow at the time of purchase or investment. You cannot afford to make things work in the wrong direction from your counterpart.
On the other hand, Operating expenditures directly affect profitability by reducing net income and also impact cash flow in the period they occur. Effective planning can boost the chances of reducing the expenses of your business.
6. Decision Making & Budgeting
Capital expenditures involve strategic decisions as they impact the company’s long-term growth and productivity. Budgeting for CapEx requires careful planning and consideration of future benefits. You should know the core points of differences between Capex vs Opex. It will assist you in attaining your goals with complete ease.
Operating expenditures are part of routine budgeting and are necessary for maintaining day-to-day operations. They are generally more predictable and recurring. Without proper application of the strategies, things can turn worse for you.
Examples Of Capex Expenditure
There are several examples of Capex expenditure that you should know at your end. It will help you to get a better insight into it. Let’s find out some of the core examples of the Capex Expenditure that can make things easier for you.
- Machinery, manufacturing plants, and equipment.
- Computers.
- Building Improvements.
- Trucks and vehicles.
The contribution margin of the company plays a vital role here. You should pay it from your end to meet all the expenditure.
Examples Of Opex Expenditure
There are several examples present for Opex expenditure that you must know at your end. Some of the core examples of it are as follows:-
- Salaries and wages.
- Rent and Utilities
- Legal and accounting fees.
- Overhead costs.
- Business travel.
- Property expenses.
- Interest on debt.
- Research and development expenses.
You can easily make the market segmentation with the help of the differences between capex vs opex to meet the requirements.
How To Reduce Capital Expenditure?
There are several techniques you can employ to reduce the capital expenditure of your company to a great extent. You must follow the correct process in this regard to have a better idea of it.
1. Evaluate The Asset Needs
Conduct a thorough assessment of current assets to determine if there are underutilized or redundant assets. Selling or repurposing such assets can free up capital and reduce the need for new investments.
2. Leasing Vs Buying
Consider leasing equipment or assets instead of purchasing them outright. Leasing can lower initial costs and shift maintenance and upgrade responsibilities to the lessor.
3. Prioritize Essential Investment
Focus on essential investments that directly contribute to core business operations or strategic growth. Prioritize projects that offer the highest return on investment (ROI) and align with long-term business goals.
4. Implement Of Efficient Technology
Invest in technology that streamlines processes, reduces manual work, and improves efficiency without significant capital outlay. Cloud-based solutions or software-as-a-service (SaaS) models often have lower upfront costs.
5. Outsource Non-Core Functions
Consider purchasing refurbished or used equipment instead of new. Often, these options come at a lower cost while still providing adequate performance and reliability.
Final Take Away
Hence, if you are making the differences between the two concepts of capex vs opex, then the mentioned points can prove to be useful for you. Try to reduce your expenses as much as possible. It will reduce your debts to a great extent.
You can share your views and opinions in our comment box. It will help us to know your take on this matter. Once you follow the correct process, things are going to be easier for you. The application of the correct strategy can make things work for you.
Continue Reading For More Business-Related News!!
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
Navigating Home Financing: A Deep Dive Into Non-Qm Mortgage Loans
In the realm of mortgage financing, Non-QM (Non-Qualified Mortgage) loans have emerged as a flexible and inclusive option for individuals who may not fit the traditional lending criteria. This comprehensive guide aims to shed light on the intricacies of Non-QM mortgage loans, exploring their definition, eligibility criteria, benefits, and considerations for those seeking alternative paths to homeownership. If you're curious about Non-QM loans and want to learn more, click here. Understanding Non-QM Mortgage Loans What Are Non-Qm Loans? Non-QM loans fall outside the guidelines set by government-sponsored entities like Fannie Mae and Freddie Mac. Unlike traditional Qualified Mortgages (QM), Non-QM loans provide a more inclusive approach to lending by considering a broader range of borrower profiles. Eligibility Criteria For Non-Qm Mortgage Loans 1. Credit Flexibility Non-QM loans are designed to accommodate borrowers with unique credit profiles. Individuals with a recent bankruptcy, foreclosure, or fluctuating income may find Non-QM loans more accessible. 2. Debt-To-Income Ratio Variation While conventional mortgages often adhere to strict debt-to-income ratios, non-QM loans allow for greater flexibility. Borrowers with higher debt-to-income ratios may still qualify based on other compensating factors. 3. Alternative Documentation Traditional mortgages often require extensive documentation to verify income and employment. Non-QM loans, however, may accept alternative forms of documentation, making them more suitable for self-employed individuals or those with non-traditional income sources. 4. Unique Property Types Non-QM loans can be more lenient when it comes to financing unique property types. This flexibility is beneficial for borrowers looking to invest in non-traditional homes or properties. Benefits Of Non-Qm Mortgage Loans 1. Accessibility For Non-Traditional Borrowers Non-QM loans provide an alternative for borrowers who don't meet the stringent criteria of conventional mortgages. This inclusivity extends to self-employed individuals, retirees, and those with unique financial circumstances. 2. Flexible Underwriting Criteria The flexibility of non-QM loans allows lenders to consider a broader range of factors beyond the traditional credit score and debt-to-income ratio, providing more opportunities for approval. 3. Unique Property Financing Borrowers interested in financing unique or non-traditional properties may find Non-QM loans more accommodating than traditional mortgages. 4. Credit Repair Opportunities For individuals with recent credit challenges, Non-QM loans can serve as a stepping stone to homeownership while providing an opportunity to rebuild credit over time. Considerations And Drawbacks 1. Higher Interest Rates Non-QM loans typically carry higher interest rates in contrast to conventional mortgages. It's crucial for potential borrowers to thoroughly assess the long-term financial implications. 2. Potential For Larger Down Payments Some Non-QM lenders may require larger down payments, impacting the initial financial commitment for borrowers. 3. Limited Regulatory Protections Non-QM loans are not subject to the same regulatory protections as Qualified Mortgages. Borrowers should carefully review loan terms and conditions. 4. Variable Loan Terms Non-QM loans may come with variable terms and conditions. Borrowers must understand and assess the specific terms offered by lenders. The Non-Qm Mortgage Loan Application Process 1. Pre-Application Consultation Prospective borrowers should engage in a pre-application consultation with a Non-QM lender. During this phase, the lender will assess the borrower's unique financial situation and discuss available loan options. 2. Documentation Submission Borrowers will be required to submit documentation to support their application. This may include alternative income documentation, proof of assets, and other relevant financial information. 3. Underwriting And Approval The lender will conduct a thorough underwriting process, considering the borrower's unique circumstances. Upon approval, the borrower will receive a loan offer with specific terms and conditions. 4. Property Appraisal As with any mortgage, a property appraisal may be required to determine its value and suitability for financing. 5. Closing And Homeownership Upon completing the necessary steps and meeting any remaining conditions, borrowers can proceed to the closing. This involves signing the required paperwork, officially making them homeowners. Conclusion Non-QM mortgage loans offer a valuable alternative for individuals who may not fit within the parameters of traditional lending. While they come with certain considerations and potential drawbacks, the inclusivity and flexibility of Non-QM loans make them a viable option for a diverse range of borrowers. As with any significant financial decision, thorough research, consultation with non-QM lenders, and a clear understanding of the terms are crucial. If you're intrigued by the possibilities of Non-QM mortgage loans and want to explore more, click here for additional information. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Dec 04, 2023

What Is The Leverage Ratio And How to Calculate It?
Leverage ratio is a tool for businesses that helps to determine the extent to which a particular business depends on debt to purchase assets and build capital. On the one hand, it helps businesses determine their own capability to secure funding. On the other hand, the leverage ratio helps investors and lenders evaluate the ability of a business to meet its financial obligations after securing capital. In this article, you will learn about leverage ratio in general and how it works for businesses as well as investors and lenders alike. We will also share with you details on how to calculate the leverage ratio formula of different types of leverage ratios. Finally, you will learn about the importance of the leverage ratio and how it applies to businesses. Hence, to learn more, read on through to the end of the article. What Is The Leverage Ratio? According to Investopedia, “A leverage ratio is any one of several financial measurements that look at how much capital comes in the form of debt (loans) or assesses the ability of a company to meet its financial obligations. The leverage ratio category is important because companies rely on a mixture of equity and debt to finance their operations, and knowing the amount of debt held by a company is useful in evaluating whether it can pay off its debts.” Basically, the leverage ratio is a set of ratios with the help of which you can highlight the financial leverage of a business when it comes to assets, liabilities, and equities. The ratio gives you an idea of how much of the capital of a business comes from its debt. Hence, you will get a good idea of whether the business makes well for its financial obligations. Read More: Network Marketing: What Is It? Is It The Right Option For You? How Does Leverage Ratio Work? According to Hubspot.com, “A higher financial leverage ratio indicates that a company is using debt to finance its assets and operations — often a telltale sign of a business that could be a risky bet for potential investors. It can mean that earnings will be inconsistent, it could be a while before shareholders can see a meaningful return on their investment, or the business could soon be insolvent.” These metrics are really useful for creditors and investors to find out whether they should extend credit to or invest in the business. If the financial leverage ratio of a company is very high, it means that the company is allocating most of its cash flow to pay off its debts and is more prone to default on loans. On the other hand, if the financial leverage ratio of a business is low, it shows that the business is financially responsible and has a steady stream of revenue. Even if a company is in significant debt, having a good financial leverage ratio shows that there are minimal risks for investors and creditors, and the business is likely worth an investment. Leverage Ratio - How To Calculate It? The following are the different formulae of leverage ratios based on the type of ratio you want to choose: 1. Operating Leverage Ratio You can calculate it using this formula: Operating Leverage Ratio = Percentage change in EBIT (earnings before interest and taxes) / Percentage change in Sales 2. Net Leverage Ratio Here is the formula to calculate this ratio: Net Leverage Ratio = (Net Debt - Cash Holdings) / EBITDA (Earnings before Interest, Taxes, Depreciation, and Amortization) 3. Debt-to-EBITDAX You can calculate EBITDAX using this formula: EBITDAX (Earnings before Interest, Taxes, Depreciation, and Amortization before Exploration Expenses) = EBIT (Earnings before Interest and Taxes) + Depreciation + Amortization + Exploration Expenses 4. Debt-to-Equity Ratio Here is the formula to calculate this ratio: Debt-to-Equity Ratio = Liabilities / Stockholders' Equity 5. Debt-to-Capital Ratio You can calculate it using this formula: Debt-to-Capital Ratio = Debt / (Debt + Shareholders Equity) 6. Debt-to-Capitalization Here is the formula to calculate this ratio: Debt-to-Capitalization Ratio = (Short-term Debt + Long-term Debt) / (Short-term Debt + Long-term Debt+ Shareholder Equity) 7. Interest Coverage Ratio You can calculate it using this formula: Interest Coverage Ratio = Operating Income / Interest Expenses 8. Fixed-Charged Coverage Ratio Here is the formula to calculate this ratio: Fixed-Charged Coverage Ratio = EBIT (Earnings before Interest and Taxes) / Interest Expense of Long-term Debt By having a good idea of your leverage ratios related to a business, you might understand how the business can run in the near future. Why Is Leverage Ratio Important? According to the Wall Street Mojo, “Leverage ratios are important as they allow investors to assess a company’s financial position with respect to its financial obligations. Though firms have an option of using their equity to purchase assets and resources for undertaking different business activities, they go for taking up loans to finance their capital building. The reason is one – the cost of debt or cost of borrowing is way less than the cost of equity.” The different types of leverage ratios help investors get a better idea of how the business’s capital flow is structured. By calculating these ratios, you can have information about a company in regard to whether it can take advantage of its leverage or not. For example, if the company you want to invest in or lend credit to has taken too much debt, it is obviously risky for you. On the other hand, if the leverage ratio is too low and the company does not have any debt, it will be able to pay off too much cost of capital and reduce its earnings in the long run. Hence, consider your choices carefully. Read More: Project Management: What Is It? – Major Types, Examples, And More Wrapping Up Hope this article was helpful for you in getting an understanding of how a leverage ratio works. You can see here that this is one of the major financial tools with the help of which you can assess a company’s ability to meet its financial obligations. By using it to measure operating expenses, you can get an idea of how differences in output can change operating income. The debt-equity ratio, equity multiplier ratio, degree of financial leverage, and consumer leverage ratio are some of the common leverage ratios. Do you have any more information to add regarding how to calculate the leverage ratio? Share your ideas and opinions with us in the comment section below. Read More: What Are The Most Important Leadership Behaviors To Have? Contribution Margin: What Is It, Overview, Examples, And More Market Cannibalization – Definition, How Does It Work, Example, And More
Sep 29, 2023
Are Quick Loan Payoffs Possible? Let’s Explore!
In the fast-paced world of personal finance, the quest to pay off loans quickly is a common pursuit. Whether you're dealing with a personal loan, credit card debt, or considering options for early loan repayment, understanding the dynamics is crucial. In this article, we'll delve into the possibilities of quick loan payoffs and unravel the intricacies associated with this financial endeavor. Let's explore various aspects, tips, and considerations to empower you in managing your loans effectively. How Loan Terms Affect Your Credit Score? Taking out a loan is a financial decision that often involves careful consideration of terms such as loan amount, interest rates, and repayment periods. To embark on a journey towards quick loan payment, it's essential to grasp the fundamentals of loan structures and devise effective repayment strategies. The Impact Of Credit Scores On Loan Terms Your credit score plays a pivotal role in determining the interest rates and terms of your loan. A good credit score can unlock favorable conditions, while a lower credit score may lead to higher interest rates. Understanding this dynamic is crucial when strategizing how to pay off a personal loan early, or any other loan type, without incurring excessive costs. Unveiling The World Of Personal Loans Personal loans offer flexibility for various financial needs. Exploring the nuances of personal loans, including their average amounts and typical repayment periods, can guide you in making informed decisions about paying off the loan early. Here’s what reliable lenders have to say - https://www.my-quickloan.co.uk/how-to-pay-off-a-loan-faster/. Pros And Cons Of Paying Off A Personal Loan Early The Pros Of Paying Off Your Loan Early Paying off a loan ahead of schedule has its advantages. Lowering the overall interest paid and gaining financial freedom sooner are among the perks. However, it's essential to navigate potential pitfalls, such as prepayment penalties and the impact on credit scores. The Cons And Considerations While the benefits of early loan repayment are evident, it's crucial to weigh the potential drawbacks. Some loans come with prepayment penalties, and understanding how this could affect your financial situation is vital. Moreover, delving into the impact on your credit score is crucial. Strategies For Early Loan Payment Utilizing Tools - Loan Calculators And Credit Monitoring In the digital age, financial tools can be invaluable. Exploring loan calculators to understand the implications of different repayment scenarios and leveraging credit monitoring services, such as Experian's free credit monitoring service, can provide insights into your credit health. Consolidation As A Strategic Move Debt consolidation loans can be a game-changer in the quest for paying off your loan early. Understanding how to consolidate high-interest debt and save on overall interest payments is a crucial strategy for managing financial obligations efficiently. Establishing A Solid Repayment Plan Crafting a repayment plan is the cornerstone of successful loan payoffs. Tailoring the plan to your financial circumstances, utilizing extra money for repayments, and staying consistent are vital components. Lowering Interest Rates Strategically Exploring opportunities to lower interest rates, either through negotiations with lenders or by refinancing, can significantly impact how you can pay off your loan. My Quick Loan - A Provider Perspective My Quick Loan distinguishes itself by offering loans ranging from £100 to £5,000 with flexible payback periods of 1 to 36 months. Connecting applicants with multiple FCA-approved lenders ensures that individuals find the best loan with a lower interest rate. Understanding the representative interest rate of 79.5% APR (Variable) is key to making informed decisions. It's crucial to evaluate how this rate aligns with your financial goals and explore ways to minimize interest payments. FAQs On Repaying Loan Off Early How Does Early Loan Repayment Affect My Credit Score? Early loan repayment can impact your credit score. While it may positively affect your credit history, closing a credit account could impact your credit mix, which plays a role in your overall credit report. Are There Prepayment Penalties For Paying Off A Loan Early? Some loans have prepayment penalties, so it's crucial to review your loan agreement. My Quick Loan strives to provide transparent terms, minimizing surprises for borrowers. What Sets My Quick Loan Apart From Other Lenders? My Quick Loan distinguishes itself by offering a wide range of loan amounts, flexible repayment periods, and connecting applicants with FCA-approved lenders, ensuring competitive interest rates. Final Words On Paying Off Your Loan In the quest to achieve quick loan payoffs, knowledge is power. Understanding the intricacies of loans, credit scores, and repayment strategies empowers individuals to make informed decisions. While navigating the landscape of personal finance, My Quick Loan stands out as a provider committed to facilitating efficient and affordable financial solutions. Read Also: What Is Stockinvest? Is It Legit And Working MPokket: Information, Eligibility Criteria, Interest Rates, Review & More Medplus Health IPO News, Allotments, And Updates You Should Be Aware Of
Dec 07, 2023

What Is Net Operating Income? How To Calculate NOI?
Net operating Income is a valuation method. If you are a real estate professional, then you have to calculate it. It will help you in the determination of the income-producing properties For the calculation of NOI, Operating expenses need to be deducted from income a property generates. Most of the time, people often get confused between the concepts of Net Income and Net operating income. Net Operating Income will help you to know the capacity of the property to generate revenue. What Is Net Operating Income? Net operating Income helps you to calculate the profitability of an asset. It can be an income from an investment as well. After subtracting the operating expenses from Income, you will get net operating income. Most of the time, this parameter is used in the real estate industry. In order to determine the profitability of investment properties such as apartment complexes, warehouses, and buildings, this Net Operating Income is used. You can get the similar information in Investopedia. What Is The Net Operating Income Formula? You have to follow the simple Net Operating Formula to calculate the Net Operating Income. Let’s go through it once. Most of the time, for making an accurate valuation of commercial real estate, the Net Operating Income Formula is taken into consideration. You cannot ignore this fact from your end. Net Income Formula For Managerial Accounting The Net income formula for managerial accounting involves the following calculation methods:- Net Income = Total Revenue -Total Expenses Net Operating Income vs Net Income Net Operating IncomeNet IncomeNOI is a metric typically used in the context of real estate and investment propertiesNet Income, also known as Profit or Earnings, is a fundamental financial metric used in the context of businesses, not just limited to real estate.It represents the income generated from the property's operations before accounting for taxes, interest, depreciation, and amortization (known as EBITDA). It represents the profit a company makes after deducting all expenses, including operating expenses, interest, taxes, depreciation, and amortization (known as EBITDA). The formula for calculating NOI is: NOI = Total Revenue - Operating ExpensesThe formula for calculating Net Income is: Net Income = Total Revenue - Total ExpensesOperating expenses include items like property management fees, maintenance costs, property taxes, insurance, and other day-to-day operational expenses.Total expenses include operating expenses, interest payments on debt, income tax, and depreciation or amortization. Are Operating Income & Operating Revenue Same? Operating revenue is not the same as operating income. Operating revenue signifies the total cash inflow from your primary income-generating activity. After subtracting the cost of doing the business, the leftover income is the operating income. It is the primary form of difference between the two concepts. Operating income calculation is completed from the gross income depreciation, and amortization from the gross profit is deducted. Operating expenses are the expenses that involve administrative costs, rent, and supplies. If you want to calculate the gross profit, you need to calculate the Cost Of Goods Sold from the revenue. It is almost similar to the calculation of marginal cost. Benefits Of Calculating Net Operating Income There are numerous benefits to calculating the net operating income for your business. Now, you may be wondering what can be the benefits of calculating the Net Operating Income. Let’s dig deep into the details to have better insights into it. Its process of calculation is almost similar to that of the current ratio formula. 1. Profitability Assessment NOI offers you clear insight into operating profitability. When you subtract the property’s operating expenses from the gross rental income, you will get a clear idea of how much money the property is generating before the calculation of the taxes and financing. 2. Comparative Analysis Investors can use NOI to compare the financial performance of different properties. This comparison allows them to identify which properties are more profitable and make informed investment decisions. Investors need to identify the financial performance of the property before buying it. Net Operating Income can leverage the value of your property. 3. Valuation It is one of the primary components in determining the value of the property. You can estimate the value of the property after dividing it by its capitalization rate. It will be easier for you to make an accurate estimation of the market value of the property. Try to make things easier from your end. 4. Financial Planning Property owners can use NOI to create budgets, assess ongoing financial performance, and plan for the future. Understanding the NOI helps in making decisions related to rent increases, cost management, and property improvements. It is one of the basic purposes of making the calculation of NOI. It can benefit you on a pro-rata basis as well. 5. Financing Lenders often use NOI to assess the financial viability of a property and determine the amount of financing they are willing to provide. A higher NOI can lead to more favorable financing terms. You need to make the financial planning in the perfect order while attaining your requirements. 6. Income Tax Planning NOI can have implications for income tax planning. Property owners need to understand the taxable income generated by their property. It can be different from the NOI due to factors such as depreciation. In accounting terms, Depreciation reduces the value of the assets to a considerable extent. You need to get through these facts before the NOI calculation. 7. Risk Management When closely monitoring NOI, property owners can identify changes in the financial performance of a property. This allows them to address issues promptly, such as rising expenses or declining rental income, to mitigate financial risks. You need to identify the areas where Non-Operating Income can be of great help to you. 8. Investors Confidence The confidence of the investors depends largely on the operating income. Most of the time, we miss out on this fact at the time of selling the property to its investors. When investors and stakeholders have access to accurate NOI figures, it builds confidence in the property's performance. It can attract potential investors or partners. Final Take Away Hence, if you do not calculate the operating income, then you cannot get the correct insight into the accurate estimation of the property. You must not make your selection on the wrong end. Proper application of the NOI calculation can make things easier for your valuation. You can share your views and comments in our comment box. It will help us to know your take on this matter. You cannot make any kind of compromises in this regard while you calculate real estate property. Read More: Marketing Campaigns: How To Do It? – Steps To Follow Market Orientation – What Is It, And How Does It Work? Market Cannibalization – Definition, How Does It Work, Example, And More
Oct 04, 2023