Disaster Recovery Vs Business Continuity – What Are The Differences?
Disaster recovery vs business continuity: Which one is important? – The short answer is “Both.” It depends on the situation you are dealing with.
Most companies operate by assuming that their workplaces will maintain their consistent state with changing times. Hence, they try to find comfort in daily routines and rhythm of work. However, there are certain events when a business might face disruption.
Hence, businesses need to have a disaster recovery plan and a business continuity plan in place to ensure that the business recovers faster when it comes across a negative situation.
In this article, you will learn about disaster recovery and business continuity in general. However, the focus of the article will be on the differences between the two. Apart from those differences, we will also discuss the major similarities between them as well. In addition to this, we will, in brief, share with you how each of these works and how to implement them. Hence, to learn more, read on through to the end of the article.
Disaster Recovery Vs Business Continuity – What Are They?
If you want to prepare for disruptions in business, you will need to create various strategies and plans, following which you will be able to ensure that the core business functions are intact. This can help the business to come back faster from the uncertain negative consequences it just faced.
What Is Disaster Recovery?
Amazon Web Services defines disaster recovery as such –
“Disaster recovery is the process by which an organization anticipates and addresses technology-related disasters. The process of preparing for and recovering from any event that prevents a workload or system from fulfilling its business objectives in its primary deployed location, such as power outages, natural events, or security issues.”
To measure the targets of disaster recovery, two factors are taken – Recovery Point Objectives (RPO) and Recovery Time Objectives (RTO). The failures for which companies make disaster recovery plans are mostly larger-scale disaster events. The plan includes various procedures and policies for the company so that it can recover quickly from the disaster by following them.
What Is Business Continuity?
According to the Business Continuity Institute,
“Business continuity is about having a plan to deal with difficult situations so your organization can continue to function with as little disruption as possible. Whether it’s a business, public sector organization, or charity, you need to know how you can keep going under any circumstances.”
You will need a business continuity plan, too, in case of a disaster situation. However, the continuity plan is to deal with the disaster situation so that the organization is able to continue its functioning with little to no disruption.
However, you will need to understand here that a business continuity plan does not work at times of a large program or a disaster, which affects the company a lot. It also does not work when a large number of people are associated with a single plan. Hence, many big companies make business continuity plans for each of their departments. This makes each department implement the plan as per its needs.
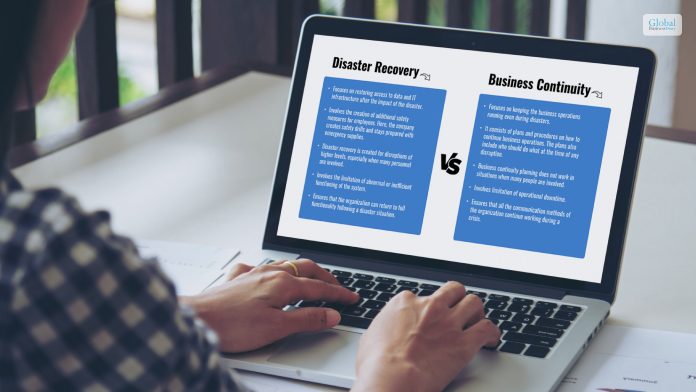
Disaster Recovery Vs Business Continuity – Major Differences
| Disaster Recovery | Business Continuity |
|---|---|
| Focuses on restoring access to data and IT infrastructure after the impact of the disaster.Involves the creation of additional safety measures for employees. Here, the company creates safety drills and stays prepared with emergency supplies.Disaster recovery is created for disruptions of higher levels, especially when many personnel are involved.Involves the limitation of abnormal or inefficient functioning of the system.Ensures that the organization can return to full functionality following a disaster situation. | Focuses on keeping the business operations running even during disasters.It consists of plans and procedures on how to continue business operations. The plans also include who should do what at the time of any disruption.Business continuity planning does not work in situations when many people are involved.Involves limitation of operational downtime.Ensures that all the communication methods of the organization continue working during a crisis. |
You can see from this table that both disaster recovery and business continuity are complementary to each other. Businesses need to combine both plans to ensure they are prepared for disastrous events.
Disaster Recovery Vs Business Continuity – Major Similarities
The following are some of the major similarities that you will find between disaster recovery and business continuity:
- Both are proactive strategies that enable a business to stay prepared for uncertain and disastrous events.
- Both plans allow the company to minimize the effects of the disaster before it actually occurs and affects the business.
- Both work quite well in situations of natural and man-made disasters. However, the result of their implementation depends on the situation.
- Professionals need to review both plans on a regular basis, and some of them need revision with the evolving situation of the organization.
How Do Disaster Recovery And Business Continuity Work?
According to the University of Central Florida,
“Having business continuity and disaster recovery plans in place can help companies minimize the consequences of a catastrophic event. They can also provide peace of mind; employees and business owners alike may feel more comfortable in a work setting where there are clear policies for how to respond to disasters.”
To implement these plans for the recovery of the business, the organization needs to create/hire crisis management professionals. These professionals will be responsible for developing and implementing such plans. Apart from that, they are also responsible for evaluating and revising them as per needs and training the employees of the organization to stay prepared.
Final Thought
Disaster recovery vs business continuity: Hope this article was helpful for you in getting a better idea of both of these terms and how they operate in the organizational setting.
Disaster recovery works in situations when the disruption is big and many people are involved. On the other hand, business continuity planning is to ensure business operations are continued in disruptions.
Do you have any more recommendations regarding when and how to implement a business continuity plan and a disaster recovery plan? Share your thoughts and ideas with us in the comments section below.
Read More:
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
How To Start A Concession Stand Business? – A Complete Guide
Do you want to commence your Concession stand business? Are you ready with your business plan and its prospect? If not, you have to understand the basics of this business to grow your business in the correct direction. You have to work on your plans well before establishing your business. One of the beneficial aspects of the Concession business is that it requires lower startup costs. Now, If you want to increase your profitability in the food service industry, then the application of the concession stand can work well in your friend. The Concession stands location will determine the ongoing success of your business. You have to chalk out a full-proof strategy to increase your profitability. How Much Does A Concession Stand Cost? Its cost depends on two factors:- Do you want to buy a used cart or, You want to build it from scratch. A new medium-sized concession stand will cost you around $11000 -$21000. On the other hand, if you want to use or purchase a well-equipped concession stand, it will cost you around $6000-$45,000. How Can You Start Your Concession Stand Business? You can follow specific lucid and straightforward steps to start your concession stand business with ease. Write your business plan first before standing your foodservice business. Keep the business plan as simple as possible. 1. Develop A Concession Stand Concept Your Concession stand concept and the menu will help you determine what type of cart you require to get the ideal location for your business. A concession stand can help you get pre-made snacks and creative gourmet cuisine for your business. You must have arrangements in your concession stand to sell the fresh cuisines, and the gourmet stuffs to your buyers. Try to keep your food items in proper condition. 2. Write A Concession Stand Business Plan Once you get a general idea about what kind of business you want to operate, now it’s time to figure out your business plan. For your concession stand, your business plan will act like a blueprint upon which the growth trajectory of your business will depend. It will help you make the right kind of investments without wasting too much money and time. A solid business plan for your concession stand will help you to gain most of the crowdfunding and other investors as they can gain a clear insight into your business growth in the upcoming days of your business. Also Read: How To Create A Powerful Business Models For Your Business 3. Arrange Funding For Your Concession Stand With a proper business plan in place, you will get the right idea of how much money you require for your business. If you want to launch a small concession stand business, your funding is enough to finance it. On the other hand, you will require money from outside sources if you want to start an extensive concession stand. Some of the best sources for the concession stand funding are as follows:- Investors:- You can pitch your business plan to your investors to arrange money. Crowdfunding: It allows a large group of people to make investments in your business if it sounds profitable and worth investing. Loans: You can collect the funds or the loans from the banks or from other sources that make loans available for investments. 4. Make A Purchase Of Your Concession Stand You can purchase your concession stand after having your business plan and funding in place. Now you need to decide whether you want a trailer, short-range, and stationary stand for your business. It will affect several factors, such as what kind of stand you purchase, the type of location you want, and the laws applied to this place. A place where there is lots of rush of people like a sports stadium or movie theatre can help you get more customers for your business. 5. Get The Essential Permits & Licenses Like any other business, you also need permission and licenses for running your concession stand business successfully. Here I will mention some of the standard licenses and permits you require to start your business. Some of them are as follows:- Food manager certification. Certificate for food handling. License for Food Vendor. Employer identification number. Sales & Use tax permit. These are some of the standard permits and licenses you will require for starting your concession stand business. Depending on your jurisdiction of the place, the law may change or alter. You can take a note of that thing for your own good. You can also incorporate your business with an LLC and you would require a registered agent in your state. For instance, if you are in Texas, you will require a registered agent in Texas for all kinds of legal correspondence. 6. Select The Food Storage & Preparation Equipment Depending upon the menu and the type of food you will serve to your target audience, you have to select the types of equipment which will suit you better. Some food items require the perfect temperature and pressure to keep the food quality intact. Some of the standard equipment’s which are primarily required for the business are as follows:- Warming & foid holding equipment. Sausage and Hot dig equipment. Ventless Fryers. Griddles. Popcorn machines. Cotton candy Machines. These are some of the types of equipment you may require for your concession stand business. Also Read: Top 7 Best Startups Revenue Model That Will Grow Your Business 7. Prepare A Concession Stand Equipment List To make your foodservice business run smoothly, you have to prepare the concession stand equipment list. There are certain everyday disposable you will require in the daily affairs of your business like cups, bowls, trays. Fryer baskets, cutlery, and many more. Some standard equipment which all types of concession stand require are as follows:- Cash registers. Coin Dispensers. Aprons. Snacks & Drinks. Signs. Cooking equipment. Serving equipment. Final Take Away Hence, if you want to run your Concession stand business properly, you have to make the required arrangements mentioned in this article. Then, you can feel free to share your views and opinions about the important deals for commencing a concession business. It is quite natural that we may have missed some of the crucial points essential to running these types of business smoothly. You can share your comments with us to provide you with better information on this business later. More Resources: Top 5 Types Of Business That Are Giving More Profits To The Sellers How To Start A Business In 2022 – Best Business Strategies? Top 7 Best Business To Start In Less Budget In 2022
Jan 24, 2022
How To Start An Insurance Company? – Steps You Must Take
How to start a life insurance company? - There is no short answer to this question. It is not a small task to start an insurance company. However, having the right focus and the right steps can help you to turn your new business into a victorious one in a short span of time. To learn more, read on through to the end of the article. The best steps to take on how to create an insurance company would be the ones that are tried and tested by many. Realistically speaking, the risks associated with the insurance sector are so high that a small mistake can cost you a fortune. Hence, you need to take careful steps. Despite that, there are some places you will need to be unique as well. But, to get started, the best option for you would be to stick to the basics. How To Start An Insurance Company? - Major Steps One of the first things that you can do to start an insurance company is to find out an idea of what will make your company different from the top companies in the market. Once you have chosen the insurance industry, you will need to do a quick search of the existing companies. According to Business News Daily, “Learn what current brand leaders are doing and figure out how you can do it better. If you think your business can deliver something other companies don’t (or deliver the same thing, only faster and cheaper), you’ve got a solid idea and are ready to create a business plan.” To start with “how to start my own insurance company,” you will need to ensure that your business does not face any legal problems or any other external problems. Hence, you need to make sure that your business is safeguarded as long as external issues are concerned. For that to happen, you need to follow some basic rules. The following are the major steps you must take to start your own insurance company in 2023: 1. Planning To The Core According to The Hartford, “When you create a business plan, you’re describing every aspect of your business in a formal document. This lets other people understand what you do, what your objectives are and what strategies you have in place to achieve your goals.” Furthermore, this document will also be your proof that you are dedicated to the business. This is beneficial for staying clear in front of insurance companies, shareholders, and staff members. However, with time, you will also need to update your business plan with necessary changes as per the demand of the market. Read More: The Types Of Business Insurance Needed For Every Business 2. Decide What Will Be Your Business Structure According to SBA.gov, “The legal structure you choose for your business will impact your business registration requirements, how much you pay in taxes, and your personal liability.” Here are the major types of business structures: Sole Proprietorship Corporation Limited Liability Company (LLC) Partnership S Corporation This depends on your personal responsibility and the setup of your business, as well as the setup of your business. Hence, you will need to choose the business structure that is right in your case. The structure depends upon your personal liability level. 3. Register Your Organization’s Title Registering is important. As per the recommendations of TheHartford.com, “Your business needs to be official. Aside from giving your startup more credibility with potential customers and clients, registering can also help protect your business’ name.” If your business is structured as a sole proprietor, your personal name is automatically the legal name of the company. However, you can give another name in the “doing business as” section. You will need to select and register a suitable name for your business. 4. Get Your TIN (Tax Identification Number) As per IRS regulations, every corporation and partnership needs to use FEIN (Federal Employer Identification Number) while it is filing taxes. This number is also important in the case of opening a bank account or a credit account for your business. However, if your business is structured as a sole proprietor, you will need to use your social security number (SSN). You will get the number after you register your business with the local government and IRS. 5. Ensure That Your Business Is State Registered Once you have received your Tax ID, you will have to connect with the State Insurance Commissioner’s desk. Businesses typically register as “resident business entities” when it comes to purposes related to state and local taxes. Once you register, your state will charge a registration fee from you. They will also give you a checklist, where they will ask you to ensure that you are aware of the state requirements and comply with them. 6. Get The Necessary Local Authorizations And Licenses Getting authorized at the local level and getting all the necessary licenses and permits is crucial to operating your business. Although you are a licensed insurance agent now, you will still need a general business permit at the local level or even a license if you want legal safeguards. However, according to Insureon.com, “The licensing, insurance, and bonding requirements for insurance agents vary by state. Having the right insurance and bonding can help keep you financially protected, and may be required for some jobs within the insurance industry.” 7. Get Insurance To Save Your Company’s Capital Depending on the structure and assets of your business, you will need to purchase insurance. There are a variety of business insurance you can check out to find which one is the right need for the moment. You can also consult with your lawyer, as well as your insurance guide, to find out which insurance is perfect for you now. Read More: Maximizing Home Insurance Coverage For Your At-Home Business With Riders Final Thoughts Hope you have found your answer on how to start an insurance company. Before starting your business and competing in the market, you will need to make sure that your business has all the legal safeguards. This is the most important aspect, as it will help your business in the long run. Share your thoughts about the business safeguards and other ideas in the comments section below. Read Also: What Is Commercial Insurance? And Its Different Types – Let’s Discuss Guaranteed Issue Life Insurance: Is it Worth It? 11 Tips For Saving On Business Insurance
Jul 25, 2023
What Is A Sales And Purchase Agreement For Business? – Let’s Find Out
A sales and purchase agreement for business is a binding legal contract that consists of conditions both the buyer and seller of a business or property agree upon. In any sale process, it is one of the main legal documents. It basically sets out the elements that are agreed upon in a business deal. It also consists of the number of protections of both parties as well as the legal framework for the completion of the sale. In this article, you will learn about the sales and purchase agreement (SPA) and some of its general details. Apart from that, you will also learn about how the sales and purchase agreement works for businesses. In addition to that, we will also discuss the major constituents of a sales and purchase agreement that all the parties in a sales process need to consider. Hence, to learn more about the SPA, read on through to the end of the article. What Is A Sales And Purchase Agreement For Business? According to Investopedia, “A sales and purchase agreement (SPA) is a binding legal contract between two parties that obligates a transaction to occur between a buyer and seller. SPAs are typically used for real estate transactions, but they are found in other areas of business. The agreement finalizes the terms and conditions of the sale, and it is the culmination of negotiations between the buyer and the seller.” In the case of the trading of a product or a service between two parties, there is a need for a legally binding contract that outlines the details of the agreement. This is called the sales and purchase agreement, and both parties (the buyer and the seller) need to sign the agreement contract. Furthermore, neither of the parties will be able to disobey the contract at any cost. Otherwise, it might lead to legal action. However, it is not an obligation for either of the parties to stay on the deal in question if one of them disagrees with the deal. Once both parties sign the agreement, they will need to follow the terms of the translation. Some of the essential things that are present in this agreement include - terms and conditions, purchase price, deposits made, limitations, closing date, contingencies, etc. How Does A Sales And Purchase Agreement (SPA) Work? According to Wall Street Mojo, “The sales and purchase agreement of business signifies the culmination of negotiations between the buyer and seller and restricts them from ditching each other. The two parties mutually agree upon it before signing it and making it legally binding. It does, however, require both parties to read the contract carefully and seek legal counsel before deciding whether or not to sign it or request a revision.” The sales and purchase agreement occurs mostly in real estate deals, stock purchases, mergers & acquisitions, advertising contracts, etc. On the other hand, the constituents of the SPA include its purchase price, settlement date, deposits paid during the negotiation process, limitations, contingencies, and many more. Apart from that, in such an agreement, both parties in the sales process need to agree to the contract after thoroughly reading it. For this, a business needs to obtain legal advice after signing it and requesting a change. The agreement, basically, provides protection to the interests of both parties. Apart from that, it also restricts them from working against each other or moving away after signing the deal. This factor helps in minimizing potential conflicts and helps to forecast demand and costs of business. What Are The Constituents Of An SPA? According to the Corporate Finance Institute, “Essentially, the sale and purchase agreement spells out all the details of the transaction so that both parties share the same understanding. Among the terms typically included in the agreement are the purchase price, the closing date, the amount of earnest money that the buyer must submit as a deposit, and the list of items that are and are not included in the sale.” 1. Asset Identification Here, you will get information about the specific asset that is subject to sale. In the case of a real property, the location and other details of the asset are jotted down. 2. Purchase Price and Conditions It consists of the exchange price of the transaction in question. Apart from that, the agreement also contains details about how much is already paid and how much is left. It also contains information about the way that the deposit is to be made. It also outlines how the buyer will pay the remaining balance of the transaction. 3. Due Diligence There is a section in the agreement that asks the buyer to acknowledge their due diligence in the transaction. It also contains the due diligence period, which might contain additional payments. 4. Covenants/Conditions Prior to Close The agreement also contains the next steps of the transaction process. The conditions here must be in order to make the sales process legally binding. If the parties fail to follow or if there is any inaction, then it amounts to a breach of contract. 5. Damages/Remedies In some cases, the parties need an explanation regarding what to do in case of damage prior to the sale or during the transit of a product. Hence, this section consists of various levels of damages that can occur to the asset. As per each damage, there is a remedy present. Final Thoughts Hope this article was helpful for you in getting to know about the sales and purchase agreement (SPA). A sales and purchase agreement for a business is a legally binding contract that consists of the conditions set by the buyer and seller, which both agree upon. SPAs are mostly common in real estate dealings, in which the item of transaction is large and includes a big amount. The SPA basically consists of various important information about the sales deal that includes the prices of the asset, the sales price, as well as the payment terms of the sales. It also consists of information about the due diligence period and the agreed-upon conditions. Do you have any more info to add? Share your ideas with us in the comments section below. Go For The Best And Latest Business Related Articles By Clicking Below!! What Are Articles Of Incorporation? – Importance, Working, And More Inventory Turnover Ratio: Definition, Formula, Working, And More What Are Articles Of Organization? – Let’s Find Out
Nov 10, 2023
Why Business Continuity Planning Is Essential For Your Company?
When crises happen in business, it is quite common to panic and make wrong decisions by remaining unprepared. Crises can happen anytime, and you must not start every day with the worst that can happen. However, you must stay prepared for anything to happen. You can do this with the help of a useful business continuity planning structure in place. This is because, if you do not stay prepared for the crises, it can cost your company a lot. In this article, you will learn some general details about business continuity planning. Apart from that, you will learn the importance of having such a planning structure in place. Furthermore, we will also discuss some of the major benefits of business continuity planning, which you must be aware of. Finally, we will share with you the steps you can follow to implement business continuity planning. What Is Business Continuity Planning? Business continuity planning is essential for a company as it helps in creating a prevention and recovery from the various risks and threats that can potentially affect the company. Having the plan will ensure that the personnel and assets of the company are protected. Protecting them will enable the company to start functioning by recovering quickly after a disaster situation. Business continuity planning is also essential to recover from situations like cyber-attacks where the company’s data gets compromised. Read More: What Is Risk Management? – Find Out How To Manage Risks in Business Why Is Business Continuity Planning Important? According to TechTarget.com, “The plan should enable the organization to keep running at least at a minimal level during a crisis. Business continuity helps the organization maintain resiliency in responding quickly to an interruption. Strong business continuity saves money, time and company reputation. An extended outage risks financial, personal and reputational loss.” With the help of the business continuity plan, you are making the company look after itself. You are analyzing the potential areas for risks and gathering important information from those areas. You have to have full information about those areas which are helpful for disaster situations. Furthermore, having a business continuity plan is also important to comply with legal processes. What Are The Benefits Of Business Continuity Planning? According to Investopedia, “Business continuity planning is typically meant to help a company continue operating in the event of major disasters such as fires. BCPs are different from a disaster recovery plan, which focuses on the recovery of a company's IT system after a crisis.” Basically, such a business continuity plan will help you to take stapes, including creating backups of projects, client information, and more. If something must happen to the company’s office, the satellite offices of the company will have access to all the essential information of the company. However, a business continuity plan does not work if a large population in the company is affected. It can happen at times of an outbreak of a disease. Despite that, having a business continuity plan in place will help you to improve the risk management processes of the company. Business Continuity Planning - Steps To Follow To make a great business continuity plan, it is important to have a management that oversees the plan. According to Hubspot.com, “This type of management determines the potential threats to a company and how each of these threats might impact business functions. Based on these findings, business continuity management is able to tweak the company's continuity plan to address any new potential hazards.” There are some steps you must follow to develop useful business continuity planning for your organization. Here are they: Step 1: Select your Business Continuity Team. Here, you must assemble a management team. Make sure the team is well-organized and detail-oriented. Make sure there is at least an executive manager, a program coordinator, and an information officer. Step 2: Define the objectives of the business continuity plan. To do that, you will need to know about what your end goal is. Furthermore, you must also have good information on the resources and budget based on your current projects. Step 3: Find the key players of your department and interview them. Make sure to talk with the executives as they have a bird’s eye view of the organization. Furthermore, make sure to interview the key team members of each department. This will help you to get an analysis that is useful and comprehensive. Step 4: Identify the essential functions of the business and the types of threats. By doing so, you will be able to find the major areas of your business that require the highest level of business continuity. Step 5: Assess the Risks in Every Area. Here, all you need to do is quantify the information that you have gathered from the interviews. Step 6: Conduct an Impact Analysis. Here, you will need to summarize your findings based on the costs and benefits to find out further what your priorities are. Step 7: Draft the business continuity plan. You must have already got ideas regarding what to include in the plan. Include all the requirements of the plan, followed by the procedure and end goals. Step 8: Test gaps in the plan. Once you have created your plan, you must immediately test it for any gaps. You can do it by communicating with those who are implementing the plan. Step 9: Revise your plan on the basis of findings. This will be on the basis of your findings in Step 8. Here, you will need to correct the flaws that you have found throughout the process. Read More: Business Risks – How To Identify, Manage, And Reduce Them? Bottom Line Business continuity planning is essential to hasten an organization’s recovery from a major risk leading to a threat or disaster. Basically, the company identifies all the risks that can affect the organization. The continuity plan puts in place various mechanisms and functions. With the help of these, the organization allows assets and personnel to minimize the company’s downtime. In case of a disaster in the company, it is important to implement business continuity planning to provide cover for the disaster. Do you have any recommendations regarding how to implement business continuity planning? Share your views and ideas with us in the comments section below. Read More: Entrepreneur : Who Coined The Term ‘Entrepreneur’? Intrapreneurship – Definition, Importance, Duties, And Responsibilities What Is a Franchise, And How Does It Work? – Examples, Benefits & More
Sep 02, 2023