The Amazon Store Card All You Need To Know About
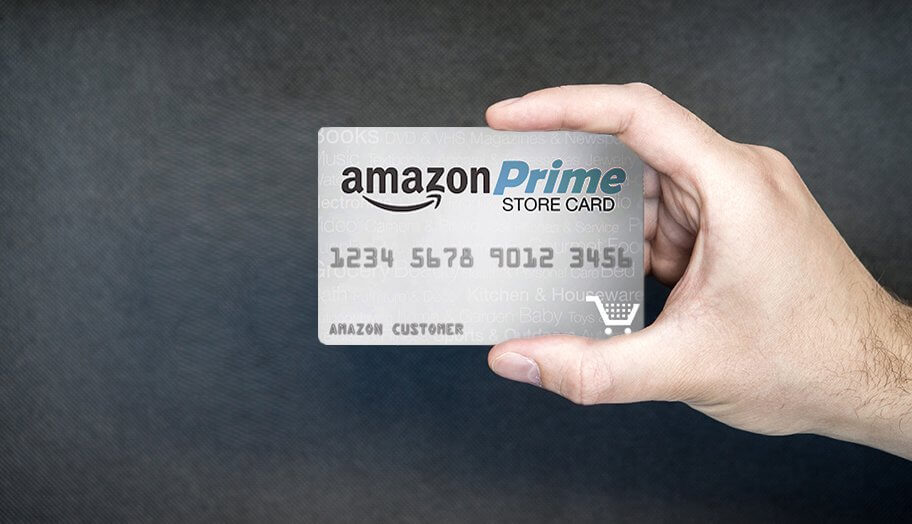
Many people shop a lot on Amazon. For them, the amazon store card will be the best choice. Synchrony bank is providing this card to the purchasers who shop a lot. In this facility, you will be able to 5% back on every purchase. Whenever you will but a thing, you will get a percentage back on your account.
Found this interesting, right? It is an exciting thing that you can get right now. To activate the amazon store card, firstly, you have to become a prime member of Amazon, then they will allow you to shop on amazon with great offers. So, start shopping onwards on amazon and get the best products in less amount of money.
Also Read: 5 Differences Between Mass-Market Paperback Vs. Paperback
How Does Store Card Works?
As we have said earlier, the amazon store card is available only for amazon prime members. So, you want to get this offer, register yourself in exchange for money. If you are already a premium member, getting these fantastic deals will be easier for you.
When you buy something, Amazon gives some points that generally get credited to your account. So, the next time you buy from Amazon, you have to pay less for the products. This feature is beneficial for regular buyers. The company also gets profits because their product selling increases.
Grab this free financing facility and get products by paying less. Then, when you become a regular buyer, you will get more exciting offers. In this way, the amazon store card works for the users.
Read More: How To Build An Ecommerce Website To Boost Your Business
Features Of Using Amazon Store Card
If you do not have any prime membership, let us tell you that it will hugely affect your purchasing on Amazon. If you take the premium membership and an Amazon store card, you will also get permission to watch films absolutely for free.
However, what amount will you pay? You will get all right back through the features. Today, you subscribe as a prime member and also pay for recharge, bills, and other things. So, don’t wait and get the features of prime membership and an Amazon store card.
1. Financing On Purchases
After purchasing the amazon store card, you will be able to do financing for six months up to $149. It is a fascinating thing because here, you will get an option for funding for six months.
If you don’t have the Amazon store card, then you must apply for the card. Get the best benefits onwards.
2. Purchase Products On Amazon
In amazon, the product price is affordable. And when you have an Amazon store card, the cost of the products will be decreased. For example, suppose a regular product price is 30$. Then, when you have an Amazon store card, the price of the product will be reduced.
In addition, you will get 5%back on every purchase.
However, there are no other sites that provide their customer this type of feature. Buy the necessary items from Amazon. You don’t have to visit the store, just order, and pay. The product will come to your door.
3. No Interest Facility
When you get the financing option, you don’t have to pay any kind of interest. So, for twelve months, you will get a no-interest facility. After that, however, get the financing up-gradation and get the benefits soon.
4. Amazon Gift Card
When the gift card application is approved by the amazon authority, you can gift someone using this card. Up to 60$ is free for months. 60$ is a considerable amount. So today, make an application for the amazon store card and get the best benefits after the approval.
How To Create Amazon Store Card
You have already learned that the amazon store card is popular and also effective for users. Now you need to know how you will apply for the amazon credit card directly. Stay with us for some more time and see the steps. So, let’s start it now.
1. Amazon Prime Membership
When you want to get the amazon store card, you have to get the amazon prime membership at the beginning. So, open your Amazon account and then go for the premium membership. Here you have to pay a bit for taking the prime membership. Pay the amount and instantly become a member of the amazon store card.
It is high time to get the card. And getting a prime membership is its first stage. So, buy the package and enjoy other activities as well.
2. Apply For The Amazon Store Card
The approval from amazon premium generally takes few times. After getting the membership, there will be a software option to click to get the amazon card. Then, press the button and apply for the amazon store card. You will get it quickly.
3. Give The Necessary Details
When you press the apply button, you will see some details they want from you. Of course, you have to fill up the details soon, like your name, age, subscription type, package details, etc.
After completing the whole work, you will be able to sen request the amazon store card. First, however, fulfilling the requirements.
4. Request For The Store Card
If you have done with the details, you have to send a request for getting the approval from Amazon. After successful submission, you don’t have to do anything.
Now you wait for amazon approval. When the approval message comes, you will get the facilities.
The Last Lines
However, these are all about the Amazon store card, and if you have more questions regarding this card, you can watch a video to get more information. So, apply for the card and wait for its approval. Then when amazon accepts your request, you will be able to get the features onwards.
However, it is the best time to start taking amazon prime membership if you are still not a member. So, start shopping using the card.
You May Like :
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles

What Is Monopolistic Competition? – Examples Of A Monopolistic Competition
Monopolistic competition exists when the companies offer competing products that are not close substitutes for one another. The barriers in the process of entry into this competition are low. The decisions of any firm do not directly affect its competitors. An example of a monopolistic competition is huge. The competing companies, in most cases, differentiate themselves on the basis of pricing and market decisions. It prevents the new competitors from entering into the industry. You must ensure that you follow the correct process in this regard. Restaurants, hotels, and electricity supply boards are some of the common examples of a monopolistic competition. You must go through it in more detail to have a clear insight into it. When you buy an LLC, it can also distinguish your firm from the others. What Is Monopolistic Competition? Monopolistic competition is a market formation that constitutes elements of both monopoly and perfect competition. In this type of market, there are many sellers offering differentiated products or services to consumers. Examples Of A Monopolistic Competition There are several examples of a monopolistic competition that you must know when you want to grow your business. Some of the core examples of the monopolistic competition are as follows:- Fast food restaurants. Apparel Industry. Personal Care products. Automobile Industry. Coffee Chains. Soft drinks. Technology Gadgets. Characteristics Of A Monopolistic Competition There are several characteristics of a monopolistic competition that you must know at your end while attaining your business goals with complete ease. Some of the core features that you should consider are as follows:- 1. Many Sellers There are numerous firms operating in the market, each producing similar but differentiated products or services. This high number of firms results in a degree of competition within the industry. 2. Product Differentiation Firms produce goods or services that are similar but not identical. They differentiate their products through branding, quality, design, advertising, or other features. To create a uniqueness in the eyes of consumers. You can get more understanding of it once you follow the examples of a monopolistic competition. 3. Low Barriers To Entry & Exit New firms can enter the market relatively easily. While some barriers, such as brand loyalty, advertising costs, or product differentiation, exist. They aren’t significant enough to prevent new entrants from competing. 4. Non Price Competition Firms compete not only on price but also on product differentiation, advertising, customer service, and branding. This non-price competition allows firms to attract customers without solely relying on lower prices. Network marketing can be a business model for monopolistic competition. 5. Partial Control Over The Price Unlike perfect competition, where firms are price-takers, firms in monopolistic competition have some control over the price of their products. However, they are constrained by the reaction of consumers to price changes. The price differentiation here plays a vital role in the process of brand differentiation. 6. Independent Decision Making Each firm makes independent decisions regarding pricing, production, and marketing. Strategies based on its perceived market demand and unique product attributes. You need to understand the reality while making independent brand decisions for your product and services. Examples of a monopolistic competition can be of great help to you. 7. Selling Cost Firms incur costs for advertising, marketing, and creating perceived product differentiation. These selling costs contribute to non-price competition and are essential for firms to distinguish their products in the market. 8. Imperfect Information Consumers may have imperfect information about the differences between products. It allows firms to create perceived differences through marketing and advertising strategies.You need to get through the complete process that can assist you in meeting your brand requirements with ease. 9. Limited Market Power While firms have some degree of market power due to product differentiation, it is limited. Consumers have options and can switch to similar products offered by other firms if prices or quality differ significantly. You can follow the examples of monopolistic competition to have a clear understanding of it. Pros & Cons Of Monopolistic Competition There are several pros and cons of monopolistic competition. You must understand the process that can make things easier for you to know the details of the competition. Some of the core Pros and Cons of Monopolistic Competition are as follows:- Pros Of Monopolistic Competition There are several pros of monopolistic competition that you must know at your end to have a clear insight into it. Some of the pros of it are as follows:- 1. Incentive For Innovation Firms in monopolistic competition continuously innovate and differentiate their products to attract customers. This drive for innovation leads to the development of new features, designs, and better-quality products over time. 2. Consumer Choice Consumers benefit from a wide variety of product choices and options. Differentiated products cater to diverse consumer preferences, allowing individuals to choose products that align with their specific needs and preferences. Here your contribution margin matters a lot. 3. Non-price Competition Firms compete not only on price but also on factors like quality, design, branding, and customer service. This encourages firms to focus on improving product quality and providing better customer experiences rather than solely engaging in price wars. Cons Of Monopolistic Competition Along with the pros, there are several cons of monopolistic competition as well. You need to be very careful about it while going through the cons of monopolistic competition. 1. Excessively High Cost Firms in monopolistic competition spend significant amounts on advertising, branding, and product differentiation. These selling costs can be substantial and may lead to higher prices for consumers. 2. Less Price Sensitivity Consumers might be less sensitive to price changes due to perceived product differentiation. This can result in firms having some pricing power, leading to higher prices without a significant loss of customers. Final Take Away Hence, if you want to overcome the monopolistic competition concept, then you must follow the examples of monopolistic competition. You must get through the details of the monopolistic competition to have a clear insight into it. You can share your views and opinions with us in our comment box. Feedback from the readers helps us to draft better content for you next time. Try to help us in this regard. Delve Into More Business Articles!! Sabbatical Leave: What Is It, And How Does It Work? What Are Distribution Channels In The Context Of Business? What Is Wholesale Distribution? – Importance, Benefits, And Examples
Nov 26, 2023
StashFin Personal Loan Review – Interest Rates, Loan Amount, Eligibility, And More
StashFin offers instant personal loans at interest rates of 11.99%, with loan amounts reaching up to 5 lakhs INR. The loan offers are available for up to 4 years of time. The best part is that you can get an instant personal loan as fast as 4 hours of time. Only minimal documentation is required to get a loan. However, these factors are applicable when you are eligible for the loan. In this article, you will get to know about StashFin personal loans and the variety of necessary details about the loan provider. The details will include the rates of interest, eligibility, and other important information related to loan offerings by the company. Finally, we will give you some details of customer reviews which can be helpful for you to get a better idea of StashFin. Hence, to get a full idea of the loan offerings of this company, read on through to the end of the article. StashFin – What Do They Offer? StashFin is a platform that offers personal loans to salaried and self-employed individuals. You can apply for loans both through the website and also the StashFin personal loan app. The types of loans offered by StashFin include Marriage loans, Cash loans, Small loans, Medical loans, Travel Loans, Home Renovation loans, Shopping loans, Personal loans, and Debt Consolidation loans. Loan AspectsWhat StashFin Offers You?Loan AmountUp to INR ₹ 10 lakhLoan TenureIt can be up to 4 years, depending upon eligibility and the loan amount.Rate of Interest On Loans11.99% – 59.99% p.a. (per year) depending on the type of loan borrowed.Loan Processing FeesProcessing fees depend upon the loan amount. However, it can extend up to 10% (excluding GST) of the amount on each loan.- 0% – 10%, excluding GST (Borrowers should pay a processing fee on the withdrawn amount every time they load their StashFin Card using the StashFin App).Collateral or MortgageDepends on the type of loan applied for.Bounce Charges₹ 500 on every bounced cheque, NACH, or failed EMI payment.Loan Review TimeIt can be as less as 4 hours.Late Payment Of The LoanA loan default or a late payment will not allow a borrower to redeem rewards.Loan RepaymentThe repayment period is up to 36 months. All loan payments are made through EMIs via electronic payments. Read More: GGP Share Price Forecast: Everything You Should Know How To Apply For A Loan From StashFin? If you want to apply for StashFin loans, you will just need to download the official app or visit the website and hit the "Apply Now" button. Once you click the button, you will get to a page where you will need to enter your name, mobile number, pin code, and PAN. Later, you will need to fill up a form and provide all your proofs. Once your documents and your credit record are verified, you can get a loan as quickly as 4 hours. StashFin – What Is The Loan Eligibility? The following are the major eligibility requirements that a borrower needs to comply with to avail of loans from StashFin: Loan RequirementsEligibilityAge of the borrowerMinimum 18 yearsStashFin credit scoreA better credit score (that is, above 750 for CIBIL TransUnion) can help a loan applicant to avail of personal loans at lower rates of interest.Type of EmploymentSalaried or self-employed.Minimum monthly income₹ 15,000 per monthWork ExperienceDepends on the type of loan applied for.Required DocumentsFor Salaried- ID proof – PAN Card- Address Proof – Aadhaar Card- Copy of a cheque for the salary bank account- Salary slips for the last 3 months- Bank statements for the last 6 months For Self-Employed- Income Tax returns- GST Returns- Proof of business ownership and continuity- Bank statements for the last 6 months- Audited financial statements for the last 2 years- Office address proof Read More: PooCoin Stock Forecast: Everything You Should Know StashFin – Top Customer Reviews The following are some of the top customers reviews that we have found from some of the famous review platforms on the internet. Hope these customer reviews can be helpful for you to get a better idea of the services and loan offerings of StashFin: Source Source Source Summing Up Hope this article was helpful for you to get an understanding of the offerings of StashFin. The company offers loans at reasonably good interest rates in return for their services and loan amounts. If you are a small-wage earner and in need of a loan, you can borrow loans easily from StashFin. We did not find many negative reviews on StashFin. However, it is also recommended to read the negative reviews by going to various review websites to find out what can go wrong. Always borrow loans when you are fully sure. Do you know of any better loan providers that offer loans at good interest rates? Share some of them with us in the comments section below. Read Also: What Is Stockinvest? Is It Legit And Working mPokket: Information, Eligibility Criteria, Interest Rates, Review & More Medplus Health IPO News, Allotments, And Updates You Should Be Aware Of
May 06, 2023
Consideration For Choosing Or Comparing Credit Cards
Choosing the right credit card, also known as charge plate or plastic money, is an important decision that can offer valuable perks, financial flexibility, and benefits. In this article we’re going to be assessing a number of factors with the aim of making the right decision while choosing the card. Consideration will be given to payment flexibility and terms, credit card types, network, and terms and conditions. Lastly, thoughts will also be given to its universality. Comparing Credit Card Payment Flexibility and Terms and Terms There is not an iota of doubt on the fact that credit cards have offered innumerable benefits to people. Amidst their different facilities, flexibility is undoubtedly one of them. It has undoubtedly provided the necessary convenience to people. We shall compare payment flexibility and terms associated with plastic money. To get information on comparing credit cards visit: https://moneywise.com/. Analyzing Payment Flexibility Options Across Credit Cards Some cards have a flexible due date that suits your financial situation and allows you flexibility in managing payments. We all know that the management of payments is indeed one of the biggest challenges entrepreneurs face in their day-to-day lives. Another form of control offered by other cards is the adjustment of minimum payment based on financial capacity. Other flexibility options on the block are the allowance to select how often you make payments such as monthly, bi-weekly, etc. Evaluating the Importance of Payment Terms The impact on payment scores positively influences your credit score, while late payment significantly affects your reputation. Payment terms influence interest accrual on the outstanding balance, so it shouldn’t be ignored. Fees and penalties are imposed based on payment terms; it’s why it is important to adhere to due dates. Responsible Credit Card Usage for Optimal Payment Terms Timely payments help in maintaining optimal payment terms that affect your financial standing positively. Also, note that if you maintain a low monetary utilization ratio by not exceeding your threshold, your payment management terms will be effectively enhanced. Related: Credit Card Frauds And What You Can Do To Avoid Them Comparing Credit Card Type and Network Plastic money, as a versatile financial tool, offers a variety of benefits depending on network affiliation and types. Understanding Credit Card Types Credit cards have undoubtedly revolutionized the entire payment system. They not only helped with the quick transfer of money but also facilitated business development. However, we understand the different types of credit cards in this section. · Secured: This card type is good for people rebuilding their credit card history. It requires a security deposit. · Unsecured: These are the most common types used to cater to a wide range of financial needs and require security deposit. · Reward: Rewards or incentives such as cashback, points, or miles depend on your spending pattern. You will find different reward offers from different providers. You should therefore choose one that suits your lifestyle. For example, you can compare Amex Gold vs Chase Sapphire Preferred to see what each offers before making a choice. · Student: These types are designed for students to help them establish their credit history. These card types have lower monetary limits. Analyzing Different Credit Card Networks Different types of plastic money are available in the financial market. The main ones are - · Visa: This option is versatile with extensive network offerings. It is widely accepted globally and caters to various consumer needs. · Mastercard: This option is also accepted globally and comes with different beneficial offers and perks that make it a popular choice among consumers. · American Express: This premium credit card type is favored by customers seeking rewards and luxury. The American Express is also known for its exceptional customer service. · Discover: Discover doesn’t have any annual fees and is good for individuals looking for straightforward rewards such as cash-back rewards. Comparing Terms and Conditions of Plastic Money Plastic money has ushered in a revolution in the entire circle of the payment system. However, we try to understand some of the ways through which the entire payment system. Different financial organizations have their own terms and conditions for their credit cards. Terms and conditions are laid out guidelines and rules governing the operations and responsibilities of both the issuer and cardholder. Key Comparison Factors Interest rates, credit limits and penalty charges are some of the critical terms and conditions to watch out for when signing up for the plastic. You should carefully note the penalties imposed for late payments, exceeding the threshold, or other infractions. Making Informed Decisions Based on Terms and Conditions Before committing to terms and conditions you’re encouraged to read it thoroughly. By comparing these terms with those across multiple offers, you’re likely to find the best suited for you. Assessing Credit Card Versatility: International Use Plastic money offers flexibility and convenience for transactions worldwide as a financial tool because of its ubiquity and its technological integration. They facilitate seamless currency conversion, allow for online transactions and, above all, enjoy global acceptance providing a comfortable payment option for travellers. Comparing Plastic Money Networks for Global Usability American Express, Visa, Mastercard and Discover are common monetary instruments that have gained extensive worldwide acceptance and used globally for transactions by travelers. This has made them the preferred choice for many individuals the world over. Merits and Demerits of Using Credit Cards Internationally Convenience, a secure way of making purchases and the accrual of rewards and benefits are some of its advantages. Drawbacks such as incurring foreign transaction fees and exchange rates, which may not be favourable may be applied by the plastic money companies. You can read this article to learn more about this international type of payment. Conclusion With comparison from the standpoint of information, one can make choices that best align with one's lifestyle and financial goals. However, a good understanding of its diverse landscape, terms, conditions, and other factors is crucial to making the right choice. The right card is the key to optimizing your financial experience while traveling or making international purchases. Read Also: The Amazon Store Card All You Need To Know About California No Credit Check Loans: A Solution For Those With Poor Credit Home Credit: Information, Eligibility Criteria, Interest Rates, Review & More
Oct 20, 2023
Navigating Home Financing: A Deep Dive Into Non-Qm Mortgage Loans
In the realm of mortgage financing, Non-QM (Non-Qualified Mortgage) loans have emerged as a flexible and inclusive option for individuals who may not fit the traditional lending criteria. This comprehensive guide aims to shed light on the intricacies of Non-QM mortgage loans, exploring their definition, eligibility criteria, benefits, and considerations for those seeking alternative paths to homeownership. If you're curious about Non-QM loans and want to learn more, click here. Understanding Non-QM Mortgage Loans What Are Non-Qm Loans? Non-QM loans fall outside the guidelines set by government-sponsored entities like Fannie Mae and Freddie Mac. Unlike traditional Qualified Mortgages (QM), Non-QM loans provide a more inclusive approach to lending by considering a broader range of borrower profiles. Eligibility Criteria For Non-Qm Mortgage Loans 1. Credit Flexibility Non-QM loans are designed to accommodate borrowers with unique credit profiles. Individuals with a recent bankruptcy, foreclosure, or fluctuating income may find Non-QM loans more accessible. 2. Debt-To-Income Ratio Variation While conventional mortgages often adhere to strict debt-to-income ratios, non-QM loans allow for greater flexibility. Borrowers with higher debt-to-income ratios may still qualify based on other compensating factors. 3. Alternative Documentation Traditional mortgages often require extensive documentation to verify income and employment. Non-QM loans, however, may accept alternative forms of documentation, making them more suitable for self-employed individuals or those with non-traditional income sources. 4. Unique Property Types Non-QM loans can be more lenient when it comes to financing unique property types. This flexibility is beneficial for borrowers looking to invest in non-traditional homes or properties. Benefits Of Non-Qm Mortgage Loans 1. Accessibility For Non-Traditional Borrowers Non-QM loans provide an alternative for borrowers who don't meet the stringent criteria of conventional mortgages. This inclusivity extends to self-employed individuals, retirees, and those with unique financial circumstances. 2. Flexible Underwriting Criteria The flexibility of non-QM loans allows lenders to consider a broader range of factors beyond the traditional credit score and debt-to-income ratio, providing more opportunities for approval. 3. Unique Property Financing Borrowers interested in financing unique or non-traditional properties may find Non-QM loans more accommodating than traditional mortgages. 4. Credit Repair Opportunities For individuals with recent credit challenges, Non-QM loans can serve as a stepping stone to homeownership while providing an opportunity to rebuild credit over time. Considerations And Drawbacks 1. Higher Interest Rates Non-QM loans typically carry higher interest rates in contrast to conventional mortgages. It's crucial for potential borrowers to thoroughly assess the long-term financial implications. 2. Potential For Larger Down Payments Some Non-QM lenders may require larger down payments, impacting the initial financial commitment for borrowers. 3. Limited Regulatory Protections Non-QM loans are not subject to the same regulatory protections as Qualified Mortgages. Borrowers should carefully review loan terms and conditions. 4. Variable Loan Terms Non-QM loans may come with variable terms and conditions. Borrowers must understand and assess the specific terms offered by lenders. The Non-Qm Mortgage Loan Application Process 1. Pre-Application Consultation Prospective borrowers should engage in a pre-application consultation with a Non-QM lender. During this phase, the lender will assess the borrower's unique financial situation and discuss available loan options. 2. Documentation Submission Borrowers will be required to submit documentation to support their application. This may include alternative income documentation, proof of assets, and other relevant financial information. 3. Underwriting And Approval The lender will conduct a thorough underwriting process, considering the borrower's unique circumstances. Upon approval, the borrower will receive a loan offer with specific terms and conditions. 4. Property Appraisal As with any mortgage, a property appraisal may be required to determine its value and suitability for financing. 5. Closing And Homeownership Upon completing the necessary steps and meeting any remaining conditions, borrowers can proceed to the closing. This involves signing the required paperwork, officially making them homeowners. Conclusion Non-QM mortgage loans offer a valuable alternative for individuals who may not fit within the parameters of traditional lending. While they come with certain considerations and potential drawbacks, the inclusivity and flexibility of Non-QM loans make them a viable option for a diverse range of borrowers. As with any significant financial decision, thorough research, consultation with non-QM lenders, and a clear understanding of the terms are crucial. If you're intrigued by the possibilities of Non-QM mortgage loans and want to explore more, click here for additional information. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Dec 04, 2023