What Is Indemnity Insurance ? And Its Different Types – Let’s Discover
As an administrator of a business organization or an enterprise, you must be aware of the unforeseen circumstances, and must step up to thwart them as it can happen to your business. Such circumstances can be perilous for the business, and can even lead to many losses for the business. This is where an indemnity insurance comes into play.
In this article, you will learn in general about indemnity insurance along with an example of the same. In addition to that, we will also discuss the major types of indemnity insurance that are available for a business. You will also learn how the various types of indemnity insurance options can help you, and in what regard. Hence, to find out more about the topic, read on through to the end of the article.
What Is An Indemnity Insurance?
According to Wall Street Mojo,
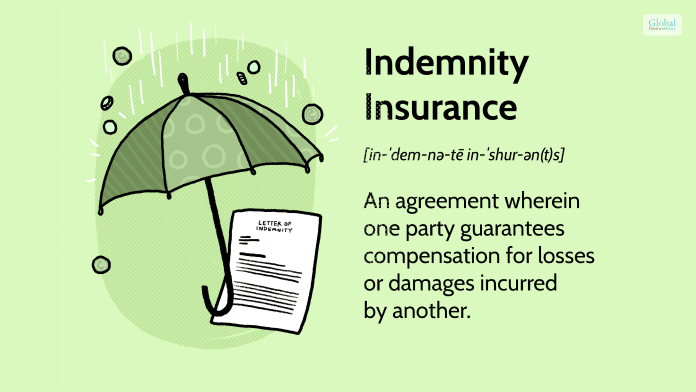
“Indemnity insurance refers to the insurance coverage that safeguards an insured against the monetary losses arising out of professional negligence. Like any other insurance, this also provides coverage in exchange for regular premium payments from the insured.”
Let’s see an indemnity insurance example, where you are the owner of a wealth management firm, and a client is suing your firm alleging a financial loss, after following the advice of the firm. If the firm had an indemnity insurance beforehand, it would help in covering the monetary damages. These monetary damages including all the legal expenses that were incurred during the lawsuit proceedings.
Indemnity insurance is a form of protection that compensates for financial losses or damages, offering various types to cater to different professional needs, including the specialized area of guardian physician disability insurance. This specific type of insurance is designed to safeguard physicians against loss of income due to a disability, recognizing the high stakes of their profession and the intensive training it requires.
Guardian physician disability insurance provides tailored coverage options that can be adjusted according to the unique risks and financial implications a physician might face if unable to practice. It’s crucial for medical professionals to consider this insurance as it not only covers their personal income but also helps in maintaining their standard of living if they become disabled.
Understanding the nuances and benefits of physician disability insurance enables physicians to make an informed choice, ensuring their financial security in the face of unforeseen health challenges.
The indemnity insurance policy compensates the insured party for not only the unexpected losses or damages, but also the amount of the loss itself. All these coverages are up to a certain limit.
According to USNews.com,
“Examples of indemnification include an insurance company paying to repair or replace damaged property, reimbursing medical bills, or covering legal settlements and fees that the insured is held liable for.”
These policies are designed in such a way to protect business owners and professionals, after they have made a fault in a particular event, which created the case of malpractice and misjudgment. The case comes in the form of an indemnity letter.
Read More: The Types Of Business Insurance Needed For Every Business
How Does An Indemnity Insurance Works?
An indemnity letter compensates in the case of losses and damages. In a legal situation, this also means an exemption from being liable for the damages made. Here, the party that is insuring promises the party that is getting insured for the coverage of the losses, in exchange for the premiums that the policyholder is paying.
According to Investopedia,
“Indemnity insurance is a supplemental form of liability insurance specific to certain professionals or service providers. Insurance professionals provide counsel, expertise, or specialized services.”
However, you must not confuse this type of insurance with a simple general liability insurance or any other commercial business insurance.
A financial indemnity insurance protects you from claims that are arising from the certain negligence or a situation when the business fails to perform, which further results in a financial loss for the client. The policy helps the individual or the business from a looming legal entanglement.
This is because, if your client has suffered a loss, he/she has the right to file a civil claim. Your indemnity insurance helps you in this case, by paying the costs associated with the litigation, as well as the cost of damages that the court awarded.
What Are The Major Types Of Indemnity Insurance?
Indemnity insurances can be of different types. The following are the major types of indemnity insurance options that you will come across:
Professional Indemnity Insurance Claim
As per the claims of Wall Street Mojo,
“Professional indemnity insurance is curated to protect professionals against specific instances such as misjudgment. These insurances help companies deal with legal expenses and settlement costs.”
It is the type of commercial indemnity insurance that protects you as a business owner or a professional if there is an alleging complaint against you. For example, if the client thinks that the business actually behaved negligently, and failed to perform as per promise. This is different from a simple commercial liability insurance, which protects your business to cover the injury costs of a client on the premises.
Hospital Indemnity Insurance
According to Investopedia,
“Hospital indemnity insurance is a type of supplemental insurance that pays for hospitalization costs that are not covered by other insurance. This type of insurance is frequently taken out by businesses in case their employees are injured on the job.”
Such a type of insurance can be beneficial, as most people in the US do not have enough savings to cover the medical bills that are unplanned. Here, as per the plan, the insurer pays the cash directly to the employees. This acts as a supplemental insurance to pay for the costs associated with admission in a hospital.
Fixed Indemnity Insurance – What Is Indemnity Plan?
Having a fixed indemnity insurance plan can help you to get fixed benefits for healthcare events, regardless of the actual insurance cost. Such a plan allows you to get a fixed amount of money for every hospital admission, or even a certain amount for each day of admission in a hospital. However, your must also know that a fixed indemnity insurance plan is not covered under the Affordable Care Act.
In addition to these, when you purchase premiums of indemnity insurances, you must focus on the aspects of the premium about what the insurance does not cover. This is because you will not get an indemnification outside the parameters set by the policy. Furthermore, you will also not receive restitution at a higher value that what is promised.
Read More: Is Startup Business Insurance Necessary For New Businesses?
Final Thoughts
If you are a business owner, having indemnity insurance can help a lot in dealing with unforeseen situations. Hope this article was helpful for you to get a good idea of what an indemnity insurance is, and what are the major types of indemnity insurance available for you. However, before you purchase your insurance, make sure to read the policy carefully. How do you think indemnity insurance can be helpful for your business? Share your thoughts with us in the comments section below.
Read More:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
What Is Commercial Insurance? And Its Different Types – Let’s Discuss
What is commercial insurance? – It is intended for commercial institutions like businesses, enterprises, and industries. These insurances cover various needs related to businesses. Full coverage of commercial insurance for businesses is essential for the protection of the business, its properties, and its employees. In this article, you will learn in general about commercial insurance policies and various common business insurance types. Furthermore, you will also learn a few details about the types of commercial insurance that occur in the business. Hence, to learn about commercial insurance for businesses, read on through to the end of the article. Commercial Insurance Definition – What Is Commercial Insurance? Commercial insurance is created to provide coverage to businesses, enterprises, corporations, and industries. The coverage is for the business, its employees, and its properties. There are different businesses having different types of situations and needs. Hence, based on these needs and situations of the business, there are different types of commercial insurance available. According to BankBazaar.com, “Commercial insurance is a type of business insurance that offers solutions for industrial sectors including but not limited to construction, manufacturing, telecom, textiles, logistics etc. These solutions aim to offer a safety net for business operations and assets when the need arises.” Such a type of insurance can help your business by providing protection against the associated risks which can impact the growth and success of the business. Furthermore, in some cases, there are other types of commercial insurance as well, which help in protecting the reputation of the organization and also its well-being. Moreover, some commercial insurances help safeguard the financial aspects of a business. On a side note, if you want to learn about the best lead management software options, click on the link given. Read More: Guaranteed Issue Life Insurance: Is it Worth It? What Are The Types Of Commercial Insurance? The difference between commercial insurance and personal insurance lies in the fact that the former helps in covering multiple factors of the business, like its stakeholders and employees. With commercial insurance, the insurance coverage is much higher, as there are a greater number of associated physical properties. Furthermore, the agents and carriers that are associated with commercial insurance are trained in such a way that they can deal easily with the threats and risks of a business. There are different types of commercial property insurance, as well as insurance to deal with liabilities, interruptions, workers, automobiles, and many more. The following are the major types of commercial insurance that you must know about: 1. General Liability Insurance This insurance is for those situations when, for example, a customer gets injured at the place of business or an employee did something or failed to do something. Here, general liability insurance helps in covering the expenses associated with legal fees and medical costs. Various copyright-related issues and infringements are also covered under this insurance. The insurance also covers damage to another person’s belongings as well as personal injuries like libel and slander. 2. Business Income Insurance According to The Hartford, “Business income insurance coverage is a type of business insurance that helps your company replace lost income if it’s unable to operate due to covered property damage. Business income insurance acts as business interruption insurance or income protection insurance.” This insurance helps in covering the pay of the income that the business lost. Some of the costs covered by this insurance include: Employee’s wages and payroll Payment of loans and taxes Payment of mortgage and rent Income loss during restoration 3. Commercial Property Insurance This type of insurance helps your business to protect the buildings and property equipment that are rented or owned by the business for the proper running of the business. However, you must understand that natural disasters are not covered under these types of insurance. For example, in cases of floods, earthquakes, and storms, when the property gets damaged, the insurance will not cover it. 4. Professional Liability Insurance Also known as Errors and Omissions Insurance (E&O), this insurance is for a situation where the business makes a mistake in providing a service to a customer. As per the information from TheHartford.com, “Professional liability insurance protects businesses when employees make mistakes in the professional services they’ve provided to customers or clients.” 5. Workers’ Compensation Insurance If an employee gets ill or injured while on the job, then the workers’ compensation insurance comes into play. This helps the workers of the company in better recovery so that they can get back to work as fast as possible. In the United States, most states make businesses comply with the laws that require workers' compensation insurance. Hence, by complying with the state's law, you will not face penalties and criminal charges. 6. Commercial Auto Insurance According to GEICO.com, “Commercial vehicle insurance is a policy of physical damage and liability coverages for amounts, situations, and usage not covered by a personal auto insurance policy. This type of business insurance covers many types of commercial vehicles.” Commercial auto insurance is required for automobiles that are different from the ones that are used for personal causes. Such insurance is meant for the cars, trucks, and vehicles used for your business. 7. Data Breach Insurance Also known as Cyber Insurance, these types of insurance help you to respond to breaches of data if personal information or important business information and data are lost or stolen. According to TheHartford.com, “Cyber liability insurance is typically meant for larger businesses and offers more coverage to help prepare for, respond to, and recover from cyberattacks.” 8. Commercial Umbrella Insurance According to Nationwide Mutual Insurance Company, “Commercial umbrella insurance provides an extra layer of liability protection by covering costs that go beyond your other liability coverage limits.” It helps complement the other liability coverages when their limits are already reached. It covers the same types of costs that business liability insurance covers. Read More: Maximizing Home Insurance Coverage For Your At-Home Business With Riders Summing Up Hope this article was helpful for you to make you understand what commercial insurance is and the types of commercial insurance available. So, choose the right one based on your needs at the moment. The bigger your business gets, the more you will gradually have to get all the insurance. Do you think commercial umbrella insurance is useful for a small business? Share your opinions with us in the comments section below. Read Also: Financial Planning Tips For Different Stages Of Life 4 Benefits Of Using A PPC Agency For Your Business 5 Most Powerful Marketing Strategies That Will Change Your Business
Jun 23, 2023

Is Startup Business Insurance Necessary For New Businesses?
Let me guess - you have a new startup business. However, while your business will be up and running (or already is), you realize you don't have insurance against any damage that might happen to it. So what do you do? You invest in startup business insurance. If you wish to learn about the various types of insurance for startups, read this post till the end. Is Startup Business Insurance Necessary For New Businesses? Yes, startup business insurance costs are necessary for a new startup business because: 1. Provides Financial Compensation Against Business Misfortunes The main point of having startup business insurance is to protect yourself from any misfortune that might befall your startup. Whether it's data theft, property damage, lawsuits, or more, insurance will provide financial backup for all such problems. 2. It Attracts Investors Most professional business investors are smart about understanding which businesses to invest in. Therefore, if they see that your startup business is covered by insurance, they will rest easy knowing that they will not suffer a loss if anything happens. 3. Top Talent Gets Attracted Nowadays, employee benefits have become necessary for all businesses. Therefore, if you don’t provide employee benefits like health insurance, they are less likely to be interested in working for your startup. 4. Builds Better Customer Relations If you have a B2B (Business to Business) startup, your client businesses might ask for proof of insurance before doing business with you. Other businesses are less likely to do business if you cannot provide insurance. Different Types Of Startup Business Insurance If you wish to learn more about different types of startup business insurance before purchasing one, then here we are. Continue reading to learn about all the main business insurance for startups and various start up business insurance costs. 1. General Liability Insurance You can expect your employees to suffer from accidents if you have a production business with your own production centers. For example, while working heavy machinery, workers can injure themselves. Moreover, they can injure themselves when they are carrying heavy things from one place to another. The possibilities are endless here! Therefore, General Liability Insurance is the first startup business insurance you must invest in. This will help you compensate employees who injure themselves while at work. In addition, it also covers damage done to clients' assets. 2. Errors And Omissions Insurance (E&O) This startup business insurance is necessary for new businesses offering professional services. It’s necessary for such businesses because mistakes in services provided, mostly in the form of errors, are more common than you think. Making mistakes in services provided to clients can make them suffer financial losses. Therefore, before they can file a lawsuit against you, you can simply offer compensation to them. This professional courtesy is helpful because doing so often improves your connection with clients. Doing so might make them return. 3. Workers' Compensation Insurance This startup business insurance is a more narrowed-down form of General Liability Insurance. In this case, the insurance serves as health insurance for your employees. If any of your employees suffer physical harm due to the nature of work or even fall sick while working, you can compensate for their recovery. This is important for startup businesses because many forms of health insurance will deny their services to businesses. In addition, it also offers disability benefits to employees. 4. Cyber Liability Insurance Due to the ever-increasing need to digitize daily business activities, your business data is now more vulnerable than ever. This is because all your business data is stored in online cloud drives, which hackers can skillfully hack. Moreover, with online banking being the most common system of making payments, all your financial data is also stored online. Therefore, a single data breach and theft here can result in hackers stealing all your financial data and money. Therefore, having startup business insurance is necessary to protect your business data (which is worth a lot). This insurance is necessary if you have a business that uses many digital resources and stores data digitally. This business insurance saving helps compensate for data breaches and theft. 5. Business Owners Policy (BOP) Every business has a commercial address - a workspace, office, or headquarters. Therefore, your business office is a form of commercial asset. So are your employees and clients (somewhat). If any harm comes to them, you will have to compensate them. Therefore, choose a startup insurance company or the best insurance apps that provide a Business Owners Policy (BOP). This form of startup business insurance covers both General Liability Insurance and Commercial Property Insurance. 6. Employment Practices Liability Insurance (EPLI) A time might come in the future when an employee (or ex-employee) of your office might sue you. No matter what the cause is - whether it's discrimination in the workplace, harassment, or wrongful termination - it will always portray your business in a bad way. Therefore, invest in Employment Practices Liability Insurance to prevent your new business from being termed as an employee rights violator. An EPLI will allow you to compensate your employees, preferably with an off-the-court settlement, before it can go public. 7. Commercial Auto Insurance If you have a start-up business that involves transporting goods and materials, it's best to ensure your vehicles. They might get involved in an accident on the road or, worse, get stolen. Therefore, Commercial Auto Insurance is necessary for new businesses. This startup business insurance will help you get compensated for any damage caused to your vehicles. Therefore, this is a necessity for dropshipping businesses. 8. Directors And Officers Insurance (D&O) Starting a new business is not easy. You must make a foolproof business plan that is good enough to satisfy investors and stakeholders. You can do this by yourself or by forming a board of directors to aid you in decision-making. However, a bad decision and course of action suggested by a director can single-handedly dissatisfy investors and make them leave. Worse, it can even bring your startup to the ground. Therefore, you must invest in startup business insurance like Directors and Officers Insurance (D&O). This will help you compensate for investors' lawsuits and other lawsuits that happen due to decisions made by directors and officers. 9. Commercial Property Insurance When you start a business, you have a workplace - its headquarters. All your equipment is stored here, and it is where business takes place. However, what will you do if it gets destroyed by a fire or a storm? Or does most of your expensive equipment get burgled? This is where a startup business insurance like Commercial Property Insurance reduces a lot of financial loads when such misfortune befalls your business. Therefore, if you want your outdoor restaurant furniture durability and style to remain the same, investing in commercial property insurance will be a smart choice. Conclusion: Insure Your Startup Business Now For Better Protection Having a startup business insurance like the ones explained above will prove to be valuable in times of crisis. No matter what damage befalls your business, these insurances will provide backup in such times of need. Therefore, it's best not to ignore them. If you need a startup business insurance consultation, comment below! Read Also: Maximizing Home Insurance Coverage For Your At-Home Business With Riders Guaranteed Issue Life Insurance: Is it Worth It? 11 Tips For Saving On Business Insurance
Jun 26, 2023

Maximizing Home Insurance Coverage For Your At-Home Business With Riders
Home insurance is a type of property insurance that helps cover expenses related to property damage and loss. It can offer financial and legal protection in case an unfortunate incident happens within an insured property. The specific coverage can vary depending on your policy. In most cases, however, it does not cover home-based businesses. The good news is that you can include this as a rider. This way, you can have peace of mind. Make the most of your home insurance. Read on and we’ll share some tips on how you can maximize your coverage for your at-home business. How Can Insurance Riders Protect Your At-Home Business? While conventional home insurance can protect your home, it might not offer the same coverage to your home-based business. Whether a self-employed professional or a home-based business owner, you might need insurance riders for additional protection. Below are some of the most common instances when home insurance riders may prove necessary: When your customers go to your house for face-to-face meetings, buy products, or avail of your services When you keep business inventory or supplies in your house When you have employees working in or out of your home When you can potentially lose business income because of damage to your home When you have a computer that keeps business/customer data Start By Calling Your Insurer If you’re building a home-based business, one of the first things to do is to call your current home insurance provider. This can be an opportunity to clarify what’s covered and what isn’t. This way, you can gauge the need to purchase additional coverage, depending on your business needs and financial capacity. More so, calling your current home insurance provider might make you eligible for a discount. For instance, this can happen when you purchase at-home business insurance as a rider compared to a separate policy from the same company. You can qualify for insurance bundling and enjoy cheaper rates. It depends on what the insurer can offer. Work with an agent to find the right rider coverage. Don’t hesitate to ask questions. Provide realistic projections about your business. For example, if you anticipate it to grow big, you might need more than a rider in the future. Go Beyond The Price Many home business owners will consider the price when buying an insurance rider. While such is a crucial factor, it should not be the sole basis of your decision. Cheaper isn’t always better. It’s critical that you read the terms and conditions to know the specific coverage. In most cases, you should not mind the additional expense if it means peace of mind. Coverage You Might Need As you evaluate the options for an insurance rider, one of the most important is to identify your needs. From here, it will be easier to narrow down the possibilities. For instance, it is useless to be paying coverage for a business vehicle if you don’t have one used for your business operations. Among others, one that you might need is business property insurance. When you file a property damage claim for your home insurance, it might not cover those you use in your business if you don’t have the right rider. Meanwhile, when you add business property insurance, you can also insure business equipment, such as computers and printers. More so, your at-home business insurance rider can also include liability coverage. This type of business insurance protects against financial losses from property damage, bodily injury, medical expenses, and defending lawsuits, among others. Consider Other Ways To Increase Coverage In this post, our focus is on at-home business insurance riders. The latter is an endorsement policy on top of your existing insurance. According to the Insurance Information Institute, you can enjoy coverage of up to $5,000 for as low as $20 per year. In most cases, qualifying for a rider has a maximum requirement regarding business receipts, depending on the insurer. For instance, it can be limited to those with a maximum business receipt of $5,000. For larger business receipts, however, a rider may not be enough. In this case, you might need to purchase a standalone business owner's policy. It can combine property and liability coverage in one different from your home insurance. Conclusion With more and more people operating their businesses at home, insurance becomes more important. Your standard home insurance might not cover your business needs, so purchasing a rider can be a good idea. Find a reputable insurer and go beyond price when exploring alternatives. Meanwhile, if the business is larger, a rider may be insufficient. Instead, you’ll need stand-alone business insurance. Additionals: Tips To Update Your Manufacturing Business Through CNC Machines What Is An Operating Agreement: Does Your Business Need One? Understanding How VPS Hosting Can Help You Grow Your Online Business
Jan 20, 2023
Risk & Reward: Navigating The Game Of Small Business Insurance For Lasting Peace Of Mind
In a fluctuating abroad of small enterprises, the quest for achievement usually comes with the help of several risk variables. Small enterprise owners are familiar enough with the challenges they have to deal with, but what about those unexpected events that might undermine their hard work? This is where the game of small enterprise coverage comes into use, providing a tactic to avoid dangers and ensure long-term peace of mind. In this edition, we delve into the remarkable ratio of threat and praise in the arena of small commercial coverage. Assessing Small Business Risks Identifying Potential Risks Step one in designing a solid coverage strategy is knowing the unique risks that your enterprise faces. Capability threats facing small groups range from damage to assets to claims for legal responsibility. For instance, a restaurant might further face slip-and-fall accidents, while a tech startup can be at risk of data breaches. Analyzing The Impact Of Risks These risks may have an excessive impact on the financial stability of your commercial enterprise. Take for instance a boutique retail store that is going through a flood, which destroys its stock and disrupts its operations. Without proper coverage coverage, the consequences can be economically catastrophic, perhaps leading to shutdowns. Types Of Small Business Insurance General Liability Insurance General legal responsibility insurance serves as a foundational shield in opposition to diverse risks. It presents coverage for bodily injury and property harm claims, protecting your enterprise from capacity proceedings. Whether a consumer slips on wet ground or there is damage because of your products, trendy legal responsibility coverage is a critical thing of a complete threat management method. Property Insurance Property insurance safeguards your physical assets, such as homes, equipment, and stock. Small corporations invest considerably in those properties, and unforeseen occasions like fires, theft, or herbal screw-ups can pose a great hazard. Property insurance guarantees that the financial burden of such events is alleviated, making an allowance for a fast restoration. Business Interruption Insurance Business interruption insurance is an insurance policy that helps reduce the financial effect of those disrupting your business activities. Be it some natural tragedy or abrupt cases such as pandemics, this policy compensates income loss for your business and helps you to stay financially afloat during these hard periods. Customizing Insurance Coverage Tailoring Policies To Business Needs Every small commercial enterprise is particular, and so are its dangers. Working with insurance vendors, together with Nation North Insurance, to customize insurance guarantees that your precise desires are addressed. Whether you operate in an excessive-legal responsibility enterprise or face specific dangers, tailoring rules to your business's wishes is a proactive step closer to complete safety. Understanding Policy Exclusions While customizing coverage, it is crucial to apprehend policy exclusions. Examining common exclusions allows discover ability gaps in insurance that may leave your enterprise vulnerable. Nation North Insurance, with its knowledge of small business coverage, can guide you through the intricacies of coverage terms and exclusions. Cost-Benefit Analysis Of Small Business Insurance Weighing The Costs Of Insurance Premiums Investing in insurance comes with an economic cost, but the benefits often outweigh the rates paid. When considering coverage, it is crucial to weigh the fees towards the potential risks. While the upfront costs may additionally seem enormous, the lengthy-term financial savings and safety provided by way of coverage offer a precious return on funding. Quantifying The Value Of Peace Of Mind Beyond the economic components, small business insurance contributes to the intangible yet helpful asset of peace of thought. Knowing that your commercial enterprise is included in opposition to unforeseen occasions allows you to recognize growth and success. The experience of safety provided via insurance is a key element in navigating the demanding situations of entrepreneurship. Risk Management Strategies Implementing Proactive Risk Mitigation In addition to insurance, small agencies can implement proactive change mitigation strategies. This consists of employee education, protection protocols, and measures to save you from common dangers. By being proactive, agencies can lessen the chance of incidents that can cause insurance claims. Establishing Emergency Preparedness Creating a contingency plan for sudden occasions is a crucial issue of hazard control. Small corporations ought to establish emergency preparedness protocols that define steps to be taken on the occasion of a disaster. Collaboration with insurance vendors can assist in developing powerful emergency plans. The Role Of Professional Advice Consulting With Insurance Experts Navigating the complexities of small business coverage requires expert steering. Consulting with skilled insurance experts, like the ones at Nation North Insurance, guarantees that you make well-informed selections. Their knowledge lets you understand the nuances of policies, pick the proper coverage, and cope with any concerns particular to your enterprise. Conclusion In the intricate sport of small commercial enterprise, studying the dynamics of hazard and praise is paramount. Small business coverage, with its tailor-made insurance and protection, serves as a strategic device for ensuring lasting peace of thoughts. By assessing dangers, customizing coverage, and weighing the expenses against the benefits, businesses can navigate the challenges with self-assurance. For complete small commercial enterprise coverage solutions, bear in mind partnering with Nation North Insurance – your relied-on ally in the pursuit of chance mitigation and long-term fulfillment. Read More: Malpractice Vs Negligence – Let’s Find Out The Difference Is Startup Business Insurance Necessary For New Businesses? What Is Commercial Insurance? And Its Different Types – Let’s Discuss
Jan 11, 2024