How To Get Personal Loan On Bajaj Markets

Bajaj Markets is one of the best loan providers in India. They are also known as Bajaj FinServ Markets. One of the best things about Bajaj Markets is that you will have the option to get a personal loan for yourself completely online. You will get access to some of the best lending partners in India once you connect with Bajaj Markets.
In this article, you will basically get to know about the ways in which you can avail of Bajaj Finance personal loans from Bajaj Markets. Furthermore, you will also know in brief about how the Bajaj marketplace works in providing you with personal loans. Apart from that, you will also know about how to get loans from Bajaj Auto Finance if you are looking to spend on a two-wheeler.
What Are The Benefits Of Personal Loans From Bajaj Markets?

The following are some of the major benefits of availing of a Bajaj Finance personal loan from Bajaj Markets:
- You will not need to keep any collateral to avail of the loan.
- The repayment tenure of the loan is fully flexible, and you will get a repayment period of up to 60 months.
- At the start, you will need to pay up to 45% less EMI for the loans.
- There are no added or hidden charges. The charges are fully kept transparent.
- The interest rates for availing of Bajaj Finance personal loans from Bajaj Markets start from 13.5%, which is very competitive in the current financial market.
Bajaj Markets: Personal Loan Charges And Interest Rates
No matter where you take personal loans from, there are always some associated loan charges and interest rates. Once you take your loans from Bajaj Markets, you will be benefitted in the way that the loan charges and interest rates are quite low and reasonable. Furthermore, the process is simple and hassle-free.
The following points are the interest rates and charges associated with Bajaj Markets personal loan:
| Types Of Charges And Rates | Rates |
| Rate of Interest | ➼ 13.5% per annum onwards |
| Penal Interest Rate | ➼ Between 2%-4% per month |
| Part-Prepayment Charges | ➼ 2% of the amount being prepaid + GST |
| Loan Foreclosure Charges | ➼ 4% of the outstanding amount + GST |
| Check Bounce Charges | ➼ Between ₹600-₹1,200 |
| Mandate Rejection Charges | ➼ ₹450 |
| Stamp Duty | ➼ Dependent on the State of residence |
Bajaj Markets: Eligibility Criteria Of Bajaj Finance Personal Loan
If you want to avail of Bajaj Finance personal loans from Bajaj Markets, you will need to qualify for the eligibility criteria of the loan offerings. The following are the eligibility criteria:
- The borrower of the loan must be an Indian citizen.
- The borrower must be a salaried individual.
- The age of the borrower must be between 25 years and 67 years.
- The borrower must be an employee of a private firm, a public company, or a reputed MNC.
- The minimum earning of the individual must be at least INR 22K.
- The individual must have a CIBIL score of at least 750.
How To Apply For Bajaj Finance Personal Loan From Bajaj Markets?

There are many ways with which you can apply for Bajaj Finance personal loan. However, with the help of Bajaj Markets, you can apply for Bajaj Finance personal loan easily. Here are some of the steps that you will need to follow:
Step 1: You will need to visit the personal loans section on the Bajaj FinServ Markets website. Alternatively, you can click on the link below:
Step 2: On the webpage, you will need to provide your mobile number and date of birth. Once your identity and age are approved, you will get access to the loan application form.
Step 3: On the loan application form, you will need to provide details and the reason for availing of the loan.
Step 4: Once you hit the submit button on another page, you will need to fill up your official details. Furthermore, you will need to upload all your documents in the form, as per the instructions. After you have uploaded the documents, the application process will be complete. In most cases, the documents will be your Aadhar Card, PAN card, and bank statements for the last three months.
Step 5: After you have completed the application process, you will need to wait for up to 24 hours for the approval of the loan. Your loan will get approved after the loan-provider checks and verifies your reason for availing loan, as well as the documents.
How To Apply For Bajaj Auto Finance Two Wheeler Loan?
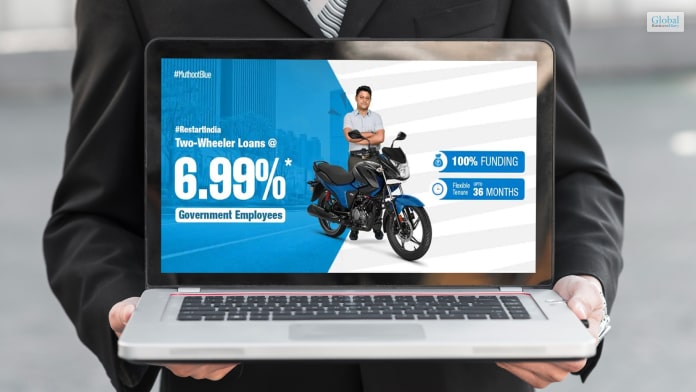
If you want a loan for your two-wheeler, applying it on Bajaj Auto Finance is the best thing you can do. This is because getting a loan is not only simple but also hassle-free. Once you follow the steps given below, it will be really easy for you to get a two-wheeler loan from Bajaj Auto Finance:
Step 1: Go to the Bajaj Markets website and then to the Automobile Loan Application Page. Alternatively, you can click on this link:
Step 2: To verify your identity and age, you will need to enter your mobile number and date at the start.
Step 3: You will get an online application form, where you will need to enter all required information, including the brand name, model, and making of the bike.
Step 4: On the page, you will then need to provide the required documents as per the instructions you have read before. Once you upload your documents, only then will you be able to complete the application process.
Step 5: Once you have completed the application process, you will need to wait for approval. The approval may take up to 24 hours. Once the loan provider verifies and approves your documents, only then will you be able to take the loan.
Summing Up
Hope this article was helpful enough in providing you with a better idea of how to apply for personal loans and how to get personal loans from Bajaj Markets. Furthermore, we also helped you in knowing how to get a Bajaj Auto Finance loan for two-wheelers. We have also covered the associated benefits of personal loans from Bajaj Markets. Do you have any more information to provide regarding Bajaj Markets personal loans? Feel free to share in the comments section below.
Have A Look :-
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
The Importance Of Saving For That Rainy Day That Will Come
It is likely that your parents and your grandparents have always told you to make sure that you put aside money. Who knows, the rainy days might definitely come along! We never know what is happening around the next corner. So it makes perfect sense that you would have money put away for such an emergency. Yes,saving money is important. Many different things can happen to you tomorrow, like losing the job that you have had for many years. The business wants to cut back, and they have a policy of last in, first out. Also, there might be some kind of medical emergency that may not affect you directly. But a family member may need money quickly to get the help that they need. It could be the simple things like the family car having major mechanical difficulties. So you need to get your hands on your savings as quickly as possible for your kids. This is why you need to seriously look into bank term deposits that offer you an excellent rate of interest over certain periods. Besides, it gives you peace of mind knowing that there is money there should you need it in an emergency. The following are just some reasons why it is so important to put aside money for a rainy day. Exigency in life may happen to us all at some point. Why It Is Important To Put Aside Money As we mentioned above, life is full of uncertainty. The ebb and flow of life ask you to spend beyond your planning. It is common in every individual’s life. That time you may need some money from your bank account. It denotes you ensure that you are getting it all in the form of your savings. Therefore, let's understand why you need to cut money from your earnings and look for savings. It Lowers Your Stress Levels As the head of the household, you have many things to worry about every single day your kid’s education and putting food on the table. Life does throw some curveballs at us from time to time. If you are not confident in your ability to be able to pay for any financial crisis that comes along, that is going to drive your stress levels through the roof. Hence you need to develop the habit of saving so that thig are manageable with time. Being properly prepared and knowing that you have money deposited in a bank earning a consistent interest rate helps you to deal with life’s issues. It Controls You’re Spending We all have a bad habit here in Australia: if we have money on the hip, we want to spend it because it is burning a hole in our pockets. It’s better to put this money away in a term deposit so that you are not tempted to spend it on silly things like a large-screen television or some kind of games console. Once it is out of your immediate reach, it’s more likely that you will leave it where it is, and this allows you to save and not to spend. Once you know that there is money available to you at any time, then it removes the pressure to want to borrow money at extortionately high-interest rates and then be unable to pay it back. There will also be fees incurred and penalties if you miss any of your payments, so having money tucked away in the bank makes so much more financial sense. Limits Your Debts As mentioned below, if you are in front of a situation where you have to spend your funds. Now, if you do not have a sufficient balance, you will have no other way but to go for loans. These exigencies are some things that you cannot avoid. Therefore you need to have the extra protection or, say, cushioning in the form of savings. It can help you meet your needs. Help Prepare For Retirement When you commence your habit of saving, it will go on to help you in the long run. Remember, you won’t be able to work any further in your old age. You may be under the state pension. Even it may turn out to be insufficient. It may not help you with the adequate support that you need. Therefore it is high time that you create a habit of saving your money right from a young age. This habit can help you get the best that you need. Hence develop the habit of saving right from a young age. It will assist you with an adequate amount. Ultimately you have a much more comfortable retirement. Advantage Of Saving For The Rainy Day When you develop a saving habit, you will certainly reap the advantages. Firstly you will find yourself saved from financial bondage, especially during the time when you do not have much to spend. With the help of financial independence, you can easily meet your expenses. Only and only with savings will you be able to own important infrastructure like homes, cars, education, training, and other aspects of your life? Hence, develop a habit of putting aside some of your funds. It denotes you can ward off debts when things become difficult with time. Life is not all about relentless struggles and hardships but also about spending money on happy moments. For instance, visiting a restaurant, pubs, going on a foreign trip, or spending valuable time with your friends and others. If you plan such things and moments of enjoyment, you must not recoil but live life to the fullest. Conclusion Saving from your regular expenditure is a great way to secure the future. It constantly motivates you to secure your life and meet emergency needs. At the same time, you must develop the habit so that your tomorrow and save be safe in the future. Be it a sunny day or a rainy day, you must go on saving for a brighter tomorrow. Read Also: a brief guide to business integrated planning maximizing tax refunds: tips and tricks for Canadians
Aug 07, 2023

Top 10 Effective Applications of AI in Fintech
AI in fintech has leveraged more value for customers in the financial services industry than anything else. It made transactions safer and more accessible. At the same time, it plays a crucial role in improving the speed, efficiency, and stability of any transactions. Financial technology, or FinTech, is an innovation in financial services. It aims to develop new ways of providing financial services. Moreover, it improves the channels of service delivery. Importance of AI in FinTech We see AI growing prominently across all industries. Above all, the AI market was valued at USD 2,575.16 Billion in 2023. AI encompasses 36.84% of the technology market's share in Northern America. Such exponential growth has impacted the FinTech industry in a big way. AI can impact the FinTech industry in aplenty ways. To speak of some, fraud detection, credit risk protection, and accurate revenue forecasting are the ones to begin with. Overview of AI Applications in the Financial Industry In this article, we will explore some critical AI features. Features like data analytics, predictions, forecasting, data retrieval, performance measurement, and real-time calculations are most effective in FinTech. Role of AI in the FinTech Industry There are many aspects of the Fintech industry, heavily influenced by AI and its many applications. AI in fintech is the driving force shaping the future of our transactions. Enhancing Analytics and Predictions Data process is a leading role of AI in fintech. AI can process 10 billion transaction messages and instructions every day. It is enough to show the data processing abilities of AI. What's better than data processing? Real-time data analytics. It is one of the other efficient features of AI in fintech. Data analytics helps financial companies identify potential risks, guide better investments, and personalize their financial services. RBC, Deutsche Bank, JP Morgan, and others actively use AI-based data mining services to improve customer response feed and service delivery. Improving Customer Support Through Virtual Assistants and Chatbots Chatbots and virtual assistants can give customers round-the-clock services without manual interference. Chatbots can resolve multiple customers' queries. They can also resolve customers' issues as well. Providing Personalized Recommendations Based on Customer Preferences Most AI can track data sets from feasible sources. For instance, AI studies the unique needs and aspirations of a customer. After that, it can send tailored recommendations to the customer. Experts say that personalized marketing is paramount for customer loyalty. In the US, Wells Fargo's predictive banking is quite popular. The bank uses AI for the same benefits discussed above. At the same time, Bank of America uses its AI-powered virtual assistant, Erica, to do the same. Handling High Volumes of Customer Inquiries Simultaneously Chatbots have simplified banking in the US. As new financial services are added to the FinTech sector, AI in fintech is becoming more meaningful. Chatbots can efficiently work 24x7 to process customer inquiries through AI's natural language processing feature. No human intervention is required. It is only an algorithm. So it can run simultaneously on all devices. Evolution of FinTech FinTech has evolved to teach more new services in its repertoire. Its evolution is also linked with the faster movement of money. Growth of FinTech services As we see, most banks and NBFCs use AI in FinTech. As a result, FinTech can provide many unique and much-needed services. For instance, retail credit card services peaked after the inclusion of AI in the US FinTech sector. At the same time, services like online portfolio management, online budgeting, peer-to-peer lending, and other services are also new. Disruption of Traditional Banking by FinTech The incumbent traditional banks are challenged by the disruptive growth of AI in FinTech. Neobanks challenge traditional banks by combining AI and fintech. The neobanks can overcome territorial limitations and provide services 24x7 using AI's NLP and blockchain protection methods. Impact of AI on Job Roles in the Financial Industry Yael Malek from Bluevine said that AI can account for several job losses. However, experts also feel that AI can leverage the working potential of humans in the FinTech sector. On the one hand, AI can perform more methodized and recurring or repeated tasks like answering customer queries. A data set of customer queries over a given timeframe from the same customer demographics, receiving similar services will include almost the same and repeating queries. AI can easily track the pattern in their queries and use modeled replies to satisfy them. So, the human workforce can focus on analytical and strategic roles. For instance, data analytics experts can scan the customer query database to find unique questions. If AI cannot answer those convincingly, new algorithm changes will be needed. So, AI will also lead to the creation of many new jobs. The job dynamics will change, though. Blockchain Technology Bettina Warburg feels that blockchain is a "decentralized database that stores a registry of assets and transactions across a peer-to-peer network." Potential of Blockchain in Transforming Financial Transactions A blockchain creates an open field within an encrypted pathway for financial transactions. You can think of it as a free-flowing pipeline with 0 or minimal obstructions. However, the pipeline is leak-proof. That's how blockchain funnels all financial transactions that use it. So, what happens? The transactions are safer than before. No hackers can infiltrate the firewall of the blockchain. At the same time, the transactions are faster as they occur peer to peer, directly. Role of AI in Optimizing Blockchain Systems AI performs an essential role in blockchain. It analyzes the programming and functioning of the blockchain's network. After that, it can recommend improvements and identify its inefficiencies. Ways AI is Transforming FinTech Companies AI plays a crucial role in the new and innovative FinTech services offered. 1. Instantaneous Financial Services One of the phenomenal examples of instantaneous services is the chatbot-based customer replies. Most of them use AI algorithms. AIs like ChatGPT can extract information from the internet and use neural learning to create human-like responses. So, it can process and answer all your financial queries in seconds. 2. Online Retail Banking Experts say that AI fintech is the basis of online retail banking services. AI can automate most retail banking services through chatbots. It can also detect fraud easily. At the same time, customers can get personalized investment suggestions using AI for fintech. 3. Investments and Trading Traders can use AI tools like stock screening to manage and improve portfolios. AI and fintech can work together to perform better asset allocation, analysis of individual stock performance and diversify trading portfolios. 4. Peer-to-peer Lending AI can derive data from the bank's databases to create secure and direct transaction channels. Hence, peer-to-peer lending has become faster and safer. 5. Financial Advisory Services AI can customize your risk tolerance and financial habits to recommend the best investment, savings, and general banking suggestions. 6. Portfolio Management AI can screen top-performing stocks across multiple sectors to diversify your portfolio. It may also assess the asset value of individual stocks to find the best growth stocks. 7. Budgeting Tools AI can detect contingent and recurring costs of a fintech company. Eventually, it can also automate most services to cut down costs. In the same way, your bank's AI can analyze your spending and banking habits to create tailored budgets. Challenges and Limitations of AI in FinTech AI is a disruptive yet emerging technology. So, it is bound to have flaws. Need for Skilled AI Developers The US has only 150000 ML engineers. However, there is a gap of 27 million AI engineers, programmers, and developers in the US. It's undoubtedly a big challenge that the American fintech sector also faces. Integration of AI Technologies in Compliance with Legal Standards There is no comprehensive regulation to directly track and monitor the use and applications of AI in the US. At the same time, case law suggests that AI-generated outputs cannot be the sole basis of operations in any sector. The same applies to the fintech sector. There may be bugs in the AI algorithms. Potential Shifts in the Financial Industry Due to AI Advancements AI has incorporated a new genre of financial services. For instance, AI introduced algorithmic trading in the US. However, bugs in algorithms can disrupt financial decisions. Conclusion There are many cases of AI being used in fintech. On one hand, it has become the guardian of financial fraud detection. On the other hand, it created new avenues of data processing. So, you may see more automation due to AI in the following time. AI also plays a crucial role in managing personal finances. The online banking services of emerging fintech includes AI. So, most of us use AI suggestions in our banking decisions. AI will also play a more strategic role in making key business decisions. However, the US needs more capable AI developers and programmers to make AI inclusion more competent and risk-free. For More Informative Business Articles Click Below!! How To Use AI Investing In Your Portfolio? AI for finance and Financial Markets: Let’s Explore What Is Market Sentiment Analysis in The Share Market?
Jun 20, 2024
8 Ways To Prepare For Your Retirement
As we all dream about the golden years of retirement, it's crucial to remember that careful planning is the key to a worry-free and enjoyable post-work life. Did you know that the average life expectancy has reached 72 years globally, according to the World Bank? This means people now have more time to cherish their retirement years, but it also highlights the need for a solid financial strategy to maintain a comfortable lifestyle. This article will explore nine essential steps to help you prepare for your retirement. From crafting a budget to fine-tuning your investment portfolio, these practical tips will enable you to embrace your golden years with confidence and tranquility. Assess Your Retirement Needs The first step towards successful retirement planning involves getting a clear picture of your financial needs. Start by estimating your future expenses, considering essential aspects such as housing, healthcare, and recreational pursuits. Online calculators can be invaluable tools for projecting the income necessary to sustain your preferred lifestyle and helping you pinpoint ideal retirement savings wealth management goals. By taking the time to assess your individual retirement needs, you can make informed decisions that will contribute to a secure and comfortable future, allowing you to truly enjoy your well-deserved golden years. Invest In Tax-Free Retirement Accounts Saving for retirement can sometimes feel overwhelming, but with the right approach, it's easier than you think. One smart strategy is to invest in tax-free retirement accounts, which can help you boost your savings. Options like Roth IRAs offer a fantastic opportunity for your investments to flourish tax-free, ultimately enhancing your long-term gains. By carefully selecting tax-advantaged financial instruments, you can keep a larger portion of your hard-earned wealth to relish during your retirement years. Remember, every dollar saved on taxes is a dollar that can help you enjoy the lifestyle you've always envisioned, so make the most of these tax-free opportunities. Diversify Your Investment Portfolio Building a diverse investment portfolio is essential in managing risk and enhancing returns during your journey toward retirement. By spreading your investments among different asset classes—such as stocks, bonds, and real estate—you can achieve a more balanced mix that safeguards your financial future. It's important to regularly evaluate and fine-tune your portfolio, ensuring that it aligns with your preferred level of diversification and risk tolerance. By taking a proactive approach toward managing your investments, you'll be better prepared to weather any financial storm. Pay Off High-Interest Debts Before you enter the realm of retirement, it's vital to tackle high-interest debts that can eat away at your income and limit your ability to save and invest. Prioritize clearing credit card balances, personal loans, and other high-interest liabilities as soon as possible. By doing so, you'll not only strengthen your financial standing but also alleviate the stress that often accompanies mounting debts. Developing a plan to systematically pay off these obligations can help you stay on track and remain motivated. Consider strategies such as the debt avalanche method, where you focus on the debt with the highest interest rate first, or the debt snowball method, where you target the smallest debt first to build momentum. As you head towards your well-earned retirement, being debt-free will allow you to fully enjoy your golden years without the burden of financial obligations looming over you. Plan For Healthcare Expenses As you look forward to your retirement years, it's essential to consider healthcare expenses, which can often become a considerable financial burden. Start by exploring Medicare coverage options and evaluating whether you might need supplemental insurance to bridge any coverage gaps. Remember, it's always better to be prepared than to face unforeseen medical costs without a safety net. To further safeguard your financial well-being, consider setting up a health savings account (HSA) that allows for tax-free withdrawals to cover qualified medical expenses. By planning ahead and allocating funds for healthcare, you can have the peace of mind that you'll be well-equipped to handle any health-related expenses during your retirement. Maximize Social Security Benefits Optimizing your social security benefits is a crucial aspect of retirement planning, as it can make a substantial difference in your overall income during your golden years. By delaying your benefits until you reach full retirement age or even later, you can secure higher monthly payments, providing you with a more stable financial foundation. When determining the best time to claim your benefits, take into account factors such as your health, life expectancy, and financial requirements. Weighing these considerations carefully will help you make an informed decision that aligns with your unique circumstances and long-term goals. Maintain An Emergency Fund Establishing an emergency fund is an invaluable way to ensure financial stability during your retirement years. Strive to accumulate a reserve equal to three to six months' worth of living expenses, stored in a liquid account that's easily accessible when needed. This safety net will enable you to address unforeseen expenses, such as home maintenance or medical bills, without tapping into your retirement savings. By building and maintaining this emergency fund, you'll have the peace of mind that comes with knowing you're prepared for life's unexpected twists and turns. This financial cushion can help you weather any financial storm and preserve your hard-earned retirement nest egg, allowing you to fully enjoy your golden years with confidence and serenity. Stay Informed And Adapt Remember, retirement planning is a dynamic process that demands continuous attention and fine-tuning. Staying informed about changes in tax regulations, new investment opportunities, and economic shifts is essential to maintaining a successful retirement strategy. Regularly reassess your plan, taking into account any relevant developments, and make the necessary adjustments to stay on course for a secure and rewarding retirement. By adopting a proactive approach and adapting to the ever-changing financial landscape, you'll be better equipped to handle any challenges that may arise. This ongoing vigilance will help you preserve your financial well-being and ensure that your retirement years are as enjoyable and fulfilling as you've always imagined. Conclusion Embracing these eight practical steps will pave the way for a financially secure and fulfilling retirement. As you embark on this exciting new chapter in your life, you can do so with confidence, knowing that you've taken the necessary precautions to safeguard your financial future. Remember, thorough preparation is key to enjoying your golden years with the peace of mind you deserve. Read Also: A Brief Guide To Business Integrated Planning Maximizing Tax Refunds: Tips And Tricks For Canadians Seven Potential Tax Credits Available To Small Businesses In 2023
Apr 27, 2023
Family Budgeting 101: Tools And Tips For Managing Household Finances
If you’re the breadwinner, you’re likely very well aware of the financial challenges of raising a family. From staying on top of bills to keeping your kids healthy and happy, there’s a constant push-and-pull of financial responsibilities that requires constant analysis on your part to resolve. In some cases, it can feel all too easy to just buckle down and fall behind financially. However, formulating a foolproof family budgeting strategy is indeed a possibility, regardless of how your finances currently stand at present. This can come in various forms, from cutting down on unnecessary costs to using tools to help break down your household’s cash flow. Here are some tools and tips to help you manage your household finances more effectively. 1. Track your budget If you don’t have a budget tracker for your household, prioritize creating one as soon as you can. A financial tracker is one of the easiest ways to get a good look at your finances, whether it’s your income or bills. This is not only useful in a corporate-level setting, but it’s also helpful for households in monitoring their cash movements. Some trackers even enable users to create financial ratios to help provide them with a clearer picture of their financial standing. For instance, some trackers have an emergency fund ratio, a ratio that measures how easy it is for liquid assets to be converted to cash in a pinch. There’s also a savings rate, which is a percentage of how much money you saved over how much you spent on a given period, typically a month. More often than not, budget trackers are used for the simple stuff, namely, inputting your income and expenses. Forming a habit of updating your budget helps keep you mindful of your spending patterns, which can help you make more informed decisions for future spending. 2. Utilise digital tools Technology has seeped its way into every corner of daily life, and in the realm of financial tracking, this is no different. In fact, many software tools and applications today can streamline the budgeting and tracking process, turning what may be minutes or hours of mind-numbing work into mere seconds of computerized processing. This calculator from Westpac is one such tool, among many other budget calculators, that can help you crunch data and project how much money you’ll need before you reach a financial benchmark. Furthermore, some tools can help keep you informed and notified about any issues related to your finances. For instance, some apps can remind you when your latest bills are due. Other apps can also provide an easy-to-read graph of your expense breakdown. Budgeting is a comprehensive activity that involves a lot of moving parts. There’s bound to be a digital app or extension that helps make that one budgeting process much easier and more approachable. Some good budgeting apps to help start you off include Mint, YNAB, and Quicken. 3. Set budget goals Every family has different budget goals that set them apart. Some families may be saving up for a new car, while other families are saving up to buy a new house. A few households may not have such grand purchases in mind and would rather climb out of a hole of debt. Having a goal is important because it gives you a target to aim for. The presence of this goal allows you to reverse engineer your decisions and strategize your financial behavior to actualize that goal. If the financial goal seems like a far-off fantasy, you can start breaking it down into smaller and more achievable chunks. You can establish figure-related milestones, like saving a certain amount each month or lowering your weekly expenditures. By having these short-term goals, you can find it easier to track your progress and adjust your purchase behaviour accordingly. 4. Pay off your debts immediately Financial management isn’t only about saving money and boosting your income—it also requires proper debt management. Debt, on its own, isn’t inherently bad. If you can guarantee that you can pay it on time, then having this infusion of funds in your hands can be used to pay off bills and other critical expenses. That said, having unpaid debt can be disastrous for your financial health. For instance, unpaid credit card and loan dues can incur high interest rates over time. Some loan types may also require borrowers to pay late fees for delayed payments. These can all add up, especially if you let the debt run for multiple months. So as soon as you earn income or receive money, be sure to pay off these debts immediately, starting with the debts that have been around the longest. 5. Uphold family financial values Family financial management is a team effort. You don’t want to be the only one restricting your spending while your spouse and/or children splurge for whatever they want, especially if they’re dependent on your income. As such, you should teach your kid key financial values as early as possible. Teach them the scarcity of money, the value of money, the importance of saving, the importance of holding off from wants, and other healthy money habits. You should also communicate finances with your spouse honestly and openly. Being on the same page is important for not just your financial health, but also your relationship at large. This can promote harmony and stability within the family unit, as well as foster the right foundation for proper money management. 6. Minimise unnecessary spending It’s crucial for all members of the family to commit to lowering their spending. Living below your means can seem tough, but it can be approached in several ways. For instance, instead of buying lunch in the cafeteria or at restaurants, just prepare a packed lunch from home. Also, avoid buying random snacks and drinks throughout the day. You should also look into your monthly subscriptions and see if there are any monthly payments you’re making that aren’t being used. Cancel these unused subscriptions, and urge your family to do the same. Furthermore, find ways you can lower your expenditure by buying things at lower rates. You can use discounts, coupons, and vouchers to lower the cost of products and services that you and your family need. Being proactive and scouring for these discounts through email newsletters or partnered websites can be a good way to score a good deal. 7. Be flexible Here’s a cold, hard truth: things will never always go as planned. Emergencies can and often will happen, and many of these emergencies are capable of wiping a significant portion of your savings away. As such, it’s important to develop contingency plans in your budget in case these events do occur. For starters, you can try to make an emergency fund as a financial cushion in case a sudden bad event happens. Besides that, always be mindful of your and your family’s lifestyle habits and make the necessary financial adjustments. If you find that your savings rate is decreasing month-on-month because of added expenses, for instance, you may have to think hard and reevaluate your budget’s goals. Being flexible is an important value to possess to be able to navigate financial difficulties effectively. Sticking with one goal stubbornly when the situation around you changes can spell your downfall, so be receptive to change and be prepared to call new shots. Read Also: A Brief Guide To Business Integrated Planning Maximizing Tax Refunds: Tips And Tricks For Canadians Seven Potential Tax Credits Available To Small Businesses In 2023
Dec 20, 2023