Credit Card Frauds and What You Can Do to Avoid Them
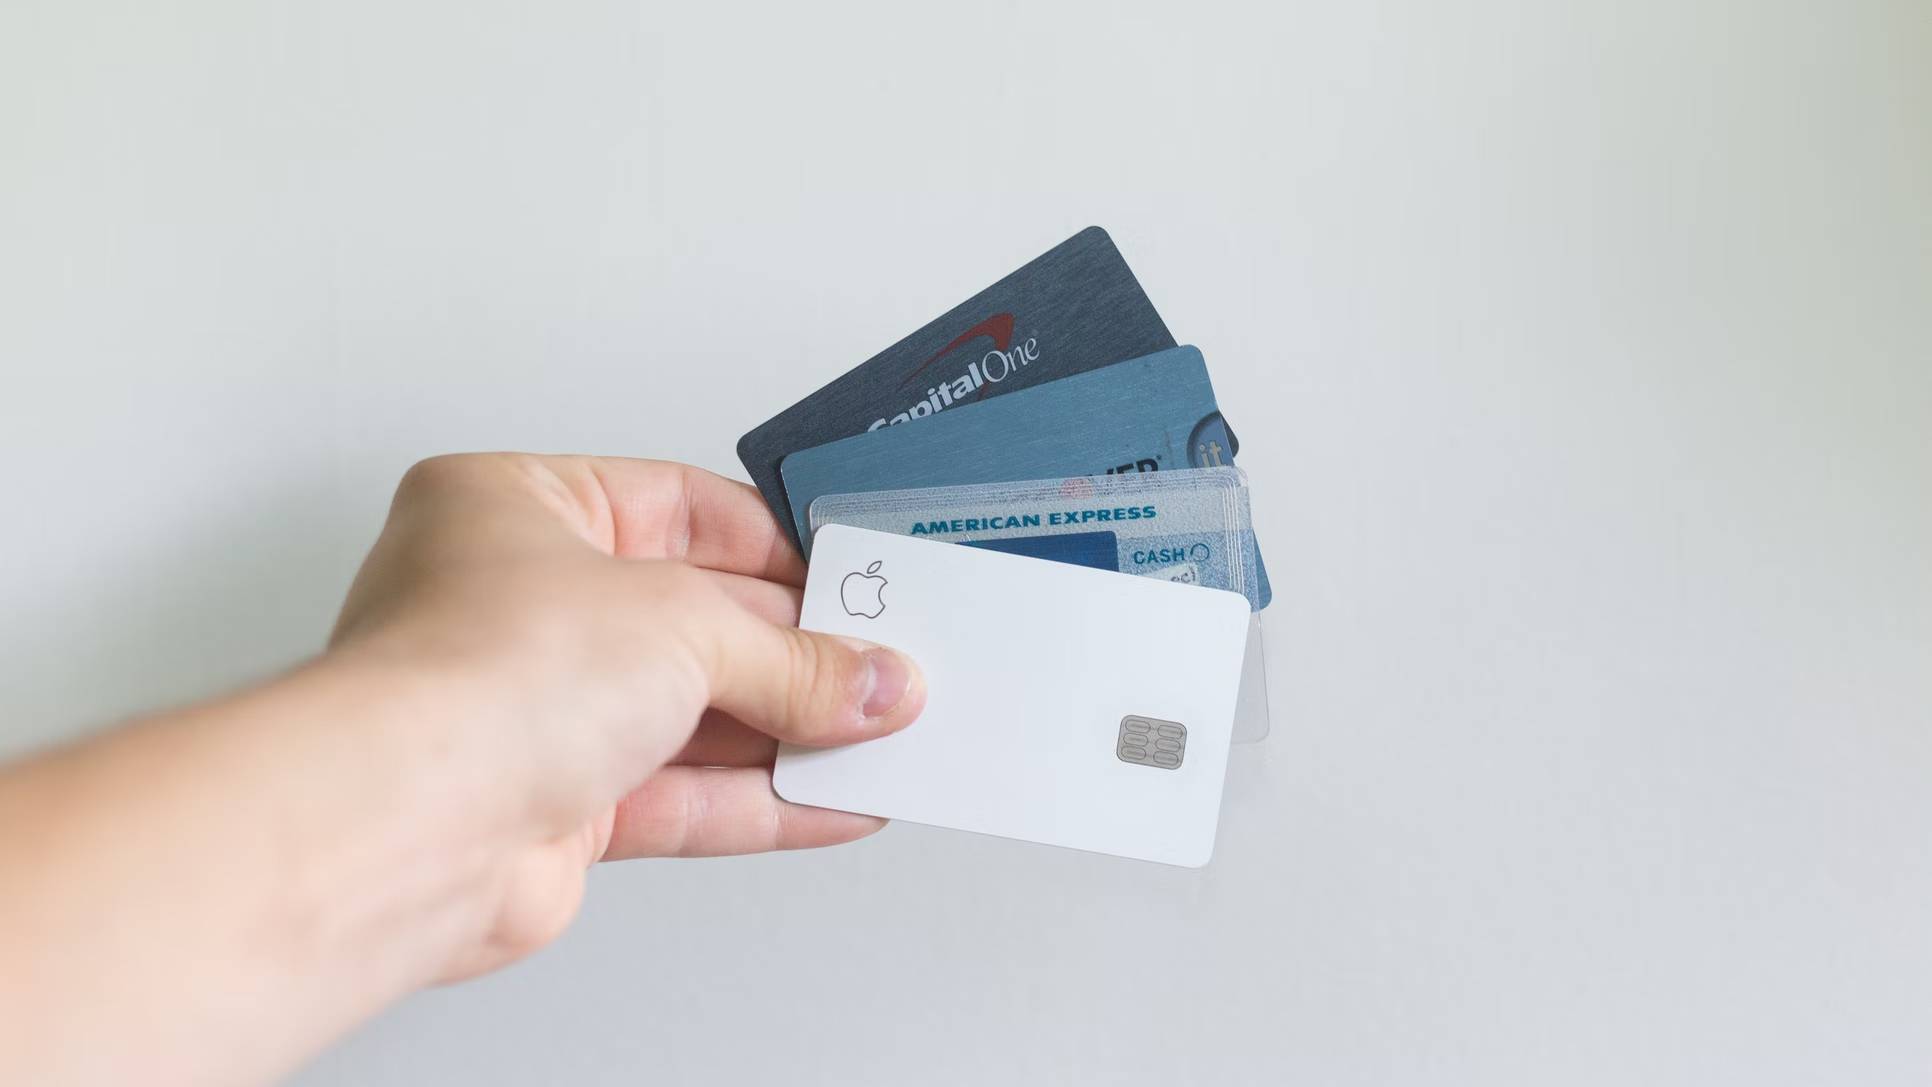
As of 2021, the most common payment method out of all the fraud reports in the US was credit cards. In 2020, when the world was battling COVID-19, there were a total of 459,297 cases of such fraud. Most of these fraud victims were between the ages of 30 and 39, the target demographic for credit card issuers. As a result, theft by credit card fraud increased by almost 45% compared to 2019.
Credit card fraud is one of the biggest threats today’s eCommerce industry faces. No one’s bank account is entirely safe from these perils, from credit card theft to credit card data breaches.
A card issuer does their best to stop offline and online transactions from a stolen credit card whenever they suspect fraud. It’s also possible to recover funds from credit card fraud via a funds recovery company. These companies can easily back you up as long as you have sufficient evidence. However, you to be vigilant as well regarding this issue. So, here are a few things you can do to avoid credit card fraud.
Never Save Your Credit Card Details
In 2021, Google sent millions of users a chilling email when it told them their passwords had been compromised. The data breach exposed millions of users’ saved login and payment credentials.
You often save your credit card information on various websites. The purpose is that you don’t have to re-enter the same details the next time you want to buy something from them. However, hackers can access your information when they manage to breach the website’s security measures. As a result, your credit card information is no longer safe. It might already be too late by the time you get to know it.
Scan Your Computer and Phone for Virus and Malware
The number of online transactions reaches the million mark almost every day. Most of these are credit card transactions, where people are buying stuff online. Since you’re either using your mobile or PC for this, you must make sure no one is snooping on you and your credit card information.
Scan your PC and smartphone for viruses and malware. Hackers and scammers can access confidential information on your devices by planting a backdoor. At the same time, you should be careful while installing third-party software on your devices.
Read : What Is Stockinvest? Is It Legit And Working In 2022?
Use Stronger and More Secure Security Measures
Not saving your login credentials and credit card information will go a long way in protecting you from fraud. However, you can still do more to protect yourself from credit card fraud.
Using a secure password should be your priority. Use a mix of alphabets, symbols, and special characters to compose the password. Never use guessable passwords like your birthdate or pet name.
Look into other ways of securing your devices. Biometric authentication is a highly efficient way of doing so. After all, it won’t be easy to replicate your eyes, face, or fingerprints.
Don’t Use Your Credit Card On an Insecure Website
Never purchase anything using your credit card on a website without an SSL certificate. The SSL certification verifies that the website encrypts sensitive information passed between the user and the server. No SSL certificate means that anyone can snoop on that information. When you wish to install an SSL certificate make sure it is from a reputed CA like RapidSSL, GlobalSign, DigiCert, etc. A few well-known certs are popular among developers including RapidSSL wildcard Certificate for subdomains, comodo multi domain SSL, and Thawte SSL for a single domain. A site owner can choose as per the site’s requirements.
When using your credit card online, you send your card number and security pin to the receiver’s server. Anyone with the right tools and brains can snoop on these exchanges and steal your credit card information. That is even worse than when someone steals your credit card. With credit card theft, you’ll at least know that someone stole it. There’s no easy way to tell if someone stole your credit card information during the transaction process.
Be Careful While Using Your Card
When using your credit card, keep the following points in mind.
- Make sure the card reader at the ATM is not loose.
- Cover your pin as you enter it into the machine.
- Never let anyone use your credit card. At the same time, never tell your credit card pin to those at the payment terminal or counter of the store.
- Immediately call your card issuer and block the card if you lose it.
Read more : PooCoin Stock Forecast: Everything You Should Know.
Be Aware of Unauthorized Transactions
Always keep your credit card bills in check. When you spot an unauthorized or suspicious transaction, notify the credit card company. Don’t risk keeping your card active at that stage.
Your credit card issuer will also notify you when it sees that you’re trying to make a transaction to a suspicious or blacklisted website. Listen to their reasons for the notification and possible transaction block. Avoid using your credit card on those sites if possible.
Credit card fraud will continue as long as people are not careful about how they use it. So, your best bet to avoid these frauds is to ensure you stay extra cautious all the time.
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
5 Most Common Human Errors In Crypto Accounting
Crypto accounting is a complex and challenging task that requires a deep understanding of how the emerging market of cryptocurrencies works. While traditional accounting is straightforward, experienced accountants struggle to comprehend how risk interplays with crypto's market and how underlying technologies protect investors. This makes it difficult for regulators to make informed decisions and entrepreneurs to manage risk in their projects. However, most of the challenges in crypto accounting arise from simple human errors, and everyone in the crypto world could use some help to manage their accounting better. One way to minimize these errors is by using crypto accounting software, which simplifies tracking and managing crypto transactions for individuals and businesses. 5 Common Mistakes to Avoid in Crypto Accounting 1. Incorrect Cost-Basis Calculations If you've engaged in crypto transactions, it's crucial to understand the impact they may have on your taxes. One common mistake to avoid is miscalculating your cost basis and capital gains. The cost basis is the total amount paid to acquire the crypto, including transaction fees, while capital gains refer to the proceeds from the sale minus the cost basis. To calculate the cost basis and capital gains, you'll need to use specific formulas. In a simple example, if you bought crypto for $10,000 (including $35 in transaction fees) and later sold it for $50,000, your capital gains would be $40,000 since you'll have to face a $10,000 fee. However, if you traded one crypto for another, such as selling bitcoin to purchase ether, this counts as two separate transactions, and the cost basis of your ETH would be the amount paid, including fees. It's essential to keep accurate records and avoid mistakes that could result in penalties or interest on underpaid taxes. 2. Incorrect Spreadsheet Formulas Even the most intelligent individuals can make simple errors, which can result in significant consequences. For example, TransAlta lost 10% of its annual profits due to a spreadsheet mistake. Although it is challenging to identify spreadsheet errors in traditional accounting, it is even more difficult in the world of crypto accounting, where the complexity of the data can make it difficult to recognize an error until it is too late. To avoid spreadsheet mistakes, it is crucial to be extremely careful when using spreadsheets and, if possible, utilize more advanced tools. Finding a platform or service where you can reconcile your calculations and results to ensure accuracy is also recommended. Reducing reliance on human accuracy can further help to avoid spreadsheet errors. By taking these measures, individuals can significantly reduce the chances of spreadsheet mistakes and their resulting consequences. 3. Uncategorized Transactions Keeping accurate records of financial transactions is essential for any business to succeed. However, categorizing these transactions systematically can be a challenge. A proper categorization system ensures that your bookkeeping is error-free and that you can easily identify similar transactions using categories or memos. Invoices must be correctly linked to transactions, and it is crucial to ensure that all events associated with a transaction are accounted for separately. Let's take the example of a Cardano transaction, which can trigger multiple events, including a transfer of Cardano, a gas fee paid to execute the transaction, and a gain/loss associated with the transaction. By accurately categorizing and reporting any losses associated with these transactions, you may be eligible for a tax write-off, or even minimize your crypto taxes which could save you money. Therefore, it is essential to have a robust categorization system in place to keep track of your finances and to make informed decisions that can benefit your business in the long run. 4. Susceptible Security Crypto accounting is crucial for companies handling crypto assets, but it can be tricky to navigate. One of the biggest challenges is avoiding common mistakes that can compromise the security of sensitive information. Human error is one of the biggest culprits, as employees may inadvertently click on unfamiliar links or enter personal information into fake accounts. To prevent these types of mistakes, it's important to implement best practices such as ensuring employees are properly trained on security protocols and regularly reminding them to remain vigilant. Additionally, utilizing secure networks and limiting access to sensitive information can help reduce the risk of cybercrime. By avoiding these common mistakes, companies can better protect their crypto assets and ensure their accounting practices remain secure. 5. Bad Calculations Based on Inaccurate Exchange Fees Crypto accounting can be a challenging task due to the complexities of the technology and the lack of standardization across different exchanges. One common mistake is relying on information from one exchange to make calculations about another, which can quickly lead to errors and require significant effort to correct. Additionally, manually calculating exchange fees can result in mistakes, so it's recommended to use automated tools to keep track of fees and calculations. With the help of technology, such as automated software, crypto accounting can be made more efficient and accurate. It's important to exercise caution and remain vigilant to avoid making mistakes in crypto accounting and maintain accurate records. Final Thoughts Crypto accounting can be a challenging task due to the unique characteristics of crypto, such as its cryptographic and anonymized nature. Even experts in traditional accounting may make basic mistakes when dealing with crypto accounting, especially when trying to navigate the additional complexities of crypto. The lack of established crypto accounting standards adds to the challenge as well. To ensure accuracy and efficiency in crypto accounting, it's important to exercise extreme caution and use specialized crypto accounting software that can help streamline the process. With the help of accounting software, companies can avoid common mistakes and keep their books organized and accurate. Read Also: How Blockchain Infrastructure Is Revolutionizing Businesses What You Need To Know About Software Testing In Blockchain ACTC Stock – Present Price, Forecast, Statistics – Should You Invest In It In 2022?
Mar 23, 2023

What Do the 2026 SALT, Senior Bonus, and Standard Deduction Changes Mean for Your Taxes?
In high-tax states, taxpayers have waited seven years for meaningful SALT relief. As of 2026, that wait ends now. This is due to the One Big Beautiful Bill Act. This act was signed into law in July 2025. It brings in the most significant overhaul to federal deductions in nearly a decade. Also, there are updated tax brackets, IRA limits, and 401(k) contribution caps. Basically, all these changes entirely reshape the outlook for 2026 wealth management. At the outset, homeowners, retirees, and middle-income earners stand to benefit. That part is clear enough. But it only works if the changes are understood properly and the positioning follows accordingly. Your State Tax Bill Finally Gets Federal Recognition Since 2018, homeowners in places like New York, California, and New Jersey have been dealing with the fallout. In fact, that was when the Tax Cuts and Jobs Act imposed the $10,000 SALT cap, which tightened things more than expected. That effectively penalized residents of high-tax states who previously deducted far more. Meanwhile, the new legislation quadruples that limit. The SALT deduction cap rises to $40,400 for 2026. Also, there are annual 1% increases through 2029. Consider a married couple in New Jersey. State income taxes are at $25,000, and property taxes are another $15,000. That totals $40,000, now fully deductible, which wasn’t the case earlier. Back then, the cap stopped everything at $10,000, cutting off the rest without much room to adjust. There’s a catch, though. High earners start losing the benefit. In 2026, the expanded cap phases down once income crosses $500,000. Around $600,000, it drops back to $10,000, almost like a reset. The provision isn’t permanent either. It sunsets in 2030 unless extended. All of this shifts the calculation. Itemizing starts to matter again, so revisiting earlier assumptions becomes necessary. A Fresh Tax Break Lands Exclusively for the 65-and-Over Crowd Retirees get the flashiest piece here. Maybe the most talked about, too. A new deduction shows up, $6,000 for those 65 and older. Married couples where both qualify can claim $12,000, which feels substantial at first glance, almost unusually generous. It doesn’t come alone. The deduction stacks, which is where things get interesting. Seniors already receive an extra standard deduction, $2,050 for single filers and $1,650 per qualifying spouse. Add the base deduction, and the numbers climb quickly. A single senior can shield $24,150. Joint filers, both over 65, can reach $47,500. The scale shifts quietly but significantly. Data from the White House Council of Economic Advisers suggests 88% of seniors receive Social Security benefits. That’s about 51.4 million people, a wide sweep, though outcomes will still vary. Of course, there are limits to this. In fact, the full deduction phases out above $75,000 for single filers. Meanwhile, for joint fillers, it is $150,000. Moreover, it disappears entirely at $175,000 and $250,000, respectively. Basically, that cutoff matters more than it first appears. One detail stands out. The deduction applies whether itemizing or not. That flexibility changes planning decisions. Seniors with medical expenses or charitable contributions still qualify, and the provision runs through 2028, leaving a narrow window to act. Small Gains Stack Up Over Time With inflation, the standard deduction goes upward for 2026. Although the shift isn’t dramatic, it is still there. Joint filers can claim $32,200, while singles get $16,100. Meanwhile, heads of household earn $24,150. These numbers might feel routine on paper, but they still matter. Individually, the increases seem minor. Easy to overlook, honestly. But they stack over time, slowly, almost quietly. Around 90% of taxpayers take the standard deduction, per IRS data. Over decades, these small adjustments start adding up, shaping outcomes more than expected. Why These Changes Demand a Longer View The first instinct is simple. Take the deduction, lock in the savings, move on. But that approach rarely holds up over time. Durable strategies need a slower, more deliberate kind of thinking. The interaction between provisions complicates things. A senior in a high-tax state now faces multiple pathways: the expanded SALT cap, the $6,000 bonus, and a higher standard deduction. The choice between itemizing and the standard deduction isn’t straightforward anymore. It carries more weight now. Nothing here is permanent. The SALT expansion sunsets in 2030. The senior bonus fades after 2028. Flexibility matters, maybe more than precision, especially with deadlines approaching. Q&A 1. Should I switch from the standard deduction to itemizing in 2026? It comes down to totals, really. Itemizable expenses, all of them together. SALT is now capped at $40,400, not the old $10,000, which changes the math quite a bit. Taxpayers in high-tax states need to recalculate.Itemizing starts to make more sense if the following factors exceed the standard deduction:1. State taxes2. Property taxes3. Mortgage interest4. Charitable contributions. 2. Can seniors who itemize still claim the new $6,000 deduction? Yes. This part stands out a bit. The senior bonus applies either way, itemizing or not. Retirees with high medical costs or charitable giving can claim both, which shifts the calculation slightly. 3. What happens when these provisions expire? When these provisions expire, the SALT cap reverts to $10,000 in 2030. The senior bonus ends after 2028. Building strategies that account for these sunsets makes more sense than assuming Congress will extend them. 4. How do these deductions interact with retirement planning? Timing matters more than it seems. Actually, deductions shift taxable income. This then nudges contribution limits and even Social Security thresholds. When planning connects across these areas, outcomes tend to improve. Read Also: What Is A Schedule 1 Tax Form? What Is Safe Harbor 401K? Benefits And Types Which Describes A Type Of Tax That Funds City Programs? – Let’s Find Out Seven Potential Tax Credits Available To Small Businesses Need Help with Tax Debt? Check Out These Relief Options
Mar 24, 2026
Coinbase: Essential Things To Know About This Fintech Company
Cryptocurrency creates economic freedom for the people so that they can participate fairly in the economy. Coinbase offers complete economic freedom for more than 1 billion people. They are offering a century-old financial system. Thus, it helps you in getting a trusted platform. It is easy for people and institutions to make it easy for the people as well as institutions. These are making engagement with people as well as the institutions. Thus, it includes trading, staking, spending, and safekeeping and offers fast free global transfers. Coinbase offers the critical infrastructure for all the on-chain activities and provides support for the builders who share a vision in the on-chain online. Additionally, it is one of the most popular global fintech companies whose services you can rely upon. What Are The Core Services Of Coinbase? Coinbase offers several core services to its clients and customers. This is one of the leading Fintech companies that can offer you absolute solutions within a specific time. You need to get things done in perfect order while meeting your requirements with absolute ease. Some of the key factors that you should know here are as follows:- 1. Buy & Sell Cryptocurrencies Users can buy and sell a variety of cryptocurrencies, including Bitcoin, Ethereum, and others, using fiat currency. It is one of the basic services that Coinbase offers to its clients. You need to be well aware of the situations to meet your goals. The future of money is revolving around Cryptocurrency. 2. Wallet Services Coinbase provides digital wallets for users to store their cryptocurrencies securely. Without knowing the reality, you cannot make things happen in your favor. Wallet services will offer you the best opportunity to keep your cryptocurrency safe with complete ease under certain measures. Although, it will help you in getting best wallet services. 3. Exchange Services The platform offers a trading platform where users can trade cryptocurrencies with each other. You can compare the prices as per your requirements within an estimated time frame. This will boost your chances of earning within a shorter span of time. 4. Conversion Services Users can convert one cryptocurrency into another using Coinbase's conversion services. Your business's conversion services will rise within a shorter time frame. Ensure that you follow the correct process from your counterpart. It will be easier for you to get more value for your money using their conversion services. 5. Merchant Services Coinbase provides services for merchants to accept cryptocurrency payments from customers. Seeking merchant services will make it easier for you to get things done in the correct order. This will assist you in meeting your goals with complete ease. Its services are similar to Stripe. 6. API Services Coinbase offers APIs for developers to integrate Coinbase services into their own applications. Applications of the API services will help your business to grow in the correct order. Try to follow the correct process that can make situations work for you in the right order. 7. Education Coinbase provides educational resources for users to learn about cryptocurrencies and Blockchain technology. This will help beginners in crypto trading gain valuable insights into the current market scenario. Try to follow the process that can assist you in making the best options work for you in the right sequence. What Type Of Solutions Coinbase Offers To Individuals There are several types of solutions Coinbase offers to individuals that you must be well aware of while attaining your requirements with ease. Some of the key services Coinbase offers to individuals are as follows:- 1. Cryptocurrency Buying & Selling Coinbase provides a user-friendly platform for buying and selling a variety of cryptocurrencies, including Bitcoin, Ethereum, and others, using fiat currency. You need to keep things in perfect order when you want to buy and sell Cryptocurrency within a specific time. 2. Digital Wallet Coinbase offers a digital wallet solution where users can securely store their cryptocurrencies. The wallet includes features like multi-factor authentication and insurance coverage. A digital wallet can offer you the chance to keep your Cryptocurrency in safe custody. 3. Recurring Buys Coinbase allows users to set up recurring purchases of cryptocurrencies, allowing them to invest in cryptocurrencies over time. Recurring buying of Cryptocurrencies will become possible for you if you make use of Coinbase platform for your Crytotrading. 4. Vault Coinbase offers a vault feature for storing large amounts of cryptocurrency securely. Thus, with additional security measures such as time-delayed withdrawals and multiple approval support. It can boost the chances of keeping your Cryptocurrency safe from the clutches of hackers. Thus, you can ensure risk-free Crypto trading options work perfectly well for you. 5. Crypto To Crypto Conversions Users can easily convert one cryptocurrency into another using Coinbase's conversion services. You can make crypto-to-crypto transactions very easily. Thus, it can make things work perfectly well in your favor. Ensure that you follow the correct solutions that can assist you in reaching your objectives with complete ease. 6. Earn Crypto Coinbase offers a program where users can earn cryptocurrencies by learning about them through educational content. Earning money using Crypto trading will become easier for you while you make use of this platform. 7. Staking Coinbase supports staking for certain cryptocurrencies, allowing users to earn rewards for participating in the network. Thus, only by participating can you earn the maximum rewards within a shorter version of time. It can boost the scope of your earnings to a greater level within a shorter version of time. 8. Crypto Debit Card Coinbase offers a debit card that allows users to spend their cryptocurrencies at merchants that accept Visa. The application of cryptocurrency can help you make use of debit cards that can assist you in reaching your goals. What Type Of Solutions Does Coinbase Offer To Businesses? Coinbase offers several types of solutions to many businesses. You need to be well aware of it while attaining your requirements with complete ease. Without knowing the facts, things can become more difficult for you in the long run. Some of the key facts that you should know at your end are as follows:- 1. Offering Merchant Solution Coinbase provides tools for businesses to accept cryptocurrency payments from customers. This includes payment buttons, invoices, and other payment solutions. Thus, you need to get through the details that can assist you in meeting your requirements with ease. Once you make things work perfectly in your way, it can become easier for you to attain your requirements with ease. Try to keep things in proper shape while attaining your requirements with ease. 2. Commerce Coinbase Commerce allows businesses to accept cryptocurrencies directly on their websites or in their brick-and-mortar stores. Thus, you can enjoy flexibility in the process of your transaction with complete ease. Commercial businesses can also seek the benefits from Coinbase platforms. You must take care of these facts while meeting your requirements. Ensure that you know the process from your end while applying for this cryptocurrency platform. 3. Custody Services Coinbase offers custody services for businesses looking to store large amounts of cryptocurrency securely. This includes cold storage solutions and insurance coverage. Make an application for custody services to meet your needs with ease. The custody services of these platforms can make it easier for you to keep your cryptocurrency in safe hands. Once, you follow the correct process things can become perfect for you in the long run. 4. Exchange Services Coinbase provides exchange services for businesses looking to trade cryptocurrencies. This includes access to a deep liquidity pool and competitive pricing. Thus, you can compare the rates that you need. Once it is done, your selection process ends here. No other platform will offer you such facilities as this app can deliver you. If you have a limited budget, then also you can make use of this platform to make the correct selection of Cryptocurrencies that suit your budget and can boost your earnings. 5. API Services Coinbase offers APIs for businesses to integrate cryptocurrency transactions into their own applications. This includes the ability to send, receive, and store cryptocurrencies programmatically. API services can offer you the chance to boost your transaction level to a greater extent. Without knowing these facts, things can turn worse for you in the long run. Try to make your selection and the choices on the correct end. 6. Institution Trading Coinbase offers trading services for institutional clients looking to trade large amounts of cryptocurrency. This includes access to OTC trading and advanced trading tools. Try to make your institution work in the correct order. Institution trading can help your business move in the correct direction that can allow you to reach your requirements with complete ease. Try to follow the best process that can assist you in getting the right solution within a shorter version of time. 7. Asset Management Coinbase offers asset management services for businesses looking to diversify their cryptocurrency holdings. This includes access to a range of cryptocurrencies and investment strategies. Once you make perfect asset management strategies, things can become easier for you to reach your goals with complete ease. Without knowing the applications of this app, things can become more complex for you in all possible ways. What Type Of Solutions Coinbase Offers To Developers Coinbase offers several types of solutions to its developers. You must be well aware of it before using this app. Let's find out some of the core solutions that it delivers to its developers. Coinbase provides a set of APIs that developers can use to integrate cryptocurrency buying, selling, and trading into their applications. This Fintech company offers wallet services that developers can use to build applications that securely store and manage cryptocurrencies. Coinbase Commerce provides tools for developers to integrate cryptocurrency payments into their websites and applications. It offers webhook notifications that developers can use to receive real-time updates on account activity and transactions. Additionally, it provides a range of developer tools, including SDKs, libraries, and documentation, to help developers build and deploy applications that interact with the Coinbase platform. Benefits Of Coinbase Services There are several benefits of the Coinbase services that you must know at your end while attaining your requirements with complete ease. Some of the key factors that you should know about it are as follows:- 1. It Offers User-Friendly Interface Coinbase provides a user-friendly platform that makes it easy for beginners to buy, sell, and store cryptocurrencies. You will get a user-friendly interface that can make things work in perfect order. Without knowing the reality, you cannot make things happen in your favor. 2. Offers Greater Security It offers greater security within the process of your transaction. Coinbase offers a high level of security, including insurance coverage for cryptocurrency stored on its platform. Along with it, you will get two-factor authentication for account protection. 3. Variety Of Cryptocurrencies Coinbase supports a wide range of cryptocurrencies, allowing users to diversify their holdings and invest in different assets. It delivers a variety of Cryptocurrencies that can boost the chances of your brand value to a greater level. You should make your choices in the perfect order while attaining your aims with complete ease. 4. Convenience This platform offers a range of services, including buying, selling, and storing cryptocurrencies, all in one platform, making it convenient for users. You will get a higher level of convenience while you make use of this platform. Ensure that you know the details of how to use this app with complete accuracy. 5. Educational Resources It provides educational resources to help users learn about cryptocurrencies and how to use them effectively. Educational resources will help you in meeting your goals with ease. Thus it can boost your brand value to a greater level. 6. Offers Better Integration Coinbase offers APIs and developer tools that allow developers to integrate cryptocurrency transactions into their own applications. It offers better integration with the Fintech companies to help you attain your requirements with complete ease. Career Opportunities Available In This Company There are several kinds of career opportunities available with this company. You need to be well aware of it while reaching your goals with ease. Some of the key factors that you should know here are as follows:- Business Development. Customer experience. Business Operations & Strategy. Design. Data Science. Backend Engineering. Data Engineering. Final Take Away Hence, if you want to make use of the Coinbase app, you will receive these kinds of facilities from their end. You must be well aware of these facts while you make use of the Coinbase apps for your business. You can share your views and comments in the comment box. This will help you in meeting your goals with complete ease. Without knowing the process, things can become difficult for you to handle in the long run. Coinbase is regulated in several jurisdictions, providing users with a level of trust and confidence in its services. It offers better integration with the Fintech companies to help you attain your requirements with complete ease. #Disclaimer: The information provided on this blog is for educational and informational purposes only and should not be construed as financial advice. I am not a licensed financial advisor. Any investment decision you make is at your own risk, and you should consult with a qualified financial advisor before making any investment decisions. This site may contain affiliate links, and I may earn a commission at no additional cost to you. Continue Reading: Chime Financials: Essential Things To Know About It Revolut Makes Your Financial Management Journey Easy Ant Group: A Leading Fintech Organization
Mar 06, 2024
Demystifying Common Misconceptions About Licensed Money Lenders
Financial service providers are very important to society because they help people and small businesses who might not have access to traditional ways of getting money. But there are many misconceptions regarding authorized money lenders, which may deter potential borrowers from employing this important tool. While making informed decisions about financial possibilities, it's essential to understand the truth behind these fallacies. In order to help you choose the best option for your financial needs, we want to clarify some common misconceptions and shed some light on how these lenders operate. Misconception 1: High-Interest Rates Charged by These Lenders A common misconception is that these financial service providers charge very high-interest rates that make it hard for borrowers to pay back their loans. In reality, licensed money lenders are regulated by the government, which sets limits on how much interest they can charge. This makes sure that people who need loans can get them at fair and reasonable rates. For example, many countries put limits on how much interest these lenders can charge. This keeps interest rates competitive and in line with market standards. Additionally, they often offer flexible repayment terms, allowing borrowers to choose suitable loan structures. In summary, while interest rates provided by these lenders may be slightly higher than those of traditional banks, they are not exorbitant. Rates are regulated to make sure that borrowers get fair terms and can get loans without having to pay unreasonable amounts. Misconception 2: Unethical Collection Practices by These Lenders Another misconception is that these financial service providers engage in unethical collection practices. But licensed money lenders have to follow strict rules about how they collect debts. This is to make sure they are following the law and being honest when they do so. When trying to get their money back, these lenders can't use threats, harassment, or violence. Violating these rules may result in severe penalties, including fines and license revocation. To protect borrowers further, regulatory bodies have established channels for reporting unethical behavior and holding lenders accountable for their actions. In conclusion, the misconception that these lenders engage in unethical collection practices is unfounded. Even though there are some unlicensed or dishonest lenders out there, most of them follow strict rules, treat their clients fairly, and follow the rules that have been set up. Misconception 3: Catering Only to High-Risk Borrowers A common misconception is that these financial service providers exclusively cater to high-risk borrowers rejected by traditional banks. In reality, licensed money lenders work with a wide variety of people and small businesses with different credit histories. These lenders consider factors like credit history, income, and repayment ability when approving loans. They may be more willing to work with borrowers with less-than-perfect credit scores or limited credit histories if they demonstrate a stable income source and repayment capacity. These lenders often offer financial products tailored to different needs, such as personal loans, business loans, and short-term loans. This gives them the ability to serve a wider range of customers and help borrowers get the money they need. In summary, the misconception that these lenders only serve high-risk borrowers is unfounded. They cater to a wide range of clients, offering flexible financial solutions to meet the unique needs of borrowers. Misconception 4: Complicated Application Processes with These Lenders People often think that applying to these financial service providers is hard and takes a long time. On the other hand, they often have simple and quick processes that make it easier for borrowers to get funds quickly. In most cases, the application process involves giving some basic personal and financial information, and then a quick check to see if the borrower is eligible. In many cases, loan approvals and disbursements can occur within a few hours or days, unlike traditional banks which may take weeks. Additionally, these lenders may have fewer requirements and more lenient eligibility criteria, making it easier for a wider range of borrowers to qualify for loans. This convenience and speed make them an attractive choice for those in need of immediate financial assistance. In conclusion, the misconception of a complex application process with these lenders is unfounded. Getting loans from them is often easier, faster, and more convenient than from traditional banks. Misconception 5: Negative Impact on Credit Score A misconception is that borrowing from these financial service providers negatively impacts your credit score. But if you borrow money from a licensed money lender in a responsible way, it can actually help your credit score. To build a good credit score, it's important to pay back loans on time and keep your debt-to-income ratio low. By borrowing and paying back loans from these lenders in a responsible way, borrowers can show that they are creditworthy, which could help their credit scores over time. In conclusion, it is a misconception that borrowing from these lenders hurts your credit score. When managed responsibly, it can be a viable way to build or improve your credit history. Related: Need Help with Tax Debt? Check Out These Relief Options Conclusion We have debunked common misconceptions about licensed money lenders, shedding light on their practices and benefits. By understanding the truth behind these misconceptions, borrowers can make informed decisions about their financing options. Explore licensed money lenders in your area and discover the financial solutions they offer to meet your unique needs. Read Also: Instant Loan App: Top 25 Best Loan Apps Should You Know In 2023 The Benefits Of Using A Mortgage Broker: Why You Should Consider One Home Credit: Information, Eligibility Criteria, Interest Rates, Review & More
Apr 21, 2023