What Is The Current Ratio Formula? – Meaning, Interpretation, And More
The current ratio formula is used to calculate the current ratio of a business, This ratio gives an idea of the company’s capacity to repay its short-term loans that are due within a year. This ratio is really helpful for investors as it tells them about the company’s ability to meet its financial obligations. The investors thus evaluate whether the company is financially sound as compared to other competitors and stocks.
‘In this article, you will learn about what the current ratio means and how to calculate it using the current ratio formula. Apart from that, we will also give you tips on how to interpret the situation of a business using the current ratio formula. You will also learn how the current ratio works in general. Finally, we will discuss some of the major pros and cons of using the current ratio formula to calculate the situation of a business.
What Is A Current Ratio?
According to Investopedia,
“The current ratio is a liquidity ratio that measures a company’s ability to pay short-term obligations or those due within one year. It tells investors and analysts how a company can maximize the current assets on its balance sheet to satisfy its current debt and other payables. A current ratio that is in line with the industry average or slightly higher is generally considered acceptable.”
However, if the current ratio of a company is lower than what is expected on average from the industry, this indicates a higher risk of distress or default for the company. On the other hand, if a company has a very high current ratio as compared to its competitors in the same industry, this shows that the company might not be using its assets in an effective manner.
There are various other liquidity ratios that investors use to calculate the situation of a company. Unlike other ratios, the current ratio makes use of all current assets and current liabilities. That is why the word ‘current’ is used here. It is also called the working capital ratio.
Read More: Disaster Recovery Vs Business Continuity – What Are The Differences?
Current Ratio Formula – How To Calculate It?
According to Wall Street Mojo,
“The current ratio equation is a crucial financial metric that assesses a company’s short-term liquidity by comparing its current assets to its current liabilities. A ratio above 1 indicates the company can meet its short-term obligations, while below 1 suggests potential liquidity issues. It aids in evaluating a firm’s financial health and ability to cover immediate debts.”
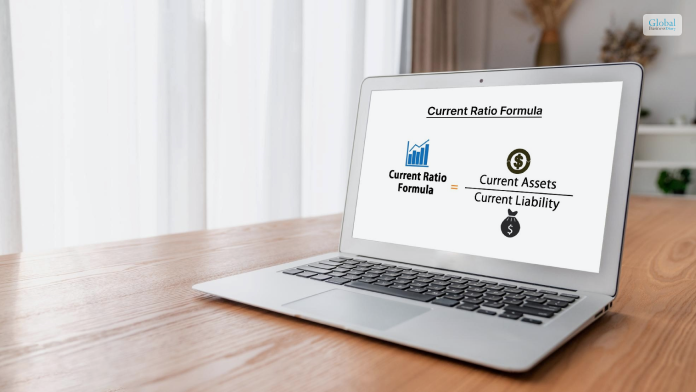
Here is the formula with which you can calculate the current ratio of a company:
| Current Ratio Formula = Current Assets of the company / Current liabilities of the company |
The current assets of the company are listed in the company’s balance sheet. It consists of the following:
- Cash
- Accounts receivable
- Inventory
- Other current assets (OCA) that the company expects to liquidate or turn into cash within a year
The current liabilities of the company are also listed in the company’s balance sheet. It consists of the following:
- Accounts payable
- Wages
- Taxes payable
- Short-term debts
- Current portion of the long-term debt
Interpreting Using The Current Ratio Formula
Based on the end result of the calculation, it can mean different things for the company. Here is how one can interpret the current ratio based on the results of a company:
- If the Current Assets of the company are greater than the Current Liabilities, then the Current Ratio is greater than 1. This shows a desirable situation for investors and the company.
- If the Current Assets of the company are equal to the Current Liabilities, then the Current Ratio turns out to be exactly 1. This shows that the company’s Current Assets are not enough to pay its short-term obligations.
- If the Current Assets of the company are less than the Current Liabilities, then the Current Ratio is less than 1. This creates a problem for the company since it does not have enough assets to pay for its short-term obligations. Investors mostly do not prefer to invest in such companies.
How Does The Current Ratio Work?
According to TheForage.com,
“The current ratio describes the relationship between a company’s assets and liabilities. So, a higher ratio means the company has more assets than liabilities. For example, a current ratio of 4 means the company could technically pay off its current liabilities four times over. However, what makes a good current ratio depends on the industry.”
In general, if the current ratio of the company stays between 1 and 3, it is an ideal situation for the company to get investments. However, there are certain business models and industries that operate perfectly fine with lower ratios.
What Are The Pros And Cons Of Using Current Ratio?
The following are some of the major pros and cons of calculating a company’s capability using the current ratio formula:
Pros Of Using Current Ratio
Here are the major pros of using the current ratio formula:
- It helps in understanding how cash-rich the company is
- It helps in gauging the short-term financial health, and stability
- It gives an idea of the operating cycle of the company and how efficient it is in selling off its products
- A greater value shows the efficiency of the management
Cons Of Using Current Ratio
Here are a few cons of using the current ratio formula:
- It is not sufficient to analyze the financial situation of the company.
- The inclusion of inventory may lead to overestimation.
- The ratio can be unstable during seasonal sales period.
- A change in the inventory valuation method impacts the ratio.
Read More: Matrix Organizational Structure – What Are Its Pros And Cons?
Wrapping Up
Hope this article was helpful for you in getting a better understanding of how the current ratio formula works for businesses. It basically compares all the current assets of the company to its current liabilities. These assets have high liquidity, that is, either they are already cash, or they can be turned into cash within a year. These can also be liabilities to be paid within a year.
Calculating the current ratio helps investors get a better understanding of whether a company is able to cover its short-term debts with its current assets. Investors also compare this value with other competitors in the industry. Can you share some more applications of the current ratio formula? Share them with us in the comments section below.
Read Also:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles

Financial Planning Tips For Different Stages Of Life
Let us tell you something that can change your perspective on handling finances. It may sound cliché, but it has never been truer than ever – planning always pays off regardless of where you are in your life right now. Did you know that taking control of your hard-earned cash at every stage of your life could greatly impact where you want to be financially? That's right; we are talking about the concept of financial planning for different stages of your life. From embracing adulthood to reaching old age, here's why it matters so much! You go through different stages in your life and might encounter new challenges and goals at various points along the way. So, whether you are a government employee, just graduated from school, hit mid-life stability, or are getting ready to kick back in old age, understanding the nuances of your journey will help you make smarter decisions when it comes to your finances. And guess what? We have got you covered with all things related to financial planning across these distinct life phases. Are you ready to take charge and start building your roadmap to prosperity? Buckle up because our next stop is where the magic happens! 1. Employment The nature of your job plays a crucial role in financial planning. Every organization offers different benefits, including insurance options and provident funds. However, financial planning for Govt. Employees may involve in some particular issues. You might have chosen this career path due to the attractive benefits packages offered, including comprehensive healthcare coverage and generous pensions. Still, you may also confront special financial issues specific to government employment. Let's take a closer look at some crucial variables to bear in mind when budgeting your money. A. Benefits Evaluation (Healthcare & Pension Plans): When comparing private sector positions to government jobs, the latter typically offers competitive salaries alongside robust benefits packages. Adequately assessing all possibilities within healthcare and pension options allows for customization to fit individual circumstances. B. Retiree Status Planning: Reaching retirement age marks a significant milestone for anyone. For civil servants, there are particular guidelines that must be followed to attain retirement status. Determining the correct timeframe and milestones will enable the optimal use of certain benefits like annuities and deferred compensation. C. CSRS vs. FERS Comparison: As a government employee, you fall under either CSRS (Civil Service Retirement System) or its successor program, FERS (Federal Employee Retirement System). Each system has advantages and disadvantages; understanding their differences is crucial for selecting the most suitable option. D. Young Adult Life As you enter adulthood, the world opens up like a freshly blossomed flower, offering myriad possibilities. You might find yourself navigating entry-level jobs while trying to build a solid credit score. With little experience and even less knowledge, managing money becomes an intimidating task. However, this is the time when smart financial choices set you apart from others. Starting with simple steps such as crafting a basic budget, monitoring expenditures, and setting aside cash for unexpected events, lays the groundwork for a secure future. 2. The power of compounding interests So, have you paid off those hefty student loans yet? Well, hang tight because now begins the arduous battle against the burden of repayment. Remember, a thorough approach to tackling debt includes exploring multiple income sources, setting realistic targets, prioritizing expenses wisely, and seeking advice when needed. The beauty lies in exploiting the power of compounding interests, i.e., allowing your money to grow exponentially over time. Plus, who doesn't love having extra cash stashed away for a rainy day? Beginning to save diligently helps avoid potential financial disasters down the line. Leverage low risks With time comes the luxury of witnessing your investments yield rich dividends. Don't wait until you reach midlife to jumpstart your portfolio; instead, leverage low risks early on. Learning about asset allocation, balancing stocks vs. bonds, researching companies, and other complex investment techniques form the basis of successful long-term growth. 3. Mid-Career Professionals This stage brings stability and predictable routines but requires consistent monitoring of finances. Reflect on previous errors and stay committed to ensuring similar pitfalls don't arise in the near future. Analyzing well-thought-out long-term plans and assessing whether they have been met serves as an excellent reality check. It's never too late to pivot or adjust said objectives. Budgetary reviews now include higher net worth and larger monthly savings than before. Savvy savers will focus on boosting retirement accounts through maximized employer matches, IRA contributions, Roth conversion opportunities, and after-tax investments. Umbrella liability insurance coverage can help guard against legal issues triggered by unexpected events. High-interest credit card balances often get transferred to home equity lines, reducing interest charges owed by consolidating obligations. College savings plans also demand careful consideration to secure the best possible educational options for loved ones. With careful deliberation and expert guidance, one can navigate this stage with relative ease and confidence while maintaining momentum toward meeting established fiscal targets. 4. Old-age Retirement represents the culmination of lifelong hard work and dedication. However, it is crucial to ensure adequate preparation has occurred beforehand to avoid any unwanted surprises. At this stage, carefully evaluate the value of accumulated assets and the potential impact of inflation or market volatility on net worth. Importance of Estate Planning and Retirement Decision-Making Now more than ever, having up-to-date estate plans in place becomes paramount, especially if looking to distribute inheritance among heirs in an orderly manner. Carefully contemplate the decision to continue working or transition fully into retirement, including decisions surrounding when to start receiving Social Security benefits to optimize lifetime payouts. Maximizing Retirement Resources: Identifying Potential Shortfalls and Preparing for Healthcare Needs Additionally, take stock of expected post-retirement spending requirements and compare those figures against currently projected financial resources to identify potential shortcomings. Pay attention to Medicare enrollment and appropriate Part D prescription drug coverage choices. Building a Lasting Legacy Lastly, focusing efforts on legacy building through means such as philanthropy or intergenerational wealth transfers will help create lasting impressions beyond mere monetary measures alone. By addressing these critical areas, entering old age provides a solid foundation for living happily and purposefully during this exciting chapter of life. Conclusion As the old saying goes, “Failing to plan is planning to fail.” That couldn’t be more true when it comes to managing our finances through every stage of our lives. From young adulthood to retirement and beyond, having retirement planning services and plans is crucial to achieving both short-term and long-term goals. Remember that it's never too late to start fresh and implement positive changes. Make a habit of regularly reviewing and updating your financial blueprint to adapt to evolving needs and goals. By staying organized and proactive, you'll enjoy greater peace of mind, stronger overall stability, and happier days ahead. Read Also: A Brief Guide To Business Integrated Planning Maximizing Tax Refunds: Tips And Tricks For Canadians Seven Potential Tax Credits Available To Small Businesses In 2023
Apr 27, 2023
Successful Trading Strategies With Bullish Engulfing Patterns
In financial markets, traders are constantly on the lookout for reliable patterns and signals to guide their decisions. One such pattern that has stood the test of time is a bullish engulfing pattern. This candlestick pattern is a strong indicator of a potential bullish trend reversal and has been a cornerstone in the toolkit of successful traders. So, delve into the strategies below that traders employ to capitalize on the Engulfing Patterns and potentially turn the tides of their trading fortunes. Identifying The Patterns The first step in any successful trading strategy involving these Patterns is identifying them. These patterns consist of two candlesticks – the first is a smaller bearish candle, followed by a larger bullish candle that completely engulfs the previous one. Traders look for this clear and distinct formation on their price charts. It's crucial to use technical analysis tools like moving averages, RSI, and trend lines to confirm the potential reversal before making any trading decisions. Timing Is Key Timing is everything in the trading world, and this holds when dealing with a bullish engulfing pattern. So, to maximize the chances of success, traders often wait for additional confirmation before entering a trade. This can include waiting for the bullish candle to close, ensuring it engulfs the bearish one. Waiting for confirmation can help filter out false signals and reduce the risk associated with premature entries. Setting Stop-Loss And Take-Profit Levels Risk management is a key aspect of any trading strategy, and trading these Patterns is no exception. Setting stop-loss and take-profit levels is crucial to safeguarding your capital and locking in profits. Traders typically place a stop-loss just below the low of the bullish candle that formed the pattern. This level serves as a safety net to limit potential losses if the trade doesn't go as expected. Meanwhile, take-profit levels, on the other hand, are usually set at a reasonable distance from the entry point, allowing traders to secure profits when the market moves in their favor. Combine With Other Indicators Successful traders understand the critical importance of utilizing a variety of multiple indicators and analytical tools in their comprehensive market analysis. While these Patterns are inherently powerful on their own, they become exponentially more robust and reliable when combined with other diverse technical indicators. Traders often vigilantly look for additional confirming signals such as overbought or oversold conditions, pivotal support and resistance levels, or clear trend confirmation from other reputable indicators like the MACD. This multifaceted, layered approach can provide stronger, more reliable validation for the potential bullish reversal, enhancing trading strategies. Practice Patience And Discipline Trading can be emotionally charged, and the excitement of spotting an Engulfing Pattern can lead to impulsive decisions. However, discipline and patience are essential virtues in trading. Successful traders know the importance of sticking to their trading plan and not letting emotions cloud their judgment. They wait for the right setup and confirmations and ensure they are not overtrading. Consistency in applying their strategies is what sets them apart. Conclusion In trading, mastering a bullish engulfing pattern can be a game-changer for traders looking to capitalize on potential bullish trend reversals. By identifying these patterns, timing their entries, setting appropriate risk management levels, combining them with other indicators, and practicing patience and discipline, traders can enhance their chances of success. Remember that no trading strategy is foolproof, and losses are a part of the game, but by adhering to these strategies and continuously learning and adapting, traders can work towards achieving consistent profitability. So, the next time you spot an Engulfing Pattern on your price chart, approach it with these proven strategies in mind, and you might just find yourself on the path to trading success. Read Also: Bnku Stock: Microsectors Us Big Banks Index 3x Leveraged Etns Tui Share Price Forcast: Everything You Should Know Poocoin Stock Forecast: Everything You Should Know
Dec 28, 2023
A Guide To Creating A Solid Budget
Creating a budget can seem like an overwhelming task, especially when trying to navigate through personal finances. However, it's a step of paramount importance for financial stability and growth. A solid budget not only helps in tracking where your money goes but also in planning for future expenses and savings. It serves as a roadmap to financial freedom and prevents unnecessary stress related to money matters. Keep reading as we delve into the essentials of personal budgeting and offer practical strategies to help you manage your finances effectively. What Is The Purpose Of Creating A Solid Budget A solid budget is one of the core requisites to emerging successfully in the competitive market. Keeping this importance in mind, businesses, irrespective of size, invest time and resources to prepare a solid budget. It can help you understand your needs. However here we make a little discussion of the the key purpose in framing a solid budget. So let us get started with the discussion here. When you frame a comprehensive budget for one year, it means you are taking note of your prospective spending that financial year. A solid budget acts as a framework for your expenditure and future plans. Hence, you have to be quite calculative with the plan that you wish to have for a financial year. The success of a business organization depends on long-term planning. Preparing a budget can help you understand your needs, and at the same time, it can help you have a solid framework, which is crucial in understanding your goals and objectives. Overspending is not at all a good habit and it can drive your business towards complete failure. A budget keeps you on track and makes it risk-free. Creating A Solid Budget: How To Do It? The present ecosystem in business is highly challenging, and as an individual you must be calculative with your budgeting approach. Creating a solid budget helps you address your core needs and manage your concerns. Therefore while you are creating a budget you have to be highly watchful of not one but many aspects. However, we try to understand some of the aspects the have a linkage with a solid budget. Assessing Your Financial Situation And Setting Goals Start by doing a financial self-assessment which involves reviewing bank statements, credit card bills, and any other financial documents. Look for patterns in your spending and note any areas of concern. This process will help you to pinpoint opportunities for improvement and wasteful expenditures that can be eliminated. With a clear understanding of your current financial situation, setting specific, measurable, achievable, relevant, and time-bound (SMART strategy) goals becomes possible. Whether your aim is to pay off debt, save for a down payment on a house, or build an emergency fund, well-defined goals give your budget a purpose and keep you motivated. Determining your financial priorities is also key. Decide what's most important to you and allocate funds accordingly. If paying down debt is a priority, consider strategies like the debt snowball or avalanche method to tackle your obligations effectively. Tools And Techniques For Effective Budget Tracking In today's digital age, there are numerous tools and apps designed to simplify the budgeting process. From spreadsheets to sophisticated budgeting software, these tools allow you to track your spending and see real-time updates of your financial situation. Opt for one that aligns with your preferences and consistency in usage. For many people, automating their finances serves as a budgeting breakthrough. Setting up automatic transfers to savings accounts and automating bill payments ensure that you never miss a due date. For example, services like Boost Mobile pay bill online streamline the process of monthly bill payments, helping to avoid late fees and maintain good credit. Periodic reviews of your budget are also necessary. This means setting aside time, perhaps monthly or quarterly, to go over your budget and adjust as needed. Keeping a close eye on your financial progress will help you stay on track and quickly address any issues before they balloon into bigger problems. Allocating Funds To Essential And Non-Essential Expenses Creating a budget necessitates making informed decisions about how you allocate your funds each month. Essential expenses are typically non-negotiable expenses that are crucial for basic living, while non-essential expenses are those that you can live without—these are often the first to be adjusted when finances are tight. Prioritize spending on essentials such as housing, food, and healthcare. These are expenses that maintain your well-being and are required to function in life. Once these are covered, assess how much is left for discretionary spending on things like entertainment, dining out, and other luxuries. An effective approach is the 50/30/20 rule, where fifty percent of your earnings go toward needs; thirty percent towards wants, and finally, twenty percent towards savings and debt repayment. However, don't be afraid to tweak these percentages to better suit your financial situation and goals. Your budget should be as unique as your financial circumstances. Adjusting Your Budget To Reflect Changes In Finances A well-thought-out budget isn’t static; it evolves as your financial situation changes. Pay raises, unexpected expenses, changes in family size, or economic shifts all warrant a revisit to your budget. Adapting your budget to reflect these changes is critical for maintaining its effectiveness and building a financial legacy that extends beyond your immediate needs. Always reassess your budget when experiencing a substantial financial change. This includes positive changes, like a salary increase, where the extra income can support accelerated debt repayment or increased savings. Similarly, if income decreases, reviewing and reducing non-essential spending becomes necessary. Certain life events also necessitate budget adjustments. Marriages, births, and retirements are significant transitions that can impact your finances. A proactive approach to these life changes ensures your budget remains supportive and beneficial in the long term. Keeping your financial goals updated during these times is also crucial. Conclusion Overall, the art of budgeting is a continuous process that requires attention, discipline, and occasional recalibration. By understanding the dynamics of your financial life, setting clear goals, and utilizing the right tools, you can create a robust and responsive budget that stands the test of time and shifts in circumstance. Altogether, the journey to financial stability is within reach when equipped with a well-crafted budget. Read Also: Family Budgeting 101: Tools And Tips For Managing Household Finances Maximizing Your Home Loan Options: Finding The Best Fit For Your Financial Goals 5 Essential Aspects That Every Small Business Needs
Jan 30, 2024
Common Personal Loan Myths You Should Not Believe: A Complete Guide:
Personal loans are currently one of the most popular loans. You can use it for any purpose. You may be wondering why so many individuals prefer personal loans. Personal loans provide several advantages to borrowers. However, they are only sometimes the best solution for everyone. A personal loan has many benefits. It includes fast approval, easy qualifying requirements, speedy disbursement, and flexible payback terms. In all kinds of cash crunches, the loan can assist you. Despite the benefits, there are several myths that one should not believe. What Are The Pros Of A Personal Loan? Because interest rates are often much lower, a personal loan is usually cheaper. It is cheaper than using a credit card or receiving a payday loan. Also, payday loans must be repaid in full. Hence a personal loan is a more convenient alternative. Most personal loans are small and can be as much as $100,000. Have you considered applying for a personal installment loan but are still determining if it is wise? This article will help you with it. Moreover, if you want a personal loan, sorting payroll is essential. However, you can use a paystub generator for smooth working. A personal loan might be an excellent solution depending on your financial condition. It will assist you in making your payments. Continue reading to learn about the common myths about personal loans. Myths About Personal Loans: Read on to learn about seven common myths about personal loans. You will also be able to see the reality behind it. It will help you to apply for one. A low credit score results in loan denial: Many consumers believe they will not get their loans approved because of poor credit scores. An individual's credit score is not the only thing that banks consider. When determining loan eligibility, other variables take priority over a poor credit score. Besides an individual's credit score, financial organizations also consider other factors. It includes the borrower's income and ability for repayment. Personal loans have a lengthy processing: Borrowers avoid applying for a personal loan because they expect a longer processing time. They also believe that there is a need for more approval procedures. Personal loans are not secure. So they do not need collateral. You can issue them within 2-7 working days. You need to file the loan application with small documentation. Moreover, some lenders offer to provide same-day personal loans. Huge interest rates: The most widely held assumption about personal loans is their high-interest rates. In practice, these loans may be cheaper than other unsecured loans. Remember that having a fantastic credit score is the key to qualifying for low-interest rates. If you want a personal loan, shop with other lenders to check interest rates. Understanding what different lenders have to offer will help you get the best personal loans. It also helps individuals with bad credit to get a loan at the best interest rate. It does not have to be a stressful or time-consuming procedure. You may compare interest rates and personal loan lenders easily and quickly. It is hard to get approval: Another common myth about personal loans is that they are challenging to get. This is arguably the most common myth that is simple to believe and qualifies but is incorrect. Obtaining this form of loan nowadays is as simple. It is as simple as completing an online application and waiting for approval. Applying for a personal loan is simpler than obtaining a house or a vehicle loan. It begins with a simple online comparison of your loan possibilities with fixed and variable interest rates. The Only Lenders Are Banks: Before the internet age, banks were the sole providers of personal loans. There is a growing popularity and renown of internet lenders. Consumers today have several possibilities for obtaining a personal loan. Cooperating with an internet lender might provide you with several perks and advantages. Most significantly, the personal loan application procedure is simple and quick. You may receive an instant response to your application. You can use the loan only for personal reasons: It may be confusing to you since the term implies "personal." Many people believe that the loan is for personal purposes. Other lending organizations, unlike banks, are not concerned with how or where you use the money. They will not interfere with your plan to spend the money. You only must make monthly payments on schedule. You must show a serious commitment to return the loan amount. It is up to you how you intend to use it. You may also use it as extra funding for your business. Perhaps you need it for an emergency, such as repairing a broken automobile or home. There are so many ways where you can use a personal loan. Personal loans are available to salaried persons: It is generally believed that only people with a regular income stream are eligible to apply for personal loans. It is just another misconception about personal loan applications. When there is a consistent income stream, it is simpler for salaried workers to get their loan applications authorized. Those who are self-employed can also get personal loans. The individual's credit history determines the approval of the loan amount. But the amount approved may differ. NOTE: Many people find personal loans to be an attractive source of money. Unfortunately, most need to familiarize themselves with the many components of personal loans. There are various myths or misconceptions. You should not trust them. To take advantage of personal loans, you must first verify your beliefs. The list will help you determine what is true and what is not. Understanding these myths can help you on your loan journey. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Mar 17, 2023