How To Start An Insurance Company? – Steps You Must Take
How to start a life insurance company? – There is no short answer to this question. It is not a small task to start an insurance company. However, having the right focus and the right steps can help you to turn your new business into a victorious one in a short span of time. To learn more, read on through to the end of the article.
The best steps to take on how to create an insurance company would be the ones that are tried and tested by many. Realistically speaking, the risks associated with the insurance sector are so high that a small mistake can cost you a fortune. Hence, you need to take careful steps. Despite that, there are some places you will need to be unique as well. But, to get started, the best option for you would be to stick to the basics.
How To Start An Insurance Company? – Major Steps
One of the first things that you can do to start an insurance company is to find out an idea of what will make your company different from the top companies in the market. Once you have chosen the insurance industry, you will need to do a quick search of the existing companies.
According to Business News Daily,
“Learn what current brand leaders are doing and figure out how you can do it better. If you think your business can deliver something other companies don’t (or deliver the same thing, only faster and cheaper), you’ve got a solid idea and are ready to create a business plan.”
To start with
“how to start my own insurance company,”
you will need to ensure that your business does not face any legal problems or any other external problems. Hence, you need to make sure that your business is safeguarded as long as external issues are concerned. For that to happen, you need to follow some basic rules.
The following are the major steps you must take to start your own insurance company in 2023:
1. Planning To The Core

According to The Hartford,
“When you create a business plan, you’re describing every aspect of your business in a formal document. This lets other people understand what you do, what your objectives are and what strategies you have in place to achieve your goals.”
Furthermore, this document will also be your proof that you are dedicated to the business. This is beneficial for staying clear in front of insurance companies, shareholders, and staff members. However, with time, you will also need to update your business plan with necessary changes as per the demand of the market.
Read More: The Types Of Business Insurance Needed For Every Business
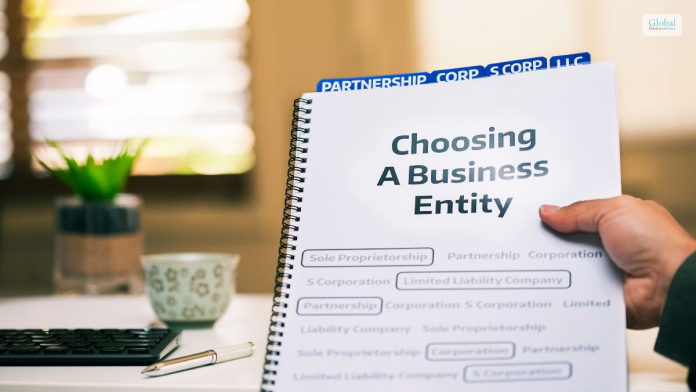
2. Decide What Will Be Your Business Structure
According to SBA.gov,
“The legal structure you choose for your business will impact your business registration requirements, how much you pay in taxes, and your personal liability.”
Here are the major types of business structures:
- Sole Proprietorship
- Corporation
- Limited Liability Company (LLC)
- Partnership
- S Corporation
This depends on your personal responsibility and the setup of your business, as well as the setup of your business. Hence, you will need to choose the business structure that is right in your case. The structure depends upon your personal liability level.
3. Register Your Organization’s Title

Registering is important. As per the recommendations of TheHartford.com,
“Your business needs to be official. Aside from giving your startup more credibility with potential customers and clients, registering can also help protect your business’ name.”
If your business is structured as a sole proprietor, your personal name is automatically the legal name of the company. However, you can give another name in the “doing business as” section. You will need to select and register a suitable name for your business.
4. Get Your TIN (Tax Identification Number)

As per IRS regulations, every corporation and partnership needs to use FEIN (Federal Employer Identification Number) while it is filing taxes. This number is also important in the case of opening a bank account or a credit account for your business.
However, if your business is structured as a sole proprietor, you will need to use your social security number (SSN). You will get the number after you register your business with the local government and IRS.
5. Ensure That Your Business Is State Registered

Once you have received your Tax ID, you will have to connect with the State Insurance Commissioner’s desk. Businesses typically register as “resident business entities” when it comes to purposes related to state and local taxes.
Once you register, your state will charge a registration fee from you. They will also give you a checklist, where they will ask you to ensure that you are aware of the state requirements and comply with them.
6. Get The Necessary Local Authorizations And Licenses
Getting authorized at the local level and getting all the necessary licenses and permits is crucial to operating your business. Although you are a licensed insurance agent now, you will still need a general business permit at the local level or even a license if you want legal safeguards.
However, according to Insureon.com,
“The licensing, insurance, and bonding requirements for insurance agents vary by state. Having the right insurance and bonding can help keep you financially protected, and may be required for some jobs within the insurance industry.”
7. Get Insurance To Save Your Company’s Capital
Depending on the structure and assets of your business, you will need to purchase insurance. There are a variety of business insurance you can check out to find which one is the right need for the moment. You can also consult with your lawyer, as well as your insurance guide, to find out which insurance is perfect for you now.
Read More: Maximizing Home Insurance Coverage For Your At-Home Business With Riders
Final Thoughts
Hope you have found your answer on how to start an insurance company. Before starting your business and competing in the market, you will need to make sure that your business has all the legal safeguards. This is the most important aspect, as it will help your business in the long run. Share your thoughts about the business safeguards and other ideas in the comments section below.
Read Also:
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
The Best Risk Mitigation Techniques For Your Business
Risks in business are inevitable, and with new projects and processes, the level of risks in business increases. This is because there are inherent risks that are associated with the processes of a project. However, there are some strategies that you can follow for risk mitigation. These will help you deal with risks in business that arise with the coming of new projects. In this article, you will learn some general details about risk mitigation. You will also learn how to plan for risk mitigation in business. Then, we will share with you some of the major risk mitigation strategies to follow. Hence, to learn more about risk mitigation in business read on through to the end of the article. What Does Risk Mitigation Mean In Business? According to Indeed.com, “Risk mitigation refers to the process of planning and developing methods and options to reduce threats—or risks—to project objectives. A project team might implement risk mitigation strategies to identify, monitor and evaluate risks and consequences inherent to completing a specific project, such as new product creation.” Major risk mitigation strategies include the actions that managers put in place to deal with major issues and also the effect of these issues in regard to the project. These strategies are brought in by risk management. Risk management is one of the most essential tools required to run a business, especially when the business faces a downturn. When an internal risk or an external risk, an unexpected surprise can easily destroy the business processes. Hence, this is whether risk management strategies help. With these strategies, you will be able to know what steps to take if you want to mitigate the risks in business. How To Plan For Risk Mitigation? With the help of a risk mitigation program, you will have your procedures in hand. However, before you mitigate the risks, you will be able to identify those risks. You will have to learn what type of risks you are dealing with, for example, organizational risks. Furthermore, you will have to stress the importance of identifying the different vulnerabilities that can affect your business. According to TechTarget.com, “A priority list should be created to rank each risk according to the likelihood of occurrence and severity of the impact on the enterprise. A high-probability event, for example, that has little or no impact on the enterprise, such as an employee calling in sick for one day, will be treated differently than a low-probability, high-impact event like an earthquake.” Identification is necessary if you want to address a particular risk and its threats and vulnerabilities. Next up, you will need to validate and analyze it to find the likelihood of the risk’s occurrence in business. You can also involve the employees and customers and learn from them their own feedback on the problems they are facing. This way, you can find the hidden risks that are threatening your business. In the business realm, these vulnerabilities can often appear in financial areas, notably during taxing periods. For these complexities, hiring a professionals can be invaluable. If you're considering hiring a sales tax accountant, you're opting for a preventive risk mitigation strategy. This expert can help manage your tax affairs effectively, ensuring complete compliance while identifying possible cost-saving areas. Hence, hiring a CPA for sales tax can indeed act as a significant risk buffer for your business. Read More: The Types Of Business Insurance Needed For Every Business What Are The Best Risk Mitigation Ways In Business? According to Investopedia, “Risk management has always been an important tool in running any business, particularly when a market experiences a downturn. In any economic environment, an unexpected surprise can destroy your business in one fell swoop if you didn’t have the right risk management strategies in place to prevent, or at least mitigate, the damage from that risk.” Hence, it is important for the business to have a risk management process in place. However, to enable risk management to work, risk mitigation is important. Here are the steps that you can take to ensure risk mitigation: 1. Throw A Challenge Towards The Risk If you see a future risk, start challenging it by allowing it to progress. However, make sure that the dangers are negligible and are easily manageable. This way, you will be able to learn the risk and prevent it accordingly. 2. Start Prioritizing The hazards that the risk can bring pose negative effects for your business and your team. Once you prioritize the risks, you can minimize the potential impact. You are just dealing with the risk as per its order of importance. 3. Exercise The Risk Since you have already identified the major hazards associated with the risk, it is time to exercise those risks. To do that, start running experiments, drills, and other exercises to model threats. 4. Risk Isolation You cannot stop other activities in the business which are necessary for its operation. By isolating the risk from other aspects of operations, you can minimize the risk’s negative impact. 5. Risk Buffering Once you add extra resources to the situation, you can minimize the potentiality of the risk. The resources can be time, money, or even personnel. This is called buffering of the risk, as it reduces the negative impact of the risk. 6. Risk Quantification Risks come with both cost and reward. You will need to quantify, compare, and analyze both sides in regard to the risks. This will help you to determine whether the positives are enough to justify the risk’s impact. 7. Monitoring The Risk Since risks are not static, you must use a two-way communication solution to monitor the risk conditions that affect your business. 8. Contingency Planning No matter how much you plan and stick to the plan, it can still lead to failure. Hence, always keep a backup plan in place, even when you think you have handled the risks. 9. Learning From Best Practices Since there are many businesses and industries present, the occurrence of a novel risk for your business is less probable. Someone might have already faced the risks that you are facing now. Hence, you should look for best practices in the industry to mitigate risks. Read More: How To Start An Insurance Company? – Steps You Must Take Wrapping Up Hope this article was helpful for you in getting a better idea of the best risk mitigation strategies for businesses. To ensure proper risk mitigation, the business needs to implement a top-end risk management policy in place. This will act as insurance in itself and can become an important step to ensure the success of the business. Consider following the aforementioned risk mitigation strategies in your business once you have identified the inherent risks for your business. Do you have any more recommendations in mind regarding the best ways for risk mitigation in business? Share your views with us in the comments section below. Read Also: How Do Entrepreneurs Make Money? – The Secrets You Should Know Project Management: What Is It? – Major Types, Examples, And More 10 Must-Have Entrepreneurial Characteristics
Sep 02, 2023
What Is A Sales And Purchase Agreement For Business? – Let’s Find Out
A sales and purchase agreement for business is a binding legal contract that consists of conditions both the buyer and seller of a business or property agree upon. In any sale process, it is one of the main legal documents. It basically sets out the elements that are agreed upon in a business deal. It also consists of the number of protections of both parties as well as the legal framework for the completion of the sale. In this article, you will learn about the sales and purchase agreement (SPA) and some of its general details. Apart from that, you will also learn about how the sales and purchase agreement works for businesses. In addition to that, we will also discuss the major constituents of a sales and purchase agreement that all the parties in a sales process need to consider. Hence, to learn more about the SPA, read on through to the end of the article. What Is A Sales And Purchase Agreement For Business? According to Investopedia, “A sales and purchase agreement (SPA) is a binding legal contract between two parties that obligates a transaction to occur between a buyer and seller. SPAs are typically used for real estate transactions, but they are found in other areas of business. The agreement finalizes the terms and conditions of the sale, and it is the culmination of negotiations between the buyer and the seller.” In the case of the trading of a product or a service between two parties, there is a need for a legally binding contract that outlines the details of the agreement. This is called the sales and purchase agreement, and both parties (the buyer and the seller) need to sign the agreement contract. Furthermore, neither of the parties will be able to disobey the contract at any cost. Otherwise, it might lead to legal action. However, it is not an obligation for either of the parties to stay on the deal in question if one of them disagrees with the deal. Once both parties sign the agreement, they will need to follow the terms of the translation. Some of the essential things that are present in this agreement include - terms and conditions, purchase price, deposits made, limitations, closing date, contingencies, etc. How Does A Sales And Purchase Agreement (SPA) Work? According to Wall Street Mojo, “The sales and purchase agreement of business signifies the culmination of negotiations between the buyer and seller and restricts them from ditching each other. The two parties mutually agree upon it before signing it and making it legally binding. It does, however, require both parties to read the contract carefully and seek legal counsel before deciding whether or not to sign it or request a revision.” The sales and purchase agreement occurs mostly in real estate deals, stock purchases, mergers & acquisitions, advertising contracts, etc. On the other hand, the constituents of the SPA include its purchase price, settlement date, deposits paid during the negotiation process, limitations, contingencies, and many more. Apart from that, in such an agreement, both parties in the sales process need to agree to the contract after thoroughly reading it. For this, a business needs to obtain legal advice after signing it and requesting a change. The agreement, basically, provides protection to the interests of both parties. Apart from that, it also restricts them from working against each other or moving away after signing the deal. This factor helps in minimizing potential conflicts and helps to forecast demand and costs of business. What Are The Constituents Of An SPA? According to the Corporate Finance Institute, “Essentially, the sale and purchase agreement spells out all the details of the transaction so that both parties share the same understanding. Among the terms typically included in the agreement are the purchase price, the closing date, the amount of earnest money that the buyer must submit as a deposit, and the list of items that are and are not included in the sale.” 1. Asset Identification Here, you will get information about the specific asset that is subject to sale. In the case of a real property, the location and other details of the asset are jotted down. 2. Purchase Price and Conditions It consists of the exchange price of the transaction in question. Apart from that, the agreement also contains details about how much is already paid and how much is left. It also contains information about the way that the deposit is to be made. It also outlines how the buyer will pay the remaining balance of the transaction. 3. Due Diligence There is a section in the agreement that asks the buyer to acknowledge their due diligence in the transaction. It also contains the due diligence period, which might contain additional payments. 4. Covenants/Conditions Prior to Close The agreement also contains the next steps of the transaction process. The conditions here must be in order to make the sales process legally binding. If the parties fail to follow or if there is any inaction, then it amounts to a breach of contract. 5. Damages/Remedies In some cases, the parties need an explanation regarding what to do in case of damage prior to the sale or during the transit of a product. Hence, this section consists of various levels of damages that can occur to the asset. As per each damage, there is a remedy present. Final Thoughts Hope this article was helpful for you in getting to know about the sales and purchase agreement (SPA). A sales and purchase agreement for a business is a legally binding contract that consists of the conditions set by the buyer and seller, which both agree upon. SPAs are mostly common in real estate dealings, in which the item of transaction is large and includes a big amount. The SPA basically consists of various important information about the sales deal that includes the prices of the asset, the sales price, as well as the payment terms of the sales. It also consists of information about the due diligence period and the agreed-upon conditions. Do you have any more info to add? Share your ideas with us in the comments section below. Go For The Best And Latest Business Related Articles By Clicking Below!! What Are Articles Of Incorporation? – Importance, Working, And More Inventory Turnover Ratio: Definition, Formula, Working, And More What Are Articles Of Organization? – Let’s Find Out
Nov 10, 2023
Disaster Recovery Vs Business Continuity – What Are The Differences?
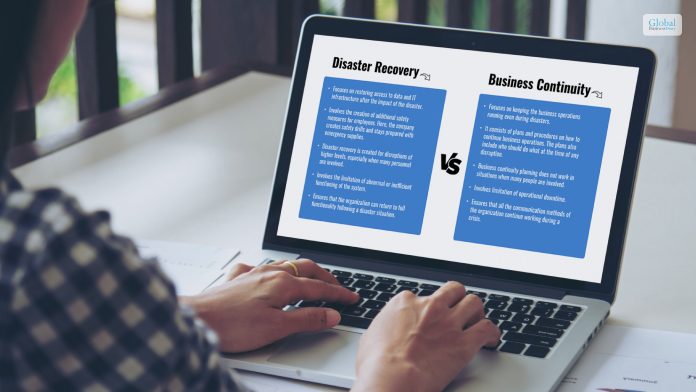
Disaster recovery vs business continuity: Which one is important? - The short answer is “Both.” It depends on the situation you are dealing with. Most companies operate by assuming that their workplaces will maintain their consistent state with changing times. Hence, they try to find comfort in daily routines and rhythm of work. However, there are certain events when a business might face disruption. Hence, businesses need to have a disaster recovery plan and a business continuity plan in place to ensure that the business recovers faster when it comes across a negative situation. In this article, you will learn about disaster recovery and business continuity in general. However, the focus of the article will be on the differences between the two. Apart from those differences, we will also discuss the major similarities between them as well. In addition to this, we will, in brief, share with you how each of these works and how to implement them. Hence, to learn more, read on through to the end of the article. Disaster Recovery Vs Business Continuity – What Are They? If you want to prepare for disruptions in business, you will need to create various strategies and plans, following which you will be able to ensure that the core business functions are intact. This can help the business to come back faster from the uncertain negative consequences it just faced. What Is Disaster Recovery? Amazon Web Services defines disaster recovery as such - “Disaster recovery is the process by which an organization anticipates and addresses technology-related disasters. The process of preparing for and recovering from any event that prevents a workload or system from fulfilling its business objectives in its primary deployed location, such as power outages, natural events, or security issues.” To measure the targets of disaster recovery, two factors are taken - Recovery Point Objectives (RPO) and Recovery Time Objectives (RTO). The failures for which companies make disaster recovery plans are mostly larger-scale disaster events. The plan includes various procedures and policies for the company so that it can recover quickly from the disaster by following them. What Is Business Continuity? According to the Business Continuity Institute, “Business continuity is about having a plan to deal with difficult situations so your organization can continue to function with as little disruption as possible. Whether it’s a business, public sector organization, or charity, you need to know how you can keep going under any circumstances.” You will need a business continuity plan, too, in case of a disaster situation. However, the continuity plan is to deal with the disaster situation so that the organization is able to continue its functioning with little to no disruption. However, you will need to understand here that a business continuity plan does not work at times of a large program or a disaster, which affects the company a lot. It also does not work when a large number of people are associated with a single plan. Hence, many big companies make business continuity plans for each of their departments. This makes each department implement the plan as per its needs. Disaster Recovery Vs Business Continuity – Major Differences Disaster RecoveryBusiness ContinuityFocuses on restoring access to data and IT infrastructure after the impact of the disaster.Involves the creation of additional safety measures for employees. Here, the company creates safety drills and stays prepared with emergency supplies.Disaster recovery is created for disruptions of higher levels, especially when many personnel are involved.Involves the limitation of abnormal or inefficient functioning of the system.Ensures that the organization can return to full functionality following a disaster situation.Focuses on keeping the business operations running even during disasters.It consists of plans and procedures on how to continue business operations. The plans also include who should do what at the time of any disruption.Business continuity planning does not work in situations when many people are involved.Involves limitation of operational downtime.Ensures that all the communication methods of the organization continue working during a crisis. You can see from this table that both disaster recovery and business continuity are complementary to each other. Businesses need to combine both plans to ensure they are prepared for disastrous events. Disaster Recovery Vs Business Continuity – Major Similarities The following are some of the major similarities that you will find between disaster recovery and business continuity: Both are proactive strategies that enable a business to stay prepared for uncertain and disastrous events. Both plans allow the company to minimize the effects of the disaster before it actually occurs and affects the business. Both work quite well in situations of natural and man-made disasters. However, the result of their implementation depends on the situation. Professionals need to review both plans on a regular basis, and some of them need revision with the evolving situation of the organization. How Do Disaster Recovery And Business Continuity Work? According to the University of Central Florida, “Having business continuity and disaster recovery plans in place can help companies minimize the consequences of a catastrophic event. They can also provide peace of mind; employees and business owners alike may feel more comfortable in a work setting where there are clear policies for how to respond to disasters.” To implement these plans for the recovery of the business, the organization needs to create/hire crisis management professionals. These professionals will be responsible for developing and implementing such plans. Apart from that, they are also responsible for evaluating and revising them as per needs and training the employees of the organization to stay prepared. Final Thought Disaster recovery vs business continuity: Hope this article was helpful for you in getting a better idea of both of these terms and how they operate in the organizational setting. Disaster recovery works in situations when the disruption is big and many people are involved. On the other hand, business continuity planning is to ensure business operations are continued in disruptions. Do you have any more recommendations regarding when and how to implement a business continuity plan and a disaster recovery plan? Share your thoughts and ideas with us in the comments section below. Read More: Entrepreneur : Who Coined The Term ‘Entrepreneur’? Intrapreneurship – Definition, Importance, Duties, And Responsibilities What Is a Franchise, And How Does It Work? – Examples, Benefits & More
Sep 11, 2023
The Role of Franchise Consultants in Expanding Businesses
Want to know how a franchise consultant can help you expand your business? Then this article might be exactly what you are looking for. In this article we discuss ‘what is the role of a franchise consultant in business expansion?’ Every business has different players who have their own role in expanding the business. So, if you are looking to expand your business or businesses you can definitely hire franchise consultants. To answer, what is the role of a franchise consultant? It's to offer you guidance on how you can grow your business and support you through the process. These consultants not only support you as a franchisor but also your people are willing to invest in your franchise business model. As franchisees face lots of obstacles when trying to achieve business goals, here franchise consultants provide guidance to overcome these obstacles. Similarly when you are franchising your business you will have to overcome several obstacles to achieve your goal of expansion. Here consulting an expert or experts in franchising business will be beneficial for you in your journey to expansion. So, here we will see how these franchise consultants can contribute to your business franchise success. Understanding the Fundamentals of Franchise Consultancy To understand what is the role of a franchise consultant you will need to think of these experts as a connectors between two parties. One of these parties is you as the business owner who wants to franchise your business. While the other being those who wants to take up your business franchise. So, the role of franchise consultants is to work as a link between aspiring franchisors and potential franchisees. As franchise consultants from developing strategies to formulating target business strategies, several tasks fall upon these consultants. They also take care of all the documentation related to franchising your business by utilising their knowledge of this sector. They are experts in their sector which makes it beneficial for you to have them guide you when franchising businesses. Your brand ethos is ensured when creating strategies which can be robust and scalable at the same time. They start by market analysis then plan the finances to expand your business and then move forward towards operations. This helps you give a closer look at how much you would need to expand your business financially and what changes need to happen to make it a success. So, to answer your question, what is the role of a franchise consultant? It is to do all the work necessary before laying down a solid foundation for your business franchise. This groundwork helps you achieve success when you expand your business. Franchise consultant’s ability to translate complex industry dynamics into actionable strategies make them an indispensable asset for your business expansion. Engaging with a franchise consultant such as the many specialists at Infinity Business Growth Network opens the door to a reservoir of specialised skills and insights tailored to navigate the intricate franchising landscape efficiently. How Franchise Consultants Facilitate Franchisee Recruitment An important aspect of hiring a franchise consultant is to recruit the right franchisees. They play a crucial part in the expansion strategy by leveraging their vast network and industry connections. This helps them source individuals who share the brand's core values and possess the zeal and capability to drive the franchise toward success. Franchise consultants play the role of screening potential franchisees for your business expansion through targeted marketing techniques. Their strategic approach is to ensure perfect alignment of business goals between your potential franchisees and your business. So, in the long run no conflicts of interest are faced in your business expansion goal. Their expertise allows them to identify candidates with the ideal mix of entrepreneurial spirit who can grow your business. Afterall when you are thinking of franchising your business you are looking to grow your profits. So it's essential for potential franchisees to foster a fruitful franchise relationship with your business. These consultants will facilitate a smoother and more efficient pathway for business growth through finding you the perfect franchisees. Their expertise helps your brand get franchised to franchisees who are fully equipped and committed to upholding your business standards. Thus, contributing to your business goal and success. Navigating Legal and Regulatory Challenges with Franchise Consultants Venturing into the franchising domain brings myriad legal and regulatory intricacies that can prove overwhelming for many businesses. Engaging a franchise consultant offers a pathway through this labyrinth, as these professionals understand the legal landscape governing franchising. They are adept at steering businesses through the preparation and scrutiny of franchise agreements. These consultants ensure franchising documents are compliant with prevailing laws and strategically aligned with the businesses growth strategies. Their expertise extends to advising on intellectual property protection, which is essential for maintaining brand integrity and competitive advantage in the franchise industry. Moreover, franchise consultants are instrumental in identifying and addressing any potential legal hurdles. Therefore, mitigating risks that could derail the franchising process. This proactive approach to legal compliance fortifies a business's legal standing and instils confidence among potential franchisees. This lays a solid foundation for successful and sustainable franchise expansion. Engaging with such experts ensures that businesses adhere to legal mandates. Also ensures that they are positioned to thrive in the competitive franchising arena, unhindered by legal impediments. The Impact of Franchise Consultants on Business Growth and Expansion Want to know what is the role of a franchise consultant in expanding your business? They offer an indispensable partnership for businesses who are eager to scale through franchising. If you are someone who is looking to increase your profitability by expanding your business, then you can hire a franchise consultant. They strategize a ripe environment where your business can navigate the ever changing market to franchise their business. With their strategic input, companies can navigate the multifaceted realms of market penetration, operational efficiencies, and brand consistency with greater ease and precision. Here the role of these consultants goes beyond just advisory as it involves hands-on assistance in sculpting a franchise model. From appealing prospective franchisees to developing strategies for business expansion that can be capable of sustaining your business in long-term growth, franchise consultants' role is crucial. Different development of franchise strategies can bring in different franchisees for your business helping you grow your customer base from every sector. So, your business expansion efforts are practical and aligned with the brand’s core values for the long-term. Their recruitment of proper prospective franchisees gives you an added benefit of sustaining business growth for the long-term. These consultants can mitigate risks and streamline your business franchising process to boost your business significantly through successful partnership. So their collaborative endeavour with your business enhances your brand’s market presence. This solidifies your competitive edge in the market which ensures your franchise system thrives and scales in a sustainable manner. You can achieve not only expansion in the regional but expanding internationally when your franchise is successful under their guidance. This creates a new chapter for your business growth. Choosing the Right Franchise Consultant for Your Business Now if you are knowledgeable about what is the role of a franchise consultant in expanding your business, let’s talk about how to select the appropriate franchise consultant for your business. You must select an appropriate franchise consultant for your business through proper evaluation of their expertise. Look for their accomplishments and understanding of your business sector when selecting a particular franchise consultant for your business. Expert franchise consultants will have a history of facilitating successful franchise operations which can make them the right pick for your company. They will have not only theoretical knowledge but also practical application of strategies that will resonate with your business model. Their depth of insights into your industry plays a crucial role, as it can influence how well your business does in their guidance. Your brand’s identity and market goal should also align with their ability to develop strategies for your business. Additionally, you can assess the consultant’s network and the depth of their services to ensure they can support your business expansion aspirations. Compatibility with your business vision and values is also critical, as this relationship is foundational to navigating the franchising journey successfully. Conclusion Opting for a consultant who mirrors your enthusiasm and dedication can significantly streamline the process, making your venture into franchising both productive and rewarding. Prioritising these factors will guide you toward a partnership that fosters your immediate expansion efforts and positions your franchise for sustained growth and success in the competitive marketplace.
May 04, 2024