





Best Business Credit Cards For Startups In 2023

Best business credit cards for startups can make your life easier for getting short-term loans instantly. Credit cards can help you to build a good business credit score. Your repayments on time can make your CIBIL score better in the long term.
If you are a sole proprietor, then also you are eligible for a credit card. A social security number does not have a significant revenue history. If you are looking for the lowest interest rates, then Credit card history matters a lot.
Cashback rewards and other perks offer a good credit card score. Your startup needs to succeed at times to make things happen in your favor.
Best Business Credit Cards For Startups Available In 2023
Great business credit cards will offer you high limits for credits. Cash back rewards, balance offers, and travel facilities. Your credit card must suit your goals with complete ease. Try out the best options that can make things happen in your way.
1. Chase Ink Business Cash Credit Card
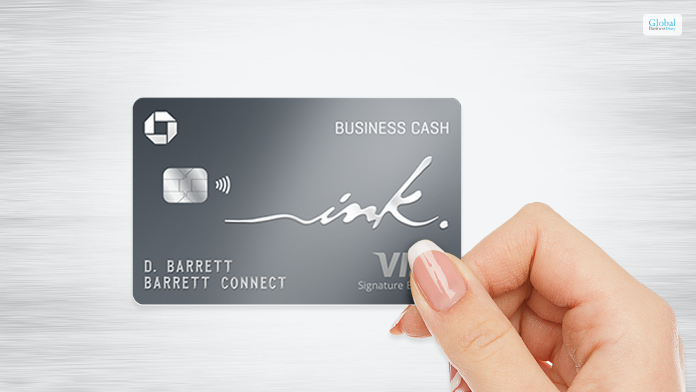
For business owners who are looking for better finances, Chase Ink is one of the best options to avail. It is one of the quality business credit cards for startups. The welcome offer for them is $750. The recommended credit score ranges between 670 -800 to get the maximum benefits of this credit card.
Features Of This Credit Card Are As Follows:-
- The best bonus-earning categories involve phone service, internet, cable, and office supplies.
- With Chase Ultimate rewards, it is highly compatible.
- You will receive 1% cash back on all other purchases.
- 2% cashback, you can redeem on the first $25 spent on restaurants and gas stations.
Your contribution margin needs to be in good shape. It will offer you the best options to explore things with ease.
2. American Express Platinum Business Credit Card
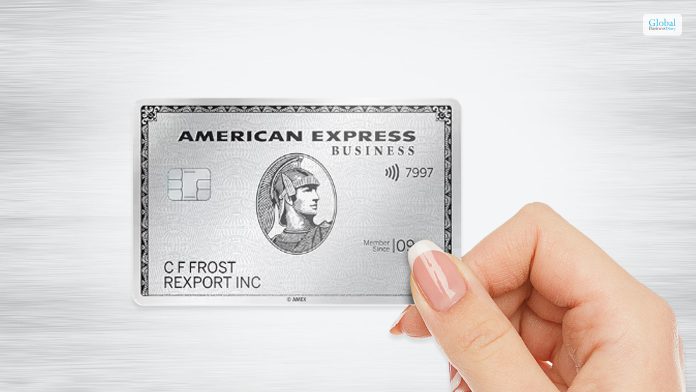
The American Express platinum business credit card is another best credit cards for startups. You will get the welcome offer of 120K points and an annual fee of $695. The recommended credit score ranges from good to excellent. You must be well aware of it. If your business requires frequent travel to distant places.
Some of the core features of this credit card are as follows:-
- $100 statement for credit entry and global entry for $85 in case of TSA precheck.
- Extensive travel and shopping protection.
- You will get upto 5X membership reward points.
- Minimal non-travel bonuses.
- Compared to other cards high annual fee.
3. Chase Ink Business Unlimited Credit Card

The Chase Ink Business Unlimited credit card is one of the best small business credit cards. You will receive a welcome offer of $750. The recommended credit score must range from good to excellent. You do not have to pay any annual fee and 1.5% cashback rewards you will receive from these credit cards.
Some of the key features of the credit cards are as follows:-
- You will receive unlimited cashback earnings.
- On a new purchase, you will receive unlimited introductory 0% APR for 12 months.
- For getting a high sign-up bonus, you will receive a low spending rate.
- Only foreign transaction fees can apply.
- Limited protection on travel costs as well as purchases.
- No presence of bonus categories.
Similar kinds of information are present in HubSpot too. You can go through it once for better understanding.
4. American Express Business Gold Card
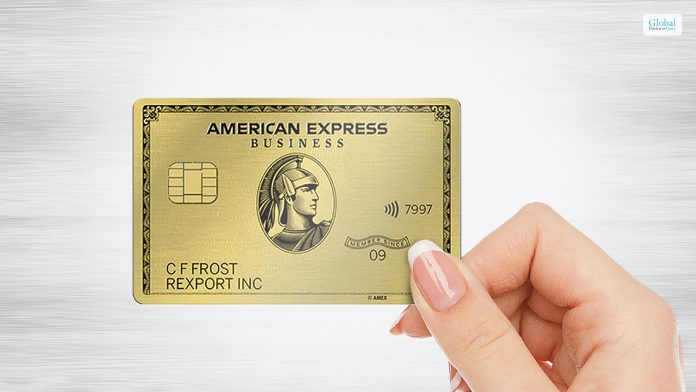
American Express business gold cards will offer you 70K points. You will get an annual fee of $295K points. The recommended credit score ranges from good to excellent. Each billing cycle ranges between $150K. You can earn one point per dollar for expenses.
Some of the core features of this credit card are as follows:-
- You will receive flexible reward and redemption options.
- With the inclusion of the integration of books, it will deliver you expense management tools.
- There are no foreign transaction fees are essential.
- No credit statements.
- Offers high annual fee.
- It is not applicable for the lower spending business.
Sometimes for ERTC qualifications, credit cards play a vital role in getting the loans on time.
5. Chase Ink Business Preferred Credit Card
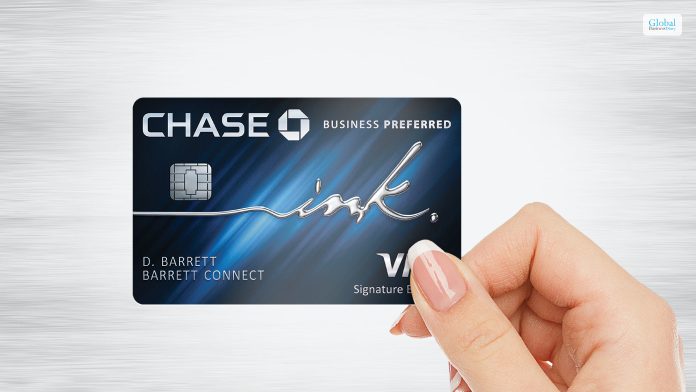
The Chase Ink business preferred credit card is also the best business credit cards for startups. It offers a welcome bonus of 100k points. The annual fee of $95 fees you will receive from these credit cards. The recommended credit score ranges from good to excellent. You will have the privilege to earn three points for every dollar spent.
Some of the core features of the Chase Ink business credit card are as follows:-
- You will receive multiple bonus categories.
- Phone and travel protection is possible.
- There are no requirements for foreign transaction fees.
- It comprises annual fees.
- If you want to get a high sign-up bonus, then you have to pay
- High spend requirements for the sign-up bonus.
6. Blue Business Plus Credit Card From American Business
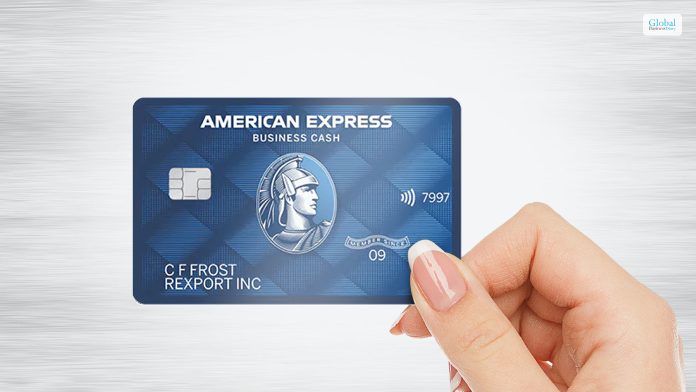
The blue business plus credit card from American business credit cards will help your small business to grow at a rapid pace. You will receive the welcome offer of 15K points. Your requirement to pay the annual fee is $0. The recommended credit score ranges from good to excellent.
Some of the core features of the Blue Business Plus credit card from American Business are as follows:-
- You will have multiple transfer partners.
- On all purchases, you will get flat-rate earnings.
- Delivers your generous welcome offer.
- You can apply for foreign transaction fees.
- $50K bonus earning cap.
7. US Bank Business Triple Cash Reward

The welcome bonus offer you will receive is $500. The annual fee of $0 you have to pay for getting this business credit card for start-ups. The recommended credit score ranges from good to excellent. You will receive business rewards. For a long introductory APR period, you will have to go through it once.
You will receive 3% cashback for all the categories.
Some of the core features of this best business credit card are as follows:-
- $100 statement credit for recurring software subscriptions.
- Upto 5% cash back that is booked on the US bank travel portal.
- No travel rewards you will receive from this credit card.
- Low rate outside all the bonus categories.
Best Small Business Credit Cards
There are several small business credit cards that you can opt for in 2023. Some of the best small business credit cards are as follows:-
- Chase Ink Business Preferred Credit Card.
- American Express Platinum Card.
- Capital One Spark Cash for Business.
- American Express Blue Business Cash Card.
- Discover it, Business Card.
- Wells Fargo Business Platinum Credit Card.
- U.S. Bank Business Platinum Card.
Your business’s net operating income also matters a lot here. Try to consider this fact as well from your end.
Final Take Away
Hence, these are the best business credit cards for startups in 2023. You need to take care of the reality while you want to get short-term loans for your business. It is impossible to make your choices all of a sudden.
You can share your views and comments in our comment box. It will assist us to know your take on this matter. Try to develop a better solution that can make things work perfectly well in your favor.
Read More Busuiness Related News By Clicking Below!!
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles

LLC VS Sole Proprietorship: Major Differences That You Need To Know
LLC Vs Sole Proprietorship: What is right for you? - Whether you are starting a new business or an online store, you will need to choose the right legal structure for your business based on your choice and needs. Both LLCs and sole proprietorships are quite common. The business model you choose might have a big impact on how you run your company, especially as seen from the tax, legal, and management perspectives. In this article, you will learn about two major types of business structures - LLC and Sole Proprietorship. We will first discuss each of these business structures individually in brief. Finally, we will share the major differences between the two in regard to structure, function, role of the owner(s), etc. Hence, to learn more about these two types of business structures, read on through to the end of the article. What Is An LLC? According to Investopedia, “A limited liability company (LLC) is a business structure in the U.S. that protects its owners from personal responsibility for its debts or liabilities. Limited liability companies are hybrid entities that combine the characteristics of a corporation with those of a partnership or sole proprietorship.” The LLC is basically a corporate structure where the owners of the organization protect their place from the liabilities of the company. Here, the company is a different entity from that of the owner. In case of debts, liabilities, and lawsuits, the structure of the organization protects the owners by making them limitedly liable. However, what the regulation of the LLC is depends on the state in the US where your business is located. Apart from banks and insurance companies, any individual or entity can be a member of an LLC. Whatever profits LLCs make, they do not pay taxes directly on the profits. The profits and losses of the LLC are passed through to members of the organization, that report on their individual tax returns. Read More: Micro vs Macro Economics: What’s The Difference? What Is A Sole Proprietorship? According to the Forbes Advisor, “A sole proprietorship is an unincorporated business that’s owned by the individual running it. A sole proprietorship is the default choice for anyone who runs a business but hasn’t set up another formal business structure like an LLC. As a sole proprietor, there’s no separation between your personal and business assets and expenses. You are personally responsible for all your business’s debts and obligations.” This is the simplest form of business. It is basically an unincorporated business with only one owner. Apart from that, this business is also the least expensive to form. A business, by default, is a sole proprietorship if an individual operates the business on his own. For example, if you are an individual shopkeeper, freelancer, retailer, or online business owner, you automatically become a sole proprietor of the business. In this case, you will not need to adopt a business structure from the first. Furthermore, if the name of the business is the same as the name of the owner, then the business is typically a sole proprietorship. However, any sole proprietorship can also operate under a trade name or a brand name. The best thing about a sole proprietorship is that the business and the business owner are not legally separate. Hence, if the business incurs debts, the owner of the business is personally responsible for making the payments for the debt. LLC Vs Sole Proprietorship: What Are The Differences? The major difference is rightly noted by Wall Street Mojo - “LLC is a separate legal entity run by its members having limited liability, and it is mandatory for an LLC to get registered, whereas sole proprietorship is a sort of business arm of an individual which is not separate from its owner; hence its liabilities are not limited, and there is no need to register sole proprietor.” The following are the major differences between LLCs and sole proprietorships: Limited Liability CompanySole ProprietorshipThe company has more than one owner.A single owner of the business runs a single unit.The business and the members are separate entities in an LLC structure.The business and the owner are not separate in a sole proprietorship.The members of the business need to register as per state regulations if they want to form an LLC.The owner of a sole proprietorship needs to ensure that the business name is not the same as another business in the state.It costs around $100 to $800 to form an LLC.There are no costs to form a sole proprietorship.The taxation method is single. A single applicable rate is charged to the members.The taxes of the sole proprietorship are charged from the income of the sole owner. The owner’s taxes and the business taxes are the same here.The members of the LLC are liable only as far as their investments and shares in the business.The owner of a sole proprietorship is fully responsible for the entire business. Furthermore, the owner also does not get liability protection.There is little paperwork to be done.There is no paperwork involved. The best option for you, if you are starting out as a business owner, is to go with a sole proprietorship. If you want to grow a bit more, then changing the structure of your business to an LLC will be a better option. Read More: Vertical vs Horizontal Integration: What Are The Key Differences? Final Thoughts LLC vs Sole proprietorship - Hope you have understood the differences between these two types of business structures. If you are starting out as a business owner, consultant, or freelancer, then sole proprietorship is the easiest and simplest option for you. The paperwork that is required is very minimal, and there are no big costs associated. However, if the business grows bigger and you need legal protection for yourself and your personal assets, LLC is the option to go for. In case of bankruptcy or a legal lawsuit against the business, you do not get involved. Furthermore, there is tax flexibility too. What do you think is the better option of the two? Share your opinions with us in the comments section below. Discover More Business Insights Below! What Is Net Operating Income? How To Calculate NOI? Vertical vs Horizontal Integration: What Are The Key Differences? What Is A Holding Company? – Importance, Operation, And Pros & Cons
Oct 25, 2023
What Is A Sales And Purchase Agreement For Business? – Let’s Find Out
A sales and purchase agreement for business is a binding legal contract that consists of conditions both the buyer and seller of a business or property agree upon. In any sale process, it is one of the main legal documents. It basically sets out the elements that are agreed upon in a business deal. It also consists of the number of protections of both parties as well as the legal framework for the completion of the sale. In this article, you will learn about the sales and purchase agreement (SPA) and some of its general details. Apart from that, you will also learn about how the sales and purchase agreement works for businesses. In addition to that, we will also discuss the major constituents of a sales and purchase agreement that all the parties in a sales process need to consider. Hence, to learn more about the SPA, read on through to the end of the article. What Is A Sales And Purchase Agreement For Business? According to Investopedia, “A sales and purchase agreement (SPA) is a binding legal contract between two parties that obligates a transaction to occur between a buyer and seller. SPAs are typically used for real estate transactions, but they are found in other areas of business. The agreement finalizes the terms and conditions of the sale, and it is the culmination of negotiations between the buyer and the seller.” In the case of the trading of a product or a service between two parties, there is a need for a legally binding contract that outlines the details of the agreement. This is called the sales and purchase agreement, and both parties (the buyer and the seller) need to sign the agreement contract. Furthermore, neither of the parties will be able to disobey the contract at any cost. Otherwise, it might lead to legal action. However, it is not an obligation for either of the parties to stay on the deal in question if one of them disagrees with the deal. Once both parties sign the agreement, they will need to follow the terms of the translation. Some of the essential things that are present in this agreement include - terms and conditions, purchase price, deposits made, limitations, closing date, contingencies, etc. How Does A Sales And Purchase Agreement (SPA) Work? According to Wall Street Mojo, “The sales and purchase agreement of business signifies the culmination of negotiations between the buyer and seller and restricts them from ditching each other. The two parties mutually agree upon it before signing it and making it legally binding. It does, however, require both parties to read the contract carefully and seek legal counsel before deciding whether or not to sign it or request a revision.” The sales and purchase agreement occurs mostly in real estate deals, stock purchases, mergers & acquisitions, advertising contracts, etc. On the other hand, the constituents of the SPA include its purchase price, settlement date, deposits paid during the negotiation process, limitations, contingencies, and many more. Apart from that, in such an agreement, both parties in the sales process need to agree to the contract after thoroughly reading it. For this, a business needs to obtain legal advice after signing it and requesting a change. The agreement, basically, provides protection to the interests of both parties. Apart from that, it also restricts them from working against each other or moving away after signing the deal. This factor helps in minimizing potential conflicts and helps to forecast demand and costs of business. What Are The Constituents Of An SPA? According to the Corporate Finance Institute, “Essentially, the sale and purchase agreement spells out all the details of the transaction so that both parties share the same understanding. Among the terms typically included in the agreement are the purchase price, the closing date, the amount of earnest money that the buyer must submit as a deposit, and the list of items that are and are not included in the sale.” 1. Asset Identification Here, you will get information about the specific asset that is subject to sale. In the case of a real property, the location and other details of the asset are jotted down. 2. Purchase Price and Conditions It consists of the exchange price of the transaction in question. Apart from that, the agreement also contains details about how much is already paid and how much is left. It also contains information about the way that the deposit is to be made. It also outlines how the buyer will pay the remaining balance of the transaction. 3. Due Diligence There is a section in the agreement that asks the buyer to acknowledge their due diligence in the transaction. It also contains the due diligence period, which might contain additional payments. 4. Covenants/Conditions Prior to Close The agreement also contains the next steps of the transaction process. The conditions here must be in order to make the sales process legally binding. If the parties fail to follow or if there is any inaction, then it amounts to a breach of contract. 5. Damages/Remedies In some cases, the parties need an explanation regarding what to do in case of damage prior to the sale or during the transit of a product. Hence, this section consists of various levels of damages that can occur to the asset. As per each damage, there is a remedy present. Final Thoughts Hope this article was helpful for you in getting to know about the sales and purchase agreement (SPA). A sales and purchase agreement for a business is a legally binding contract that consists of the conditions set by the buyer and seller, which both agree upon. SPAs are mostly common in real estate dealings, in which the item of transaction is large and includes a big amount. The SPA basically consists of various important information about the sales deal that includes the prices of the asset, the sales price, as well as the payment terms of the sales. It also consists of information about the due diligence period and the agreed-upon conditions. Do you have any more info to add? Share your ideas with us in the comments section below. Go For The Best And Latest Business Related Articles By Clicking Below!! What Are Articles Of Incorporation? – Importance, Working, And More Inventory Turnover Ratio: Definition, Formula, Working, And More What Are Articles Of Organization? – Let’s Find Out
Nov 10, 2023
Business Deductions And Tax Planning: Two Critical Steps To Save Money
As the owner of a company, doing tax planning is an essential part of sound financial management. Locating and making the most of all available company deductions is one of the most important aspects of tax preparation. Your overall tax liability will go down as a result of the reduction of your taxable income brought about by deductions. Continue reading to find out about some potential tax write-offs and deductions for your business that you may be overlooking, as well as some suggestions on how you might utilize these opportunities to reinvest in your company. Understanding Businesses Deductions And Tax Planning Steps For businesses are costs that are directly relevant to the running of a firm. When calculating your taxable income, these expenditures may be subtracted from the money generated by your firm. Expenses that are regular and essential, as well as those that are considered capital, may be deducted from a business's income. 1. Locating And Making A Claim For Tax Deductions It is essential to maintain precise records of your company's costs to properly identify and account for tax deductions. The Internal Revenue Service mandates that all expenditures must have supporting paperwork and receipts. Knowing which deductions you are eligible to claim is also very important since certain costs could not be deductible at all. 2. Utilize The Available Tax Breaks The qualifying business income (QBI) deduction allows owners of pass-through businesses to take a deduction equal to up to 20% of their share of the firm's income. However, this deduction is subject to several regulations and limits and does not come without restrictions. Figuring out who is eligible to claim the QBI deduction and then determining the amount of the deduction itself is not a straightforward operation. However, the deduction may offer a large tax break for owners of small businesses. If you believe you could qualify for this, you should discuss it with your accountant. 3. Investigate Different Ways To Cut Down On AGI Your adjusted gross income, often known as your AGI, is a primary factor in determining the taxes that you must pay. For instance, if your adjusted gross income (AGI) is less than $200K, or if you are married, your AGI is less than $250K, then you will not have to pay the extra 0.9 percent in Medical taxes. You may reduce your AGI by the below methods or by lowering your salary: For example, by registering a company in the US we can obtain some benefits. Making contributions to a retirement plan that postpones paying taxes until later. Using the itemized deductions method if your total deductions are more than the standard deduction. Making contributions to a health-related savings account If you have any reason to believe that you will wish to itemize your deductions, you might think about keeping track of them on a spreadsheet throughout the year. 4. Learn To Leverage Tax Credits Tax credits are an additional method that businesses may use to reduce the amount of tax liability they are responsible for paying. Tax credits, in contrast to tax breaks, which lower the level of cash that is subject to taxation for a person or corporation, reduce the percentage of tax that is actually owed by the taxpayer. It is in the best interest of businesses to benefit from tax benefits. Consider the following few options: Credit for work opportunities offered: Access credit for the disabled: Tax breaks for health insurance premiums paid by employers with less than 25 employees 5. Delay Or Accelerate The Receipt Of Income When it comes to their financial records and tax filings, many small firms rely on cash. When using this cash method a business records revenue and costs at the time that the corresponding cash transaction takes place. So, it means records are taken when the cash changes hands. This opens up some intriguing possibilities for tax planning tactics. You could wish to delay receiving income until the next year if you believe that you will be in a reduced tax band the following year. 6. Purchase Assets At The End Of The Year In certain tax years, it can be helpful to estimate the amount of taxes your company will owe, and then to acquire assets, both new and already used, to lower those estimated taxes. 7. Pay Student Loans Of Workers Employers are now permitted to provide financial assistance to their workers in the form of student debt repayment via a clause that was included in the CARES Act 2020. This Act contains a condition that permits companies to claim a tax exemption for repaying employee student loans and eliminates it from employee income, which means that workers do not have to pay required taxes on the money. 8. Work With Independent Contractors If you engage independent contractors or freelancers for any reason linked to your company (for example, taking images of things for your online shop), you can deduct the cost of their services from your taxable income. Before independent contractors begin working for you, you should always make it a point to gather their 1099 forms and ensure that you file them correctly. 9. Reconsider The Type Of Business Entity Your choice of business entity has a big influence on the amount of Taxes You Will Owe. People who are self-employed and must pay self-employment taxes include those who operate their businesses as sole proprietorships, limited partnerships, or certain limited liability companies. If you anticipate that your company will owe a significant amount of money in taxes, one solution to this problem is to restructure your company so that it is treated as a different kind of legal organization. Last Words: Why Is It Important For Businesses To Plan Their Taxes? You are required to pay taxes as the owner of a company, but the amount that you owe should never come as a complete shock to you. It is crucial to understand how company taxes operate and to make estimations of the amount you need to pay each quarter or year to guarantee that you have sufficient funds. Tax planning is something that can help you generate correct tax predictions, make all tax forms and reports on time, and avoid the possible ramifications of not doing so. Planning your taxes properly may help you achieve all of these things. Read Also: How To Start A Logistics Company? An Expert Guide Biggest Stock Market Crashes In The World History 10 Best Investment Apps For 2021
Feb 20, 2023
12 Passive Income Ideas To Get You Rich In 2023
Some of the major passive income ideas include investing, side hustle, creative work, and more. A passive income is an income that you do not earn, and you generate differently. Passive income puts money in your pocket even when you are not working. You will not need to do active work while you are income passively, unlike the case where you are a traditional employee or a full-time entrepreneur. In this article, we will discuss different ways to make passive income in 2023 as we give you the twelve best passive income ideas. Along with the passive income ideas, we will also give you a brief explanation of how you can implement the idea for yourself. Hence, to learn about these extra income ideas, read on through to the end of the article. Passive Income In 2023 – A General Overview To earn passive income, you will not need to spend a lot of time, money, and resources. According to Forbes.com, “Passive income helps you earn a little extra. Every penny earned matters, and you can deploy the funds to build an emergency fund, start a systematic investment plan in mutual funds, etc.” In passive income, you can earn money by doing projects and making products with little work and essentially no maintenance. This is the money that you are earning from the assets that you control. However, you must note here that it requires some effort at the start, but as you progress, you will have little to no effort. Furthermore, with progress, you will not need to invest a lot of your time. According to an article in Time Magazine, "The cash stream from sources of passive income requires some upfront work, but once established, takes little to no time to maintain. While it can take some time to see the fruits of your labor pay off with passive income, earning money without regular work is possible.” Passive income helps to raise your income level by providing you with extra income options. Although there is a small investment in some cases, it is only one-time. You will not need to participate and devote a dedicated number of hours to the work. However, there is a need for maintenance in passive income, which is not a requirement in any regular income. On a side note, check out some of the best lead management software systems available in 2023 if you are into marketing and sales. The Best Passive Income Ideas For You In 2023 Here are some of the best passive income strategies that you can tryout if you are looking to start with a passive income in 2023: 1. Dropshipping Business Although one requires a little cash, you don't need a lot to start a dropshipping business. Here, to sell a product to a particular customer, you do not need to manage products physically. 2. Blogging It is the most tried and tested passive income that many people tried and got successful. However, it has a lot of competition. So, if you want success, try to be unique and simple. 3. Printing On-Demand If you are creative or understand designs, you can start an on-demand print store, as you can monetize your creativity by printing T-shirts, posters, backpacks, mugs, papers, and more. 4. Online Tutorial If you have knowledge of any subject or skill, you can start an online tutorial regarding the same. You can create video tutorials and create a package for learners to learn from. 5. Selling Digital Products To sell digital products, you will have to create your assets (digital products) once, and then you can sell the product to as many people as you want with your online business. 6. Dealing With Rental Property This is an ancient way of having a passive income. However, you will need to have the capital to buy properties that you will rent to others. The income level is also high. 7. Investment In Businesses And Stocks The most popular source of passive income is investments in stocks and business-related investments. However, investing in stocks requires heavy speculation skills, which you will need to develop. Off-topic: Are you looking to start a startup? Once you open a startup, you will need to consider having your startup insured. To check the best startup insurance options, click on the given link. 8. Affiliate Marketing According to Shopify.com, “a great source of passive income because you earn a commission whenever someone uses your referral link to buy the recommended product or service.” All you need is to recommend the product. 9. Social Media Influencer If you are good at social media, and have the confidence to influence a many audiences with your social media content, then this idea can do wonders for you. 10. Starting A YouTube Channel You can start a YouTube channel about anything that you know. Some of the best ideas, in this case, include – tech reviews, gaming videos, entertainment, tutorials, and many more. 11. Create A Digital Guide A digital guide can be about anything, from travel guides, tutorials, University suggestions, and more. You can create a digital guide once, and you can sell it to as many people as you like. 12. Design And Sell Websites If you are a website designer, then you can sell your designs to companies to earn. Furthermore, if you can code, then you can make full-working websites and sell them to customers. Summing Up One of the most underrated things about passive income is that it is the result of hard work and repeatedly working on the same thing. The more you work, the better returns it will offer you in the future. Once you add one of these passive incomes to your life, you will have better flexibility in work, more freedom, and better earning. Choose the one that suits your character and skills, and work on it consistently, to ensure future results. Do you have any other passive income ideas that you think can work amazingly in 2023? Share some of them with us in the comments section below.
Jul 11, 2023