Stakeholder Vs Shareholder: Differences, Functions, Importance, And More
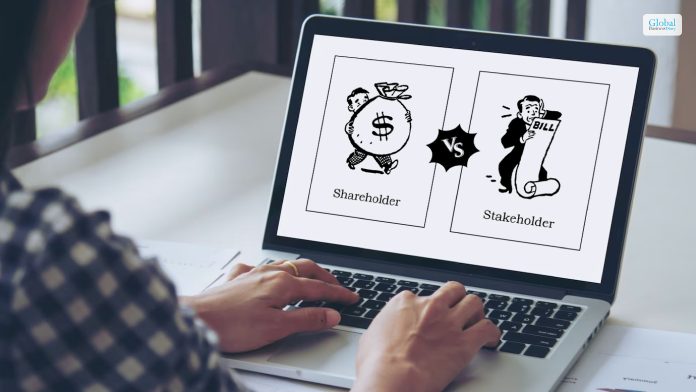
Stakeholder vs shareholder: What is the difference? – You will come across both these terms in the world of investing. There are stakeholders and shareholders in a corporation. While their names might look similar, their functions within a company are not. All shareholders of a company are its stakeholders, while all stakeholders are not necessarily shareholders. Shareholders own stock, while all stakeholders do not own stock.
In this article, you will learn about the differences between shareholders and stakeholders. However, before that, we will give you a general overview of both these terms and their significance in the context of investing. Apart from that, we will also discuss the importance of both these roles in a business, as well as the major functions that these roles require. Hence, to learn more, read on through to the end of the article.
Stakeholder Vs Shareholder: A General Overview
According to Investopedia,
“A stakeholder is a party that has an interest in a company and can either affect or be affected by the business. The primary stakeholders in a typical corporation are its investors, employees, customers, and suppliers. However, with the increasing attention on corporate social responsibility, the concept has been extended to include communities, governments, and trade associations.”
In general, stakeholders have a vested interest in a company’s performance. Stakeholders can affect or can be affected by the performance of a corporation. Stakeholders include investors, shareholders, employees, suppliers, customers, governments, trade associations, or communities. Hence, you can see that the stakeholders of a business can be both inside and outside of the organization.
On the other hand, according to Squareup.com,
“The dictionary definition of a shareholder, also known as a stockholder, is a person who holds at least one share in a company. They’re not the same as a stakeholder though – this is someone who has an interest but doesn’t necessarily hold shares. Being a shareholder confers certain rights and responsibilities such as voting rights and the right to receive dividends if the company makes a profit.”
You can see from the aforementioned definition that a shareholder owns a part of a public company through shares of stock. A shareholder is a stakeholder, but a stakeholder is not always a shareholder. A shareholder is not part of the day-to-day operations of the business, as these functions are the responsibilities of the directors, management, and employees of the company.
[N.B.: If a shareholder owns more than 50% of the stock of a corporation, then he is a majority shareholder. However, if the shareholder owns less than 50% of the stock of a corporation, he becomes a minority shareholder.]
The Importance And Functions Of Stakeholders
According to the Corporate Finance Institute,
“A stakeholder is a party that has an interest in the company’s success or failure. A stakeholder can affect or be affected by the company’s policies and objectives. Stakeholders can either be internal or external. Internal stakeholders have a direct relationship with the company either through employment, ownership, or investment.”
Stakeholders are basically those people who affect the company, or the company affects them. These people have a “stake” in the company’s success and failure. A shareholder can also be a stakeholder. However, a stakeholder is not always a shareholder. Here are some common examples of stakeholders of a company:
● The employees of the company
● Customers of the company that rely on the company’s ability to provide services
● Shareholders of the company.
● Suppliers and vendors of the company
● Community members who feel the impact of the company’s decisions
● Other promotional activities of the company, including partners in events, promotions, etc.
The Importance And Functions Of Shareholders
A shareholder is an institution, company, or individual that owns at least one share of the company. The company’s growth offers profit to the shareholders. Hence, shareholders are also stakeholders by default. The success of the business interests shareholders since they want to receive the greatest possible return on their investment. When the company performs well, the stock prices and dividends go up, which increases the value of the shareholder’s stocks.
Shareholders also have the right to exercise a vote and affect the company’s management. These people are the company’s owners and are not liable for the debts of the company, as the company is a corporation.
To have shareholders, a company or a business venture needs to become a corporation by filing articles of incorporation.
Stakeholder Vs Shareholder: Major Differences
The following are some of the key differences between a stakeholder and a shareholder:
| Stakeholder | Shareholder |
|---|---|
| They are bound to the company for the long term and are interested in the actions and success of the company. | They might not have a long-term need for the company. |
| A stakeholder can have an ownership stake in the company. | Shareholders can own a part of the company by purchasing stock. |
| The day-to-day decisions of the company impact stakeholders. The actions of the stakeholders also impact the company’s growth. | The day-to-day decisions of the company might not impact shareholders. |
Depending on their relationship with the company, shareholders and stakeholders might have competing interests. For example, shareholders might want a company to maximize its profits by keeping its wages low or using less expensive manufacturing processes. However, this is not good news for employees and the customers of the company.
Both stakeholders and shareholders are important for a corporation. However, if business ownership and management are ethical, they understand that a shareholder’s short-term profit goals might not be a good thing for the company in the long run. Hence, they resort to the Stakeholder Theory.
Wrapping
Stakeholder vs shareholder – Hope this article was helpful to make you understand the differences between these two terms. You can see from the article that all shareholders of a company are stakeholders. However, all stakeholders are not necessarily shareholders. When a company is public, shareholders own stock of the company through shares.
On the other hand, a stakeholder just wants to see the company grow and prosper in the market. Other than stock performance, a stakeholder can also have other reasons to see the company grow. In most cases, stakeholders are often part of a company for a long time. Do you have more points to add? Share them with us in the comments below.
#Disclaimer: The information provided on this blog is for educational and informational purposes only and should not be construed as financial advice. I am not a licensed financial advisor. Any investment decision you make is at your own risk, and you should consult with a qualified financial advisor before making any investment decisions. This site may contain affiliate links, and I may earn a commission at no additional cost to you.
Get High With Business Articles Let’s Check Out!!
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles

LoanTap: Information, Eligibility Criteria, Interest Rates, Review & More
Why does anything have to wait? Especially when you need personal emergency loans for medical urgency; or to meet your business or lifestyle goals. LoanTap is the perfect assistant that gets your loan application approved within 30 minutes, and you get the fund within 6 hours. Sounds interesting? Well, it is. I know it is urgent, but you cannot just take a loan from an outright stranger for a loan provider. Yes, we have our trust issues. But that is what we call being careful and vigilant. So, here is all the info you need to know on LoanTap. What Is LoanTap? LoanTap is a personal loan company that offers instantaneous loans to loan seekers within 24 hours of their application. The process is simple. First, you have to download their application on your device. Then, upload all the documents they require to approve your loan, and the money gets transferred to your account. Does that sound complex? No? They offer customized options for different amounts of loans. And the higher amount and the tenure of the loans actually benefit the applicants in so many ways. Applicants also have the benefit of flexible repayment. You can apply for personal loans, holiday loans, EMI-free loans, house owner loans, rental deposit loans, wedding loans, credit card takeover loans, two-wheeler loans, premium bike loans, electric two-wheeler loans, MSME loans, and more. The process is quick and only a few clicks away. Here, go through the features of LoanTap to understand more about what they have in store for you. Read More: mPokket: Information, Eligibility Criteria, Interest Rates, Review & More LoanTap Features LoanTap is great for instant loans. You will have different advantages for your personal loans applied on the platform User-Friendly Services There is no need to worry if you have zero prior experience of getting a loan. The platform is super easy to use, and you can easily apply for a loan there. People with lower levels of experience and knowledge about borrowing money should have no problem using the platform. No Hidden Charges Associated The whole process of borrowing money from LoanTap is easy and transparent. Borrowers do not have to pay any hidden charges. Once your application is approved, you will not have to go through any additional fees than what is already mentioned. Minimum Documents Required When applying for a loan at LoanTap, you do not have to provide them with lots of your personal documents. They only collect some minimum document requirements for processing your loans. Also, the interest rate for different loans on LoanTap range between 15% p.a. to 24% p.a. However, it also depends upon the applicant’s eligibility. Long Tenure The best part of LoanTap loans is that they offer their borrowers the chance to repay within a long tenure. This flexibility provides the users with long tenures and smaller amounts in payable EMI for the loans. Yes, you will get your loan disbursed within 24 to 36 hours of application. High Loan Amount The disbursement range for the loans you apply for is high. You can apply for different amounts based on your requirements. There are also different types of loans you can apply for. However, the loan amount you can apply for depends upon your income, age, credit score, occupation, employer, work experience, Quick Loan Approval & Disbursement The process for application, approval, and loan disbursement is effortless. You can get your loan transferred with only a few simple clicks. You have to download the LoanTap app and then fill out the information required and wait for your application to be approved. Flexible Repayment When Flexible repayment options are there, you can repay your loan of outstanding amounts after a few months of the amount’s disbursal. You can repay your loan within 6 to 60 months of getting your loan. Eligibility For Loans On Loantap Credit Products Private Limited If you want to avail a loan from LoanTap, you need to fulfill several eligibility criteria. Here are those criteria – The borrower must be 23 years old or older. The maximum age of the borrower is 58 years. The borrower must be a citizen of India. The borrower needs to be a salaried worker at a reputable organization. The borrower should also have a minimum of Rs. 30000 per month. The borrower should also have a minimum of 2 years of experience. Benefits of LoanTap Personal Loans There are many benefits to getting a loan from Loantap funding. Here are some that you might want to know – Loantap pays a high amount in loans. If you fulfill the eligibility criteria, they will disburse the amount you have applied for. Also, you will be able to repay the loan within flexible tenure. Online loan eligibility on the LoanTap platform will let you check whether you are eligible for the loan or not. The process is simple and only takes you a few minutes. You can use the loan calculator and check the interest rate, processing fees, and all the necessary information about the loan you want. There are many repayment options for you to choose from. There are switch, accelerated, and enhancement options for loan repayment. The loan processing time is very instantaneous, meaning you will get your application reviewed, and approved and the loan transferred within a short period of time. The loan application process is basic. The platform’s user-friendly interface makes it even easier. The process starts with the borrower downloading and using the LoanTap app on their phones. These are unsecured loans. As a result, they don’t require you to provide any third-party guarantee. But the company might ask the borrower for third-party collateral under specific circumstances. Read More: Dhani Loans & Services Limited – Background And Services Bottom Line Yes, there are other personal loan providers you can opt for. But LoanTap is among the best when it comes to high-amount loan disbursal under short notice. The quick and simple loan payment process makes it easy for borrowers to get money instantly. However, many borrowers might feel otherwise about the interest rates. But the long tenure and flexible repayment almost makeup for the high-interest rates. If you are thinking of getting a personal loan, you can definitely think of LoanTap. However, you can also call LoanTap for more information through the Loantap customer care number (+91 788 804 0000). Read Also: NIRA Instant Personal Loans: Are They Really Instant? FlexSalary: Information, Eligibility Criteria, Interest Rates, Review & More StashFin Personal Loan Review – Interest Rates, Loan Amount, Eligibility, And More
May 20, 2023
Debtor Ghosting You? Here’s How to Collect the Debt Fast And When to Hand It to Taurus Collections
When a debtor goes quiet, it’s rarely “just busy”. It’s usually a decision to delay, avoid, or test whether you’ll keep pushing. And the longer you let it drag on, the harder it gets to collect. Late payment is not a small-business nuisance in the UK. It’s a cash-flow killer. Over 1.5 million UK businesses are affected by late payments each year, with an estimated £26 billion tied up in late payments at any given time. If your debtor is ghosting you, your goal is simple: move from chasing to collecting, fast. Below is a practical, step-by-step playbook you can use today, plus a clear point where it makes sense to hand the job to Taurus Collections Debt Collection Agency, focused on quick, professional recovery. What “debtor ghosting” usually means Ghosting typically falls into 1 of these buckets: They are stalling for cash-flow reasons and paying whoever shouts loudest. They are disputing the invoice informally but avoiding committing it in writing. They think you will give up, discount, or write it off. They are sliding toward insolvency and prioritising survival spending. The key is to stop treating silence like a communication problem and start treating it like a collections process. Step 1: Get your facts tight before you chase Before you send another “just checking in” email, collect your evidence in 1 place: The signed contract, purchase order, or written acceptance The invoice and payment terms Proof of delivery or completion (emails, job sheets, delivery notes) The full statement of account Any dispute emails or comments (even vague ones) The debtor’s correct legal name and registered address This matters because confidence wins. Wobble on the details and you give them room to wriggle. Step 2: Stop being polite and start being clear Polite chasing keeps you stuck in the maybe pile. Clarity moves you into the pay pile. Use a message that is short, specific, and time-bound: What is owed: £X What it relates to: invoice number and date What you need: payment today or a call today What happens next: late payment action and escalation Example (email or WhatsApp style): You have an overdue balance of £[amount] for invoice [number], due on [date]. Please confirm today that payment will be made by [time]. If we do not hear from you, we will begin formal recovery action. Keep it calm. No threats. Just consequences. Step 3: Make contact harder to ignore If you’re only emailing the accounts inbox, you’re easy to ignore. Go multi-channel in a controlled way: Call accounts payable and ask for the exact payment run date Call the buyer, contract manager, or director who benefits from your work Send a letter to the registered office If appropriate, send a final reminder by SMS or WhatsApp You are not being awkward. You are protecting your business. Small businesses already spend an average of 86 hours chasing late payments. You cannot afford to donate that time. Step 4: Use a 7-day escalation ladder Here’s a simple timeline that works well in the UK. Day 1 Call. Follow up by email summarising what was said. Day 3 Second call. Ask a yes or no question: Are you paying today, or do you need a payment plan? Day 5 Send a Final Demand with a clear deadline (48 hours). Attach the invoice and statement. Day 7 Issue a Letter Before Action (LBA). This is the line in the sand. The mistake most businesses make is waiting 30 to 60 days before getting firm. By then, the debtor has trained you to accept delays. Step 5: Add lawful pressure with interest and costs In many business-to-business situations, you can claim statutory interest on late commercial payments at 8 percent above the Bank of England base rate, unless your contract specifies a different rate. You may also be able to claim fixed late payment compensation depending on the size of the debt (under UK late payment rules). This is not about being punitive. It’s about signalling that delaying payment gets more expensive, not less. If you’re unsure what applies in your case, you can still do the most important thing: put the debtor on notice that you will add interest and recovery costs where legally permitted. Step 6: Neutralise the “fake dispute” tactic Ghosting often comes with a last-minute line like: “We had issues with the service.” Your response should be simple: Ask for the dispute in writing within 24 hours Ask for specific details: dates, evidence, what they want Confirm the undisputed amount is due now Example: If you are disputing the invoice, please set out the exact reasons in writing within 24 hours, including evidence. Any undisputed amount remains payable immediately. This stops vague objections becoming a permanent excuse. When to hand it to Taurus Collections You do not need to chase forever. In fact, you shouldn’t. As a rule, consider handing it over when: The invoice is 14 to 21 days overdue and communication has gone quiet You’ve chased 3 times with no firm payment date The debtor promises payment, then breaks the promise You’re spending more time chasing than the profit is worth You suspect the debtor is paying others first You want to preserve the relationship by keeping emotion out of it This is where Taurus Collections fits neatly: you stop being “the supplier who keeps asking” and the situation becomes “a formal recovery process”. Taurus Collections positions itself as a UK-wide debt collection company with fast recovery and options like No Win No Fee and outsourced credit control, which is useful when you want results without building an internal collections function. Why escalation works faster when a professional steps in A debtor can ignore you because there’s no immediate consequence. Professional collections changes the psychology: Your request becomes a demand with structure and deadlines Communication is logged, consistent, and persistent The debtor realises you are prepared to take the next step And crucially, it protects your headspace. Late payments are estimated to cost the UK economy almost £11 billion per year, and thousands of businesses close each year because of overdue invoices. You cannot treat this like an admin. It’s survival. Next steps If a debtor is ghosting you, you do not need more patience. You need a tighter process. Get your documents straight, set firm deadlines, switch channels, issue an LBA, and add interest and costs where applicable. If you hit silence, broken promises, or endless excuses, hand it to Taurus Collections so you can focus on running your business while the recovery is handled properly. Feature Image Source: tauruscollections.com Read Also: Need Help with Tax Debt? Check Out These Relief Options
Jun 09, 2026
What Is The Current Ratio Formula? – Meaning, Interpretation, And More
The current ratio formula is used to calculate the current ratio of a business, This ratio gives an idea of the company’s capacity to repay its short-term loans that are due within a year. This ratio is really helpful for investors as it tells them about the company’s ability to meet its financial obligations. The investors thus evaluate whether the company is financially sound as compared to other competitors and stocks. ‘In this article, you will learn about what the current ratio means and how to calculate it using the current ratio formula. Apart from that, we will also give you tips on how to interpret the situation of a business using the current ratio formula. You will also learn how the current ratio works in general. Finally, we will discuss some of the major pros and cons of using the current ratio formula to calculate the situation of a business. What Is A Current Ratio? According to Investopedia, “The current ratio is a liquidity ratio that measures a company’s ability to pay short-term obligations or those due within one year. It tells investors and analysts how a company can maximize the current assets on its balance sheet to satisfy its current debt and other payables. A current ratio that is in line with the industry average or slightly higher is generally considered acceptable.” However, if the current ratio of a company is lower than what is expected on average from the industry, this indicates a higher risk of distress or default for the company. On the other hand, if a company has a very high current ratio as compared to its competitors in the same industry, this shows that the company might not be using its assets in an effective manner. There are various other liquidity ratios that investors use to calculate the situation of a company. Unlike other ratios, the current ratio makes use of all current assets and current liabilities. That is why the word ‘current’ is used here. It is also called the working capital ratio. Read More: Disaster Recovery Vs Business Continuity – What Are The Differences? Current Ratio Formula - How To Calculate It? According to Wall Street Mojo, “The current ratio equation is a crucial financial metric that assesses a company’s short-term liquidity by comparing its current assets to its current liabilities. A ratio above 1 indicates the company can meet its short-term obligations, while below 1 suggests potential liquidity issues. It aids in evaluating a firm’s financial health and ability to cover immediate debts.” Here is the formula with which you can calculate the current ratio of a company: Current Ratio Formula = Current Assets of the company / Current liabilities of the company The current assets of the company are listed in the company’s balance sheet. It consists of the following: Cash Accounts receivable Inventory Other current assets (OCA) that the company expects to liquidate or turn into cash within a year The current liabilities of the company are also listed in the company’s balance sheet. It consists of the following: Accounts payable Wages Taxes payable Short-term debts Current portion of the long-term debt Interpreting Using The Current Ratio Formula Based on the end result of the calculation, it can mean different things for the company. Here is how one can interpret the current ratio based on the results of a company: If the Current Assets of the company are greater than the Current Liabilities, then the Current Ratio is greater than 1. This shows a desirable situation for investors and the company. If the Current Assets of the company are equal to the Current Liabilities, then the Current Ratio turns out to be exactly 1. This shows that the company’s Current Assets are not enough to pay its short-term obligations. If the Current Assets of the company are less than the Current Liabilities, then the Current Ratio is less than 1. This creates a problem for the company since it does not have enough assets to pay for its short-term obligations. Investors mostly do not prefer to invest in such companies. How Does The Current Ratio Work? According to TheForage.com, “The current ratio describes the relationship between a company’s assets and liabilities. So, a higher ratio means the company has more assets than liabilities. For example, a current ratio of 4 means the company could technically pay off its current liabilities four times over. However, what makes a good current ratio depends on the industry.” In general, if the current ratio of the company stays between 1 and 3, it is an ideal situation for the company to get investments. However, there are certain business models and industries that operate perfectly fine with lower ratios. What Are The Pros And Cons Of Using Current Ratio? The following are some of the major pros and cons of calculating a company’s capability using the current ratio formula: Pros Of Using Current Ratio Here are the major pros of using the current ratio formula: It helps in understanding how cash-rich the company is It helps in gauging the short-term financial health, and stability It gives an idea of the operating cycle of the company and how efficient it is in selling off its products A greater value shows the efficiency of the management Cons Of Using Current Ratio Here are a few cons of using the current ratio formula: It is not sufficient to analyze the financial situation of the company. The inclusion of inventory may lead to overestimation. The ratio can be unstable during seasonal sales period. A change in the inventory valuation method impacts the ratio. Read More: Matrix Organizational Structure – What Are Its Pros And Cons? Wrapping Up Hope this article was helpful for you in getting a better understanding of how the current ratio formula works for businesses. It basically compares all the current assets of the company to its current liabilities. These assets have high liquidity, that is, either they are already cash, or they can be turned into cash within a year. These can also be liabilities to be paid within a year. Calculating the current ratio helps investors get a better understanding of whether a company is able to cover its short-term debts with its current assets. Investors also compare this value with other competitors in the industry. Can you share some more applications of the current ratio formula? Share them with us in the comments section below. Read Also: Why Business Continuity Planning Is Essential For Your Company? Business Risks – How To Identify, Manage, And Reduce Them? The Best Risk Mitigation Techniques For Your Business
Sep 29, 2023

What Do the 2026 SALT, Senior Bonus, and Standard Deduction Changes Mean for Your Taxes?
In high-tax states, taxpayers have waited seven years for meaningful SALT relief. As of 2026, that wait ends now. This is due to the One Big Beautiful Bill Act. This act was signed into law in July 2025. It brings in the most significant overhaul to federal deductions in nearly a decade. Also, there are updated tax brackets, IRA limits, and 401(k) contribution caps. Basically, all these changes entirely reshape the outlook for 2026 wealth management. At the outset, homeowners, retirees, and middle-income earners stand to benefit. That part is clear enough. But it only works if the changes are understood properly and the positioning follows accordingly. Your State Tax Bill Finally Gets Federal Recognition Since 2018, homeowners in places like New York, California, and New Jersey have been dealing with the fallout. In fact, that was when the Tax Cuts and Jobs Act imposed the $10,000 SALT cap, which tightened things more than expected. That effectively penalized residents of high-tax states who previously deducted far more. Meanwhile, the new legislation quadruples that limit. The SALT deduction cap rises to $40,400 for 2026. Also, there are annual 1% increases through 2029. Consider a married couple in New Jersey. State income taxes are at $25,000, and property taxes are another $15,000. That totals $40,000, now fully deductible, which wasn’t the case earlier. Back then, the cap stopped everything at $10,000, cutting off the rest without much room to adjust. There’s a catch, though. High earners start losing the benefit. In 2026, the expanded cap phases down once income crosses $500,000. Around $600,000, it drops back to $10,000, almost like a reset. The provision isn’t permanent either. It sunsets in 2030 unless extended. All of this shifts the calculation. Itemizing starts to matter again, so revisiting earlier assumptions becomes necessary. A Fresh Tax Break Lands Exclusively for the 65-and-Over Crowd Retirees get the flashiest piece here. Maybe the most talked about, too. A new deduction shows up, $6,000 for those 65 and older. Married couples where both qualify can claim $12,000, which feels substantial at first glance, almost unusually generous. It doesn’t come alone. The deduction stacks, which is where things get interesting. Seniors already receive an extra standard deduction, $2,050 for single filers and $1,650 per qualifying spouse. Add the base deduction, and the numbers climb quickly. A single senior can shield $24,150. Joint filers, both over 65, can reach $47,500. The scale shifts quietly but significantly. Data from the White House Council of Economic Advisers suggests 88% of seniors receive Social Security benefits. That’s about 51.4 million people, a wide sweep, though outcomes will still vary. Of course, there are limits to this. In fact, the full deduction phases out above $75,000 for single filers. Meanwhile, for joint fillers, it is $150,000. Moreover, it disappears entirely at $175,000 and $250,000, respectively. Basically, that cutoff matters more than it first appears. One detail stands out. The deduction applies whether itemizing or not. That flexibility changes planning decisions. Seniors with medical expenses or charitable contributions still qualify, and the provision runs through 2028, leaving a narrow window to act. Small Gains Stack Up Over Time With inflation, the standard deduction goes upward for 2026. Although the shift isn’t dramatic, it is still there. Joint filers can claim $32,200, while singles get $16,100. Meanwhile, heads of household earn $24,150. These numbers might feel routine on paper, but they still matter. Individually, the increases seem minor. Easy to overlook, honestly. But they stack over time, slowly, almost quietly. Around 90% of taxpayers take the standard deduction, per IRS data. Over decades, these small adjustments start adding up, shaping outcomes more than expected. Why These Changes Demand a Longer View The first instinct is simple. Take the deduction, lock in the savings, move on. But that approach rarely holds up over time. Durable strategies need a slower, more deliberate kind of thinking. The interaction between provisions complicates things. A senior in a high-tax state now faces multiple pathways: the expanded SALT cap, the $6,000 bonus, and a higher standard deduction. The choice between itemizing and the standard deduction isn’t straightforward anymore. It carries more weight now. Nothing here is permanent. The SALT expansion sunsets in 2030. The senior bonus fades after 2028. Flexibility matters, maybe more than precision, especially with deadlines approaching. Q&A 1. Should I switch from the standard deduction to itemizing in 2026? It comes down to totals, really. Itemizable expenses, all of them together. SALT is now capped at $40,400, not the old $10,000, which changes the math quite a bit. Taxpayers in high-tax states need to recalculate.Itemizing starts to make more sense if the following factors exceed the standard deduction:1. State taxes2. Property taxes3. Mortgage interest4. Charitable contributions. 2. Can seniors who itemize still claim the new $6,000 deduction? Yes. This part stands out a bit. The senior bonus applies either way, itemizing or not. Retirees with high medical costs or charitable giving can claim both, which shifts the calculation slightly. 3. What happens when these provisions expire? When these provisions expire, the SALT cap reverts to $10,000 in 2030. The senior bonus ends after 2028. Building strategies that account for these sunsets makes more sense than assuming Congress will extend them. 4. How do these deductions interact with retirement planning? Timing matters more than it seems. Actually, deductions shift taxable income. This then nudges contribution limits and even Social Security thresholds. When planning connects across these areas, outcomes tend to improve. Read Also: What Is A Schedule 1 Tax Form? What Is Safe Harbor 401K? Benefits And Types Which Describes A Type Of Tax That Funds City Programs? – Let’s Find Out Seven Potential Tax Credits Available To Small Businesses Need Help with Tax Debt? Check Out These Relief Options
Mar 24, 2026