Marginal Cost: Definition, Formula, Examples, And More
Every production in a business has a certain level of expected output. However, in most situations, there is always a change in the quantity of the desired output for the business. This results in an increase or decrease in the total production cost. This change in cost is known as marginal cost. This is a term that is used in economics and managerial accounting. It is a variable unit that depends on the inclusion of resources to enhance production or service.
In this article, you will learn about marginal cost and how it works in the world of accounting. Apart from that, we will also share with you how marginal cost works for businesses, especially during the accounting processes, where we will give you the formula to calculate it. Next up, you will learn more about this term with the help of a simple example. Finally, we will discuss the major benefits of marginal cost.
What Is Marginal Cost?
According to Investopedia,
“In economics, the marginal cost is the change in total production cost that comes from making or producing one additional unit. To calculate marginal cost, divide the change in production costs by the change in quantity. The purpose of analyzing marginal cost is to determine at what point an organization can achieve economies of scale to optimize production and overall operations.”
Here, if the marginal cost of the business to produce one more unit is lower than the price of each unit, it gives the business an opportunity to make a profit. The business will be able to maximize its profits to the point where its marginal cost matches its marginal revenue.
Read More: What Is Continuity In Business, And Why Is It Important?
What Is Marginal Cost Formula?
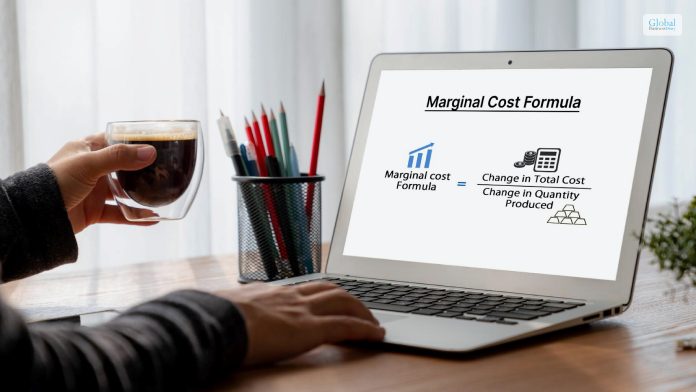
The increase in the total expense that is required to manufacture one additional product is the marginal cost. Hence, you can measure the marginal cost by determining the changes to what expenses are incurred for manufacturing one additional product.
Here is the formula for calculating marginal cost:
| Marginal Cost = Change in Total Costs / Change in the Quantity of Production |
How Does Marginal Cost Work?
According to Wall Street Mojo,
“The marginal costing technique is crucial for any business aiming to optimize the production of goods or delivery of services. The concept technically means extra costs added to the production cost due to additional unit(s). It helps companies determine the selling price of a product or service. Furthermore, they can estimate the desired output by understanding marginal and sales costs.”
Any manufacturing business uses the marginal cost factor to isolate the level of optimum production. Apart from that, manufacturers also examine the cost of adding one more unit to their schedules of production.
There are situations manufacturers face during production where the benefit of producing one more unit and generating revenue from that product will bring down the overall production cost of that product. If the business wants to optimize its costs of manufacturing, it would need to find that point or level as quickly as possible.
The marginal cost in production basically includes all the costs that vary with the change in the production level. Let’s say a company builds a new factory entirely so as to produce more goods. The cost of building the new factory is considered as the marginal cost.
The company that is looking to maximize its profits will try to produce up to a point where the marginal cost of the company is equal to the marginal revenue.
An Example Of The Working Of Marginal Cost
Both fixed costs and variable costs are part of the production. The fixed cost is the one that does not change with an increase in the level of production. Hence, the business spreads out the same value over more outputs as the production increases. On the other hand, the variable cost is the one that changes with the change in the variable output. Hence, when the business produces more units, the variable cost of the production will increase as a result.
You can understand this better with the help of an example:
Let’s consider a company XYZ which makes pencils. Each requires $0.75 of wood and lead. Here, wood and lead are variable costs. The pencil company also has to spend $1000 on fixed costs every month.
If XYZ makes 500 pencils per month, then each pencil takes $2 of fixed costs ($1000/500 pencils). Hence, the total cost per pencil would be $2.75, where $2 is the fixed cost per pencil and $0.75 is the variable cost of one pencil.
Hence, the marginal cost of the company XYZ goes up as a result.
What Are The Benefits Of Marginal Cost?
The following are the major benefits of calculating marginal cost:
- Knowing the marginal cost and marginal revenue of various product lines will allow the company to concentrate resources on products where the difference is higher.
- The business can focus on manufacturing individual units with maximum returns rather than investing in less successful goods.
- The business gets an idea when it is no longer profitable to manufacture additional products.
- It also helps the business to take on additional or customer orders.
However, there are some limitations of marginal costs as well.
According to Indeed.com,
“The limitation of marginal cost is that in real-world examples of the calculation, some costs aren’t easily discernible as fixed or variable, such as overhead costs, which can sometimes be in either category. This can cause some issues with the calculation since variations in how people separate values can change the outcome of the formula.”
Read More: Business Continuity Plan – What Is It, And How Does It Work?
Wrapping Up
You can see from this article that marginal cost is one of the most important terms in accounting. It is the increase or decrease in the total cost of production of the business mainly due to the changes in the quantity of the output that the business desired beforehand. By calculating marginal cost, businesses can optimize their production through economies of scale.
Managers can use marginal cost to make decisions related to resource allocations, optimize production processes, control manufacturing costs, streamline operations, and many more. Do you have anything more to add on how to use marginal cost? Share your thoughts and ideas with us in the comments section below.
Read Also:
Tags:

Recent
Dinmukhamet Idrisov and a Gold-Mine Dispute From Kazakhstan’s Oligarchic Past
Oct 16, 2026

Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

Related Articles
Instant Loan App: Top 25 Best Loan Apps Should You Know In 2023
With the rise in the level of digitization, there has been a simultaneous rise in the number of instant loan apps in the last few years. As per various sources, in the year 2022 itself, the demand for personal loans surged by 50% in the retail industry. However, a very interesting fact is that in the disbursement of personal loans, non-banking financial institutions were on top of banks. In this article, we will mainly discuss the top twenty-five instant loan apps that offer personal loans in 2023. These are the best loan apps that will allow you to avail of loans fast. However, these apps come with different types of service options, and the time of disbursal changes with the app. Hence, to get fully informed, read on through to the end of the article. The Best 25 Instant Loan Apps In 2023 The following are the best instant loan apps that you must look for before you try to avail yourself of personal loans fast in 2023: 1. Earnin If you are qualified to get loans in this app, you can get an emergency loan from this app if you are confident to pay it back. The advances are large. 2. Chime This is one of the best $50 Loan Instant Apps if you are looking for payday loans. However, lenders can still charge high interest. 3. Current The best thing about this app is that there are no overdraft fees associated with it. Furthermore, you can get overdraft protection of $200. 4. MoneyLion You can get an instant cash advance of up to $300 dollars, and you can also be able to access and improve your credit score. 5. Brigit This is one of the best cash advance apps. If you are an eligible member, cash advances are available to you between #50 and $250. 6. Dave This is one of the best $100 loan instant apps that you will come across. Cash advances start here at only $5, and there is also automatic overdraft protection. 7. Spotloan Once you do a SpotLoan login, they will inform you, "It’s an installment loan, which means you pay down the balance with each on-time payment.” It means that it is not a payday loan app. 8. Bright Lending You can get loans from $300 to $1000, but there are also triple-digit APRs, as well as short terms for repayment. 9. Cash App How to borrow money from Cash App? The Cash App borrow loan services allow you to use the app and access loans from multiple devices using the tag “$cashtag”. 10. MoneyLion With the help of Moneylion NYC, you will be able to avail of credit-builder loans without a credit check if you are a member. 11. SoFi The best thing about this loan app is that you can get even $5000 to $100,000 loans and can get your funds on the same day. 12. PayActiv You can get here early paycheck access, and also you will be able to get up to 50% of earned wages before your payday. 13. Even If you are eligible, you can get up to 50% of your earned wages early, and you can get budgeting tools to track your spending as well. 14. Branch Apart from getting 50% of your earned wages early, you will also benefit from no credit checks and zero-cost loans. 15. Grain If you have low credit scores, then this is one of the best loan apps for you. This is also great if you have a short credit history. 16. Vola If you are able to pay a monthly fee, with the help of Vola, you can permanently avoid overdraft fees with the help of instant cash advances. 17. Empower Borrowing a small number of finances can be easy with the help of the Empower Loan App. Furthermore, there are budgeting tools to track expenses. 18. CLEO The app uses AI to help you analyze your spending and help you by giving actionable insights as well. You can also avoid overdraft charges with the help of rewards and auto savings. 19. SoLo Once you apply for a loan here, you will get a soft credit check, which will not affect your credit score. However, based on the credit check, lenders will have a better idea in regards to lending their money to you. 20. Upgrade Personal Loans You can get fast loans with Upgrade, You can get loans up to $50,000. However, there is a high origination fee associated with the borrowing. 21. Varo Apart from being a loan app, this is also a bank account, which gives you an account with a minimum balance with no monthly charges or overdraft. Furthermore, the credit card option is also secure. 22. Albert According to Business Insider, “Albert is a financial app offering automatic savings tools, cash accounts, cash-back rewards, auto-investing, and much more.” However, you can get some customer service issues, as per complaints of borrowers. 23. LendJet Although not a direct lender, you can get access to a variety of lenders through this platform. Hence, it will be easier to look for personal loans from various options. 24. ZippyLoan Like the other platforms, ZippyLoan also offers you to choose from a variety of lenders. You can get loan amounts from $100 to $15,000. 25. Viva Payday loans You can apply for loans in this app without having a credit history for yourself. The loans are hassle-free, and you will get fast approvals as well. Summing Up Hope this list is informative enough to give you a better idea of the best instant loan apps in 2023. If you are trying to avail of fast loans, then you must try one of these apps mentioned above to get the best services. However, we will still recommend you read all the information related to availing of loans. This will give you a better idea of what services are offered by the loan app that you are taking a loan from. Which of the aforementioned loan apps do you think is the best option for you? Share your reviews with us in the comments section below. Read Also About: Credit Card Frauds and What You Can Do to Avoid Them Home Credit: Information, Eligibility Criteria, Interest Rates, Review & More
Apr 20, 2023
Family Budgeting 101: Tools And Tips For Managing Household Finances
If you’re the breadwinner, you’re likely very well aware of the financial challenges of raising a family. From staying on top of bills to keeping your kids healthy and happy, there’s a constant push-and-pull of financial responsibilities that requires constant analysis on your part to resolve. In some cases, it can feel all too easy to just buckle down and fall behind financially. However, formulating a foolproof family budgeting strategy is indeed a possibility, regardless of how your finances currently stand at present. This can come in various forms, from cutting down on unnecessary costs to using tools to help break down your household’s cash flow. Here are some tools and tips to help you manage your household finances more effectively. 1. Track your budget If you don’t have a budget tracker for your household, prioritize creating one as soon as you can. A financial tracker is one of the easiest ways to get a good look at your finances, whether it’s your income or bills. This is not only useful in a corporate-level setting, but it’s also helpful for households in monitoring their cash movements. Some trackers even enable users to create financial ratios to help provide them with a clearer picture of their financial standing. For instance, some trackers have an emergency fund ratio, a ratio that measures how easy it is for liquid assets to be converted to cash in a pinch. There’s also a savings rate, which is a percentage of how much money you saved over how much you spent on a given period, typically a month. More often than not, budget trackers are used for the simple stuff, namely, inputting your income and expenses. Forming a habit of updating your budget helps keep you mindful of your spending patterns, which can help you make more informed decisions for future spending. 2. Utilise digital tools Technology has seeped its way into every corner of daily life, and in the realm of financial tracking, this is no different. In fact, many software tools and applications today can streamline the budgeting and tracking process, turning what may be minutes or hours of mind-numbing work into mere seconds of computerized processing. This calculator from Westpac is one such tool, among many other budget calculators, that can help you crunch data and project how much money you’ll need before you reach a financial benchmark. Furthermore, some tools can help keep you informed and notified about any issues related to your finances. For instance, some apps can remind you when your latest bills are due. Other apps can also provide an easy-to-read graph of your expense breakdown. Budgeting is a comprehensive activity that involves a lot of moving parts. There’s bound to be a digital app or extension that helps make that one budgeting process much easier and more approachable. Some good budgeting apps to help start you off include Mint, YNAB, and Quicken. 3. Set budget goals Every family has different budget goals that set them apart. Some families may be saving up for a new car, while other families are saving up to buy a new house. A few households may not have such grand purchases in mind and would rather climb out of a hole of debt. Having a goal is important because it gives you a target to aim for. The presence of this goal allows you to reverse engineer your decisions and strategize your financial behavior to actualize that goal. If the financial goal seems like a far-off fantasy, you can start breaking it down into smaller and more achievable chunks. You can establish figure-related milestones, like saving a certain amount each month or lowering your weekly expenditures. By having these short-term goals, you can find it easier to track your progress and adjust your purchase behaviour accordingly. 4. Pay off your debts immediately Financial management isn’t only about saving money and boosting your income—it also requires proper debt management. Debt, on its own, isn’t inherently bad. If you can guarantee that you can pay it on time, then having this infusion of funds in your hands can be used to pay off bills and other critical expenses. That said, having unpaid debt can be disastrous for your financial health. For instance, unpaid credit card and loan dues can incur high interest rates over time. Some loan types may also require borrowers to pay late fees for delayed payments. These can all add up, especially if you let the debt run for multiple months. So as soon as you earn income or receive money, be sure to pay off these debts immediately, starting with the debts that have been around the longest. 5. Uphold family financial values Family financial management is a team effort. You don’t want to be the only one restricting your spending while your spouse and/or children splurge for whatever they want, especially if they’re dependent on your income. As such, you should teach your kid key financial values as early as possible. Teach them the scarcity of money, the value of money, the importance of saving, the importance of holding off from wants, and other healthy money habits. You should also communicate finances with your spouse honestly and openly. Being on the same page is important for not just your financial health, but also your relationship at large. This can promote harmony and stability within the family unit, as well as foster the right foundation for proper money management. 6. Minimise unnecessary spending It’s crucial for all members of the family to commit to lowering their spending. Living below your means can seem tough, but it can be approached in several ways. For instance, instead of buying lunch in the cafeteria or at restaurants, just prepare a packed lunch from home. Also, avoid buying random snacks and drinks throughout the day. You should also look into your monthly subscriptions and see if there are any monthly payments you’re making that aren’t being used. Cancel these unused subscriptions, and urge your family to do the same. Furthermore, find ways you can lower your expenditure by buying things at lower rates. You can use discounts, coupons, and vouchers to lower the cost of products and services that you and your family need. Being proactive and scouring for these discounts through email newsletters or partnered websites can be a good way to score a good deal. 7. Be flexible Here’s a cold, hard truth: things will never always go as planned. Emergencies can and often will happen, and many of these emergencies are capable of wiping a significant portion of your savings away. As such, it’s important to develop contingency plans in your budget in case these events do occur. For starters, you can try to make an emergency fund as a financial cushion in case a sudden bad event happens. Besides that, always be mindful of your and your family’s lifestyle habits and make the necessary financial adjustments. If you find that your savings rate is decreasing month-on-month because of added expenses, for instance, you may have to think hard and reevaluate your budget’s goals. Being flexible is an important value to possess to be able to navigate financial difficulties effectively. Sticking with one goal stubbornly when the situation around you changes can spell your downfall, so be receptive to change and be prepared to call new shots. Read Also: A Brief Guide To Business Integrated Planning Maximizing Tax Refunds: Tips And Tricks For Canadians Seven Potential Tax Credits Available To Small Businesses In 2023
Dec 20, 2023
Strategic Asset Planning For Entrepreneurs And Business Owners
As an entrepreneur or business owner, your assets are a critical part of your overall business strategy. Proper planning and management of assets can maximize their value and contribution to reaching your business goals. It requires taking a strategic approach that aligns your assets with your broader vision. With a focus on practical steps and key insights, this guide aims to equip you with the knowledge and tools needed to make informed decisions about your assets: Understand Your Assets The first step in strategic asset planning is to clearly understand your current holdings, a process crucial for protecting and enhancing your business’s financial health. This evaluation covers a broad spectrum of assets, categorized into two main types: Tangible Assets: These are physical entities you can see and touch, such as real estate, buildings, machinery, and inventory. Each asset is vital in your day-to-day operations, contributing significantly to your organization’s overall value. It’s also important to recognize that these are the properties that can be seized in a judgement, underscoring the need for strategic planning to safeguard against potential financial liabilities. Intangible Assets: Although they may not occupy physical space, intangible assets are equally critical to your company’s success. This category includes intellectual property like patents and trademarks, brand value, customer relationships, and proprietary technology. These assets are key drivers of your competitive edge and positioning in the marketplace, often determining your ability to innovate and stay ahead of the curve. Inventorying your tangible and intangible assets lays the groundwork for successful asset management and growth strategies. Understanding the specifics of these assets is critical to maximizing their potential and aligning them with your business objectives. Such strategic alignment boosts your market position and drives long-term success. Set Clear Goals When setting clear goals, it’s essential to align them with your long-term vision, immediate needs, and the principle of business continuity. This integration ensures that your strategy aims for growth and prepares your organization to maintain operations during unexpected disruptions. Identifying specific, measurable objectives is crucial in guiding your asset management strategies. For instance, if expanding your business is the goal, focusing on acquiring assets that increase your production capacity or market reach is wise. Alternatively, if improving cash flow is a priority, strategies might include optimizing inventory management or investing in assets that generate steady income. Establishing these goals provides a roadmap, guiding every decision about your assets towards your desired outcomes. Assess Risks And Opportunities Effectively managing business risks requires a targeted approach. Here’s how to refine your risk assessment process: Quantitative Analysis: Apply financial modelling to quantify potential impacts on tangible and intangible assets. This helps in understanding the financial exposure of each asset type to various risks. Qualitative Analysis: Use scenario planning to evaluate how external factors, such as market changes or regulatory updates, might affect your assets. This method is particularly useful for assessing risks to intangible assets. Asset-Specific Risks: Tailor your assessment to the nature of the asset. For example, real estate requires analysis of location-specific risks, while intellectual property needs a focus on legal and technological vulnerabilities. Market Monitoring: Regularly review economic indicators and industry trends to adapt your risk management strategies to current conditions. Risk Mitigation Planning: Following assessment, develop strategies to mitigate identified risks. Such may include diversification, insurance, or strengthening legal protections. This streamlined approach ensures a comprehensive evaluation of risks and opportunities, guiding better strategic decisions for asset management. Develop A Diversification Strategy Don’t put all your eggs in one basket. Diversification is essential to mitigating risk and promoting stability. This could mean diversifying your investment portfolio, expanding your product line, or entering new markets. A well-rounded strategy protects against market volatility and ensures multiple streams of income. Here’s how to get started: Invest In Different Asset Classes: Spread your investments across stocks, bonds, real estate, and other asset classes. This approach reduces risk, as different assets perform differently under various economic conditions. Expand Geographically: Consider entering new geographic markets to reduce dependence on a single economy. This can help buffer your business against local economic downturns and tap into new customer bases. Innovate Your Product Line: Regularly introducing new products or services can attract a broader customer base and reduce reliance on a single revenue stream. It keeps your offering fresh and competitive. By implementing these strategies, you create a robust framework that can withstand market shifts and capitalize on emerging opportunities, ensuring your business remains resilient and forward-moving. Optimize Asset Allocation Optimizing asset allocation involves a strategic approach to distributing your resources across various investments and business areas to maximize returns while minimizing risks. This critical step requires a deep understanding of your business landscape, including market trends, financial forecasts, and the competitive environment. By aligning your asset allocation with your long-term business objectives, you can ensure that every dollar invested is working towards the growth and sustainability of your business. It’s about making informed decisions that balance short-term needs with long-term ambitions, ensuring that your assets are preserved and actively contributing to your business’s success story. Plan For Succession For many entrepreneurs and business owners, the business is a legacy. Planning for succession ensures that your hard work continues to thrive, even when you’re ready to step away. Whether it’s transferring ownership to a family member or preparing for a sale, a clear succession plan is a vital component of strategic asset planning. It involves identifying potential successors early and mentoring them to take over the reins. This preparation secures the future of your business and minimizes disruptions during the transition, ensuring a smooth handover of leadership and operations. Regularly Review And Adjust Your Plan The only constant in business is change. Regular reviews of your asset plan ensure it remains aligned with your goals and responsive to market dynamics. This ongoing process allows you to make informed adjustments, seize new opportunities, and navigate challenges with confidence. Conclusion With mindful, strategic asset planning, entrepreneurs and business owners can build, manage and leverage assets to maximize value and drive sustainable growth. Keep assets aligned with your evolving strategy and vision. Be nimble and responsive in acquisition, maintenance and disposition decisions. Your assets will become a competitive advantage. Read Also: Why Business Continuity Planning Is Essential For Your Company? Managing Fixed Assets: Accounting Techniques For Long-Term Success Financial Planning Tips For Different Stages Of Life
Feb 07, 2024
A Boutique Mortgage Lender & The Many Benefits Of Borrowing From Them.
If you are taking the time to read this article, then it’s likely that you are thinking about getting yourself onto the first rung of the property ladder. Buying your first house is a significant investment, and it is likely to be the biggest one that you will make in your lifetime. This means that you have to be careful about the lender that you borrow the money from because it is a little bit of a minefield out there, and as interest rates continue to rise all across the country, many Australians have to take care of the purse strings so that they can try to save themselves money over the course of the mortgage term. This is why people turn to a boutique mortgage broking firm because, unlike what is regarded as normal lending institutions, there are a number of upsides to engaging with a private lender such as this. Let us try to explore the benefits of borrowing money from boutique mortgage lenders. Difference Between Bank And Mortgage Lenders A general question that might crop up in this discussion is why you must reap the advantages of the mortgage lender. The question is quite obvious because people over the ages have considered Banks for loans. This has been the traditional approach to taking loans. At the same time, you must have an understanding. To get into the matter, let us try to find out the difference between the Banks and the mortgage loan providers. Varied Options And Better Knowledge And Guidance The mortgage loan options are more varied compared to that of the banks. It means you can have better loan terms with the former option. Boutique mortgage lenders use their expertise and training to provide you with better options and guidance on the loans, and you will find it manageable enough to understand the minute details of the terms and conditions. Better Negotiations When you ask for a loan from the banks, they will check your credit score and then decide on the terms and conditions of the loan. On the other hand, boutique mortgage lenders discuss and negotiate the terms and conditions of the loans. Even the closing of the loan is way faster in mortgage loans compared to that of traditional banks. Compliance The banks are more strict compared to that of mortgage loans. This is because compliance with the banks is more rigid and stiff than that of the mortgage lenders. Now that there is more compliance, you have to pay more fees to the banks than the mortgage lender. These points discussed above take boutique mortgage lenders to an advantageous position compared to that traditional financial banks. Boutique Mortgage Lenders: How Can They Help You Out? Boutique mortgage lenders offer you different benefits, and they are an advantage if you compare them to similar financial organizations. There will be many different options offered to you when it comes to purchasing your first home, so you need to think about whether or not you want to get pre-approved so that you can be guaranteed the loan. It can be tempting to stick with the bank that you have saved with from when you were a very young child, but you shouldn’t ignore the benefits that borrowing from a boutique lender offers. You Can Get Better Rates Don’t just assume that the high street banks will have the best mortgage rate currently available because many of these private broking firms can offer lower interest rates as well as cheaper fees as well. They are also a good choice for those Australians who don’t have the most detailed credit histories or who don’t have all of the money on hand to put down a significant deposit. You Get A Quicker Decision From the initial application to a high street bank to when you get an answer with regards to approval for your loan, it can take a significant amount of time because these banks have many rules and regulations that need to be followed, as well as lots of red tape. When you engage with a private broking firm, they tend to move things along more smoothly, and this means that you get a decision quickly. Customer-Tailored Financing Options One of the advantages that you can get with boutique mortgage lenders is customer-tailored financing options. If you are looking for a 27-year fixed loan term or a 13-year fixed loan term, you can get such flexibility with these mortgage lenders. Hence, you do not need to be really bothered regarding the financial options. A customer tailor financial option can do it for you. Communication Another benefit that you enjoy with the boutique mortgage lender is communicating loan status updates to each borrower. Different money lenders have specific dates on which they provide detailed information on the status of loans that their customers took. This reminder helps the borrower have a good understanding of the loan status. Generally, the loan process is highly complicated, and with the help of this system, the process gets simplified. You Get More Flexibility When you are dealing with a private lender, they want to give you the mortgage that you need, and so they are incredibly flexible when it comes to the documents that have to be supplied and the forms that need to be filled in. The other selling point is that they deal with you as an individual, and they value being able to do business with you. They try to make the whole mortgage process so much easier, and you will always have access to your broker, who will take you through the whole process so that things seem a lot simpler. It makes sense that you would want to deal with a private lender who treats you like a customer rather than just a number. Conclusion Boutique Mortgage lenders offer different benefits to their customers and cooperate with them. They offer features and benefits that help process loans faster. Moreover, these lenders offer varied offers and flexible terms to their customers. You can seek advice from the experts to have clarity on the matter to understand the particular advantage. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Jun 16, 2023