What Is The Current Ratio Formula? – Meaning, Interpretation, And More
The current ratio formula is used to calculate the current ratio of a business, This ratio gives an idea of the company’s capacity to repay its short-term loans that are due within a year. This ratio is really helpful for investors as it tells them about the company’s ability to meet its financial obligations. The investors thus evaluate whether the company is financially sound as compared to other competitors and stocks.
‘In this article, you will learn about what the current ratio means and how to calculate it using the current ratio formula. Apart from that, we will also give you tips on how to interpret the situation of a business using the current ratio formula. You will also learn how the current ratio works in general. Finally, we will discuss some of the major pros and cons of using the current ratio formula to calculate the situation of a business.
What Is A Current Ratio?
According to Investopedia,
“The current ratio is a liquidity ratio that measures a company’s ability to pay short-term obligations or those due within one year. It tells investors and analysts how a company can maximize the current assets on its balance sheet to satisfy its current debt and other payables. A current ratio that is in line with the industry average or slightly higher is generally considered acceptable.”
However, if the current ratio of a company is lower than what is expected on average from the industry, this indicates a higher risk of distress or default for the company. On the other hand, if a company has a very high current ratio as compared to its competitors in the same industry, this shows that the company might not be using its assets in an effective manner.
There are various other liquidity ratios that investors use to calculate the situation of a company. Unlike other ratios, the current ratio makes use of all current assets and current liabilities. That is why the word ‘current’ is used here. It is also called the working capital ratio.
Read More: Disaster Recovery Vs Business Continuity – What Are The Differences?
Current Ratio Formula – How To Calculate It?
According to Wall Street Mojo,
“The current ratio equation is a crucial financial metric that assesses a company’s short-term liquidity by comparing its current assets to its current liabilities. A ratio above 1 indicates the company can meet its short-term obligations, while below 1 suggests potential liquidity issues. It aids in evaluating a firm’s financial health and ability to cover immediate debts.”
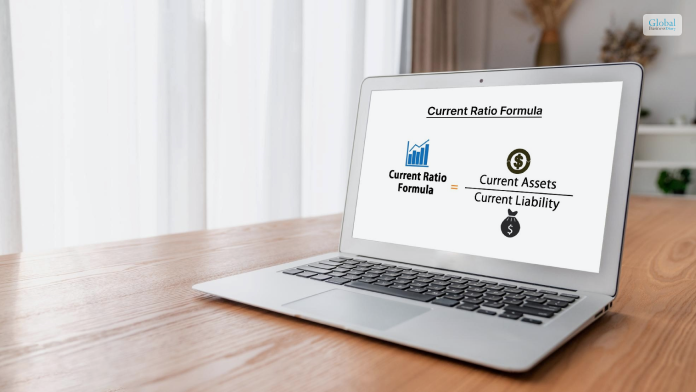
Here is the formula with which you can calculate the current ratio of a company:
| Current Ratio Formula = Current Assets of the company / Current liabilities of the company |
The current assets of the company are listed in the company’s balance sheet. It consists of the following:
- Cash
- Accounts receivable
- Inventory
- Other current assets (OCA) that the company expects to liquidate or turn into cash within a year
The current liabilities of the company are also listed in the company’s balance sheet. It consists of the following:
- Accounts payable
- Wages
- Taxes payable
- Short-term debts
- Current portion of the long-term debt
Interpreting Using The Current Ratio Formula
Based on the end result of the calculation, it can mean different things for the company. Here is how one can interpret the current ratio based on the results of a company:
- If the Current Assets of the company are greater than the Current Liabilities, then the Current Ratio is greater than 1. This shows a desirable situation for investors and the company.
- If the Current Assets of the company are equal to the Current Liabilities, then the Current Ratio turns out to be exactly 1. This shows that the company’s Current Assets are not enough to pay its short-term obligations.
- If the Current Assets of the company are less than the Current Liabilities, then the Current Ratio is less than 1. This creates a problem for the company since it does not have enough assets to pay for its short-term obligations. Investors mostly do not prefer to invest in such companies.
How Does The Current Ratio Work?
According to TheForage.com,
“The current ratio describes the relationship between a company’s assets and liabilities. So, a higher ratio means the company has more assets than liabilities. For example, a current ratio of 4 means the company could technically pay off its current liabilities four times over. However, what makes a good current ratio depends on the industry.”
In general, if the current ratio of the company stays between 1 and 3, it is an ideal situation for the company to get investments. However, there are certain business models and industries that operate perfectly fine with lower ratios.
What Are The Pros And Cons Of Using Current Ratio?
The following are some of the major pros and cons of calculating a company’s capability using the current ratio formula:
Pros Of Using Current Ratio
Here are the major pros of using the current ratio formula:
- It helps in understanding how cash-rich the company is
- It helps in gauging the short-term financial health, and stability
- It gives an idea of the operating cycle of the company and how efficient it is in selling off its products
- A greater value shows the efficiency of the management
Cons Of Using Current Ratio
Here are a few cons of using the current ratio formula:
- It is not sufficient to analyze the financial situation of the company.
- The inclusion of inventory may lead to overestimation.
- The ratio can be unstable during seasonal sales period.
- A change in the inventory valuation method impacts the ratio.
Read More: Matrix Organizational Structure – What Are Its Pros And Cons?
Wrapping Up
Hope this article was helpful for you in getting a better understanding of how the current ratio formula works for businesses. It basically compares all the current assets of the company to its current liabilities. These assets have high liquidity, that is, either they are already cash, or they can be turned into cash within a year. These can also be liabilities to be paid within a year.
Calculating the current ratio helps investors get a better understanding of whether a company is able to cover its short-term debts with its current assets. Investors also compare this value with other competitors in the industry. Can you share some more applications of the current ratio formula? Share them with us in the comments section below.
Read Also:
Tags:

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
Fullerton India Review: Things To Know Before Taking A Loan!
Nowadays, if you are in need of money, whether it's for personal uses or for your business, getting it instantly is a major convenience. Therefore, many new loan institutions are cropping up globally. One such company from India that I am going to discuss is Fullerton India Ltd. To learn more about this Kolkata-based company, read this post till the end! Fullerton India: Company Overview Fullerton India credit company Ltd is a new finance company originating from Kolkata, India. With its headquarters in Park Street, they have managed to gain a lot of traction lately by providing instant loans to people and businesses. One of the primary reasons they have become popular is because of how easy it is to get approved loans from Fullerton. Plus, their loan application processes are easy - you can do them entirely online if you wish to! In addition, you don’t need a Fullerton India credit company limited account! Fullerton is similar to other Indian financial institutions like Navi, PayMe India, and LoanTap. Fullerton India Personal Loans Fullerton India is widely renowned for providing personal loans to account holders at lower-than-average interest rates. As long as you are eligible for Fullerton India personal loans and you are a salaried employee, you will get such loans quickly. All the procedures of this company are completely transparent to ensure that there are no hidden charges or secret terms and conditions in place. In addition, most of the Fullerton loan payment solutions can be customized by you to an extent. Maximum Loan AmountUpto INR 25,00,000Repayment TenureMinimum 12 months, maximum 60 monthsInterest RateStarting from 17%Processing FeesUpto 6% of the total loan amountPrepayment ChargesUpto 7% of the total loan amount Why Should You Apply For Fullerton India Personal Loan? Some of the benefits of applying for a Fullerton India personal loan are: The application process for this loan is 100% digital - no paperwork is required.These personal loans are free of any collateral. Repayment tenures for these personal loans are flexible. Since these are personal loans, the reasons for applying for this loan can be anything. Required Documents To apply for this loan, you need the following documents: A filled application form that is also digitally signed. Identity proof (should contain proof of your address, age, and citizenship) Salary Pay Slips for the last three months Bank statement for the last six months Form 16 Income Tax Returns report Other necessary financial statements and Proof of income (if you are self-employed) Personal Loan Eligibility Criteria You will be eligible for Fullerton India personal loans by meeting these requirements: AgeMinimum 21, maximum 60Employment StatusMust be salaried or self-employedMinimum IncomeMinimum salary INR 25,000Credit Score750+ CIBIL score with a good credit historyNationalityIndianWork ExperienceMinimum 1 year of work experience Fullerton India Business Loans If you are an entrepreneur and you are in need of funds to expand your business, then contact Fullerton India. They have business loans for all types of businesses, both big and small. Not only will these loans help you manage your business capital necessities, but they will also help you manage your capital needs for other purposes. This includes inventory purchases, workspace expansion, marketing, and any other additional payments. Maximum Loan AmountUpto INR 50,00,000Repayment TenureMinimum 12 months, maximum 60 monthsInterest RateStarting from 11.99%Processing FeesN/APrepayment ChargesN/A Why Should You Apply For Fullerton India Business Loan? The primary benefits of applying for loans from Fullerton India home finance company limited are: All the loan facilities provided by the company are flexible since you have a loan repayment tenure of upto 48 months. Such business loans of upto INR 50 lakhs will be provided to you quickly within 24 hours after you apply. There are no collaterals for Fullerton business loans. You can access your loan account online pretty easily. Required Documents To apply for this loan, you will need these documents: A recently clicked photograph of you. Identity proof, like your PAN card. Address proof like your passport. Necessary bank statements Income Tax Report (ITR) files or GST Reports Income proof Business existence proof (like your business’s Certificate of Existence) Business Loan Eligibility Criteria You and your business will be eligible for these loans if you meet these requirements: AgeMinimum 25, maximum 65Business StatusSole proprietorship or partnershipMinimum TurnoverMinimum INR 10,00,000 per annum, with INR 2,00,000 profitCredit Score750+ CIBIL score with a good credit historyNationalityIndianBusiness ExperienceMinimum 3 years of business life with profits in the last two years Other Types Of Fullerton India Loans Apart from the two loans described above, which are the specialty of Fullerton India, they also provide other customizable loans like: Loan Against Property: If you have an immediate expense to clear out as soon as possible, then you can get a loan against your property as collateral instantly! Two-Wheeler Loans: These are short-term loans for purchasing your first two-wheeler! Home Loans: If you wish to purchase that dream house you have been eyeing for some time, you can apply for this loan! Commercial Vehicle Loans: If your business needs a commercial vehicle like trucks and other vehicles, you can apply for this loan! How To Apply For Fullerton India Loans? If you wish to apply for a Fullerton India loan, you have to follow a simple process, which I have described below: First, go to the Fullerton India official website. Here, click on the Apply Now button at the top of the page. Now, out of all the loan options, select the type of loan you wish to apply for. Depending on the type of loan you have chosen to apply for, an application form will open on your screen. Fill it up with all the required details. After you have filled up the application form, click on Next. An OTP will be sent to your registered email ID and phone number. Confirm them by following the on-screen procedures. Now, you must upload scanned copies of the necessary paper documents. After you are done uploading scanned copies, click on Submit. After you hit the final Submit button, Fullerton India will get back to you if your loan is approved in the next 24 hours. Conclusion Fullerton India provides loans to people who are in dire need of them. All you need to do is meet their eligibility criteria and apply for their loans online! Plus, they provide many loans like personal loans, business loans, loans against property, two-wheeler loans, commercial vehicle loans, and home loans to apply for! If you have any queries, please comment below! Read Also: What Is Stockinvest? Is It Legit And Working SmartCoin: Information, Eligibility Criteria, Interest Rates, Review & More StashFin Personal Loan Review – Interest Rates, Loan Amount, Eligibility, And More
May 30, 2023
What You Should Know Before Committing To A Cash Buyer
Cash buyers are becoming increasingly popular in the real estate market. They can make the process of buying or selling a home faster and easier than traditional buyers due to their ability to purchase properties with cash instead of having to go through the lengthy process of getting a loan approved. However, if you're considering working with a cash buyer, there are some things you should know before committing. Benefits of Working with a Cash Buyer Working with a cash buyer has many benefits. The most obvious benefit is that they can help you sell your house fast. They can often close deals more quickly than traditional buyers who may take weeks or months to get financing from a bank or other lender. Also, cash buyers typically have fewer contingencies as part of their offer, which can make it less likely for an agreement to fall through at the last minute due to issues with financing or appraisals. Finally, working with a cash buyer may help you avoid the hassle and expense of commissions, closing costs, and other fees associated with traditional sales. What You Need To Know Before Signing Before signing any agreement with a cash buyer, it's important that you do your research and understands what you're getting into. Here are some key considerations: Make sure that the cash buyer has enough financial resources available to purchase your property in full and on time. Ask for proof of funds such as bank statements or verification from an escrow company before entering into any agreement. Understand all terms and conditions included in the offer including any deadlines for completion or conditions that must be met prior to closing. Make sure these terms are clearly spelled out in writing so there is no ambiguity later on. Ask about the buyer’s track record in completing similar transactions in the past and inquire about references so you can check up on their credibility and reputation within the industry. Ask for an estimate of how long it will take for all paperwork required for closing to be completed, as this will help you plan accordingly for when funds will become available after the completion of the sale. Be aware of any potential tax consequences associated with selling your property quickly at discount prices—this could increase your overall liability so consult your accountant before signing anything! Consider consulting legal counsel if needed—an experienced attorney can ensure all legal documents associated with the sale are properly drafted and signed off on by both parties involved before money changes hands. Final Thoughts Cash buyers can be an excellent option if you need quick access to capital without going through the hassle of finding financing from banks or other lenders—just make sure that you understand all terms associated with the sale beforehand! Doing your research ahead of time by asking questions about their history and experience dealing in similar transactions will help ensure everything goes smoothly during the negotiation process as well as upon completion of the sale itself! Read Also: How Sustainability Sets Up Real Estate Developers For Success Profitable Business Ideas To Start In UAE What Is The Defeasance Clause?-Everything You Need To Know
Mar 09, 2023
Navigating Home Financing: A Deep Dive Into Non-Qm Mortgage Loans
In the realm of mortgage financing, Non-QM (Non-Qualified Mortgage) loans have emerged as a flexible and inclusive option for individuals who may not fit the traditional lending criteria. This comprehensive guide aims to shed light on the intricacies of Non-QM mortgage loans, exploring their definition, eligibility criteria, benefits, and considerations for those seeking alternative paths to homeownership. If you're curious about Non-QM loans and want to learn more, click here. Understanding Non-QM Mortgage Loans What Are Non-Qm Loans? Non-QM loans fall outside the guidelines set by government-sponsored entities like Fannie Mae and Freddie Mac. Unlike traditional Qualified Mortgages (QM), Non-QM loans provide a more inclusive approach to lending by considering a broader range of borrower profiles. Eligibility Criteria For Non-Qm Mortgage Loans 1. Credit Flexibility Non-QM loans are designed to accommodate borrowers with unique credit profiles. Individuals with a recent bankruptcy, foreclosure, or fluctuating income may find Non-QM loans more accessible. 2. Debt-To-Income Ratio Variation While conventional mortgages often adhere to strict debt-to-income ratios, non-QM loans allow for greater flexibility. Borrowers with higher debt-to-income ratios may still qualify based on other compensating factors. 3. Alternative Documentation Traditional mortgages often require extensive documentation to verify income and employment. Non-QM loans, however, may accept alternative forms of documentation, making them more suitable for self-employed individuals or those with non-traditional income sources. 4. Unique Property Types Non-QM loans can be more lenient when it comes to financing unique property types. This flexibility is beneficial for borrowers looking to invest in non-traditional homes or properties. Benefits Of Non-Qm Mortgage Loans 1. Accessibility For Non-Traditional Borrowers Non-QM loans provide an alternative for borrowers who don't meet the stringent criteria of conventional mortgages. This inclusivity extends to self-employed individuals, retirees, and those with unique financial circumstances. 2. Flexible Underwriting Criteria The flexibility of non-QM loans allows lenders to consider a broader range of factors beyond the traditional credit score and debt-to-income ratio, providing more opportunities for approval. 3. Unique Property Financing Borrowers interested in financing unique or non-traditional properties may find Non-QM loans more accommodating than traditional mortgages. 4. Credit Repair Opportunities For individuals with recent credit challenges, Non-QM loans can serve as a stepping stone to homeownership while providing an opportunity to rebuild credit over time. Considerations And Drawbacks 1. Higher Interest Rates Non-QM loans typically carry higher interest rates in contrast to conventional mortgages. It's crucial for potential borrowers to thoroughly assess the long-term financial implications. 2. Potential For Larger Down Payments Some Non-QM lenders may require larger down payments, impacting the initial financial commitment for borrowers. 3. Limited Regulatory Protections Non-QM loans are not subject to the same regulatory protections as Qualified Mortgages. Borrowers should carefully review loan terms and conditions. 4. Variable Loan Terms Non-QM loans may come with variable terms and conditions. Borrowers must understand and assess the specific terms offered by lenders. The Non-Qm Mortgage Loan Application Process 1. Pre-Application Consultation Prospective borrowers should engage in a pre-application consultation with a Non-QM lender. During this phase, the lender will assess the borrower's unique financial situation and discuss available loan options. 2. Documentation Submission Borrowers will be required to submit documentation to support their application. This may include alternative income documentation, proof of assets, and other relevant financial information. 3. Underwriting And Approval The lender will conduct a thorough underwriting process, considering the borrower's unique circumstances. Upon approval, the borrower will receive a loan offer with specific terms and conditions. 4. Property Appraisal As with any mortgage, a property appraisal may be required to determine its value and suitability for financing. 5. Closing And Homeownership Upon completing the necessary steps and meeting any remaining conditions, borrowers can proceed to the closing. This involves signing the required paperwork, officially making them homeowners. Conclusion Non-QM mortgage loans offer a valuable alternative for individuals who may not fit within the parameters of traditional lending. While they come with certain considerations and potential drawbacks, the inclusivity and flexibility of Non-QM loans make them a viable option for a diverse range of borrowers. As with any significant financial decision, thorough research, consultation with non-QM lenders, and a clear understanding of the terms are crucial. If you're intrigued by the possibilities of Non-QM mortgage loans and want to explore more, click here for additional information. Read Also: How To Get Personal Loan On Bajaj Markets Speed Up Your Funding: A Quick Guide To Business Loans What You Should Know Before Committing To A Cash Buyer
Dec 04, 2023

Micro vs Macro Economics: What’s The Difference?
Economics deals with human behavior and its implications on society. This subject is divided into two broad categories known as macro and microeconomics. Micro vs Macroeconomics has lots of factors present within itself. Without an in-depth analysis, you cannot get the core points of differences between the two concepts. So, without an in-depth study of Micro vs Macro economics, things are going to be difficult for you. Microeconomics deals with individual consumers and businesses, whereas macroeconomics deals with the behavior of the aggregate economy. You must know the core differences between the two concepts that can make things easier for you. Economics studies the individual, business, and government allocates resources that can assist you to meet your requirements with ease. What Is Macro Economics? Macroeconomics is the branch of economics that studies the performance and behavior of the economy as a whole. It focuses on the study of the aggregate annual national income of the entire economy within a particular fiscal year. Marginal cost also forms a part of it. What Is Micro Economics? Microeconomics considers the behavior of the decision-makers within a particular economy, such as households, individuals, and firms. Your prime focus would be to find out the core problems of the economy at an individual level. A holistic approach is not required here. What Is The Difference Between Micro vs Macro Economics? There are several points of difference between Macro and microeconomics that you must know at your end. You should go through the differences that can assist you in getting the core points of differences between Micro vs Macro Economics. The trial balance also shows the impact of these two concepts. Basis Of ComparisionMicro EconomicsMacro EconomicsMeaning Microeconomics is that branch of economics that deals with household, individual, and firm behavior analysis at the time of allocation of resources. It comprises the goods and services of the market and deals with the issues in their economy. The Macroeconomics deals with the complete behavioral study of the economy and its performance in total. Important areas of study in the case of Macroeconomics are GDP, growth rate, inflation, and unemployment. Area Of Study It studies a specific market segment of an economy. It studies the entire economy and covers the market as a whole. Deals With Microeconomics deals with multiple issues like factor pricing, product pricing, demand & supply position, production, consumption, and economic welfare. Macroeconomics deals with various issues like national income, general price level, money, distribution, and employment. Business Application It solves the internal issues. It solves external and environmental issues. Scope Microeconomics covers issues like actor pricing, product pricing, demand & supply position, production, consumption, and economic welfare. Macroeconomics covers issues like national income, general price level, money, distribution, and employment. Significance It helps to maintain the balance between the products and the factors of production like land, labor, capital, and entrepreneurship. Macroeconomics helps you maintain and solve major issues like inflation, deflation, unemployment, and poverty as a whole. Limitations Micro-economics considers some of the impractical presumptions like all people in the economy are employed which is impossible. The process and the composition are inaccurate in the process of assumption that you must know at your end. The tabular format gives the pinpointed explanation of the two concepts. Micro vs macroeconomics has other points of difference too. Let’s elaborate on them to get a complete idea about it. 1. Scope & Analysis Microeconomics deals with the behavior of individual economic agents, such as households, firms, and consumers. It examines how they make decisions regarding the allocation of resources, the production of goods and services, and the determination of prices for specific products. Macroeconomics, on the other hand, looks at the broader economy as a whole. It studies total variables of the economy, like national income, unemployment rates, inflation, and overall economic growth. It is one of the fundamental differences between Micro vs macroeconomics. 2. Focus Microeconomics focuses on the specific details of economic transactions and interactions at the individual level. It delves into topics like supply and demand, consumer choices, market structures, and the behavior of firms in different industries. Macroeconomics takes a bird's-eye view of the economy, looking at the overall performance of the economy, including issues like economic growth, inflation, and the business cycle. It aims to understand and analyze the economy's general health and stability. 3. Key questions Microeconomics answers questions such as "How do consumers make choices?" or "How do firms maximize profit?" It is concerned with issues like individual pricing decisions and resource allocation. Macroeconomics tackles questions like "What determines the overall level of employment in the economy?" or "What causes inflation or recession?" It seeks to understand the factors influencing the overall health and stability of an economy. How does the inventory turnover ratio get the impact of it? 4. Policy Implications Microeconomics primarily informs individual and firm-level decision-making. It is less directly tied to government policies, although it does have implications for regulatory and competition policies. You can go through the website of Byjus as well to get a clearer picture. Macroeconomics is closely linked to government policies and monetary and fiscal measures. It provides insights for policymakers to manage and stabilize the overall economy, such as through monetary policy, fiscal policy, and taxation. 5. Tools & Methods Microeconomists often use tools like supply and demand curves, consumer utility theory, and market structures. To analyze individual economic decisions and interactions. Macroeconomists use tools like national income accounting, aggregate demand and supply models, and monetary and fiscal policies. To study the overall behavior of the economy. Investopedia is also of the same opinion. How Are Micro & Macro Economics Interrelated? Microeconomics studies the aggregate structure, whereas Macroeconomics is itself the aggregates. In this way, both are interrelated to one another. You cannot learn macroeconomics without knowing microeconomics. End Of The Concept Hence, if you have doubts regarding the concepts of micro vs macroeconomics, then this article can be of great help for you to guide you in the right direction. Things are going to be easier for you once you go through the concepts with an in-depth analysis. You can share your comments and views in our comment box. It will be helpful for us to know your take on this matter. Share the experiences once you complete reading the article. Feel free to reach us if you have any queries left out. Read Also: What Is Net Operating Income? How To Calculate NOI? Vertical vs Horizontal Integration: What Are The Key Differences? What Is A Holding Company? – Importance, Operation, And Pros & Cons
Oct 07, 2023