Cost Insurance Freight? Everything You Should Know About It
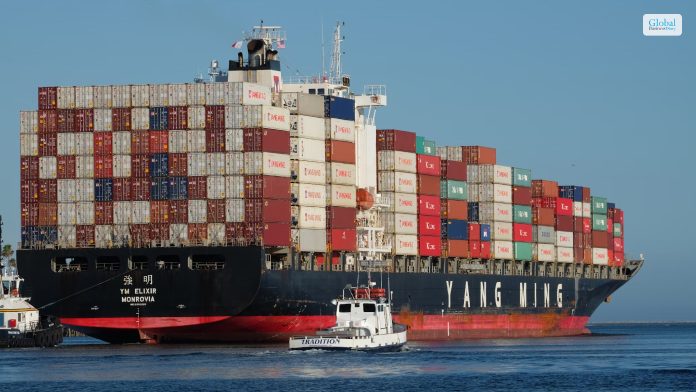
Cost insurance freight is also known as the international shipping agreement. You need to be well aware of it before you use this service. It represents the charges that a seller needs to pay to cover the costs, insurance, and freight of buyer’s order. These types of expenses sellers need to pay at the time of transit.
Most of the time, the goods are exported from the buyer’s port to the desired destination. You need to be well aware of the facts that can assist you in attaining your goals. Once the goods are loaded in the vessel, the liability of the goods transfers from seller to buyer.
The term CIF used in sea and waterway shipments all the time. You must be well aware of it while attaining your requirements with ease. CIF can ensure a smooth distribution channel.
What Is Cost Insurance Freight?

Cost, Insurance, and Freight (CIF) is a trade term used in international shipping and commerce. It specifically outlines the responsibilities and costs associated with transporting goods from the seller to the buyer. It is applicable for all the shipments that occur through the waterways. You must remember this point from your end.
Responsibilities Of Seller For Cost Insurance Freight
There are several responsibilities for the cost insurance freight that you must be well aware of. You cannot negate your responsibilities in this regard. Some of the core points that you must address here are as follows:-
- For the product, the seller needs to purchase the export license.
- You need to deliver the inspection of the products.
- Any kinds of charges at the time of shipping and loading the goods in the port will be given by the seller.
- A seller needs to meet the packaging cost of the cargo.
- The seller will give customs clearance and duties for taxes.
- Shipping costs of the freight will be given by the seller.
- Sellers need to take responsibility for the insurance of the goods unless the product reaches the buyer’s port of destination.
- You need to cover the damage and destruction of the goods at the time of shipment.
Responsibilities Of Buyer
Along with the seller, the buyer also needs to follow certain responsibilities to keep the goods in perfect shape. You cannot ease off your responsibilities in this regard. Some of the core responsibilities of the buyer are as follows:-
- You need to unload the product at the port terminal.
- The buyer needs to transport the product between the delivery site and the terminal.
- All the customs duty charges are essential for importing the goods.
- You need to meet the charges for transporting, delivering, and unloading the goods for the final destination.
Importance Of Cost Insurance Freight
There are several important cost insurance freights that you must be well aware of. You should know the facts that can assist you in reaching your goals with complete ease. Some of the key factors that you must take care of here are as follows:-
1. Clear Allocation Of Responsibilities
CIF terms clearly outline the responsibilities of the buyer and seller in the shipping process. This clarity helps both parties understand who is responsible for costs, insurance, and transportation at each stage of the shipment. You need to have a clear idea about the responsibilities that you have to shoulder at your end.
2. Risk Management On Cost Insurance Freight
CIF includes insurance coverage for the goods during transit. This mitigates risk of loss or damage to goods while they are being transported from the seller to the buyer. During transit, risk management can help you reduce the chances of your cost to a great extent. Once you follow the correct process, things can become easier for you in the long run. Follow the right process from your end.
3. Reduced Uncertainty For Cost Insurance Freight
With CIF terms, both parties have a clear understanding of the total cost involved in the transaction. It includes the cost of the goods, insurance, and freight. This reduces uncertainty and potential disputes regarding additional expenses or responsibilities. Cost Insurance freight can reduce the possibility of uncertainties to a great extent. You need to be well aware of it at your counterpart. It reduces the marginal cost to a great extent.
4. Smoother Customs Clearance
By clearly defining the responsibilities up to the port of destination, CIF terms can facilitate smoother customs clearance processes. The buyer knows when their responsibility for the goods begins, which helps in planning and preparation for customs procedures. It will reduce the burden of extra charges on the seller. Ultimately, it can distribute the cost evenly in the process of your transit.
5. Global Trade Facilitation
CIF terms facilitate global trade by providing a standardized framework for international transactions. They offer a common understanding of shipping responsibilities, making it easier for businesses from different countries to engage in trade. International trade has some rules and regulations. The cost insurance and freight will help you to meet up with these rules and regulations with complete ease.
6. Protection For Buyers & Sellers
CIF terms offer protection to both the buyer and the seller. Sellers ensure that the goods are safe and insured until they reach the agreed-upon port. While buyers need assurance of receiving the goods as agreed upon. It offers complete protection to the buyers and sellers at the time of transit of the consignment. You should be well aware of it. It helps to counter supply chain risk management issues with ease.
Final Take Away
Hence, if you want to make the process of your shipment smooth, then you must follow the guidelines of CIF. You must know the importance of the Cost Insurance freight can make things simpler for you in getting your goals with ease.
Share your experience with us while attaining your goals with complete ease. Try out the best options in this regard. Ensure that you follow the correct process from your end while attaining your goals with clarity.
CIF terms play a crucial role in international trade by providing clarity, risk mitigation, and a standardized framework for shipping goods across borders. They contribute to smoother transactions, reduced uncertainties, and better risk management.
Explore More Business Related News By Clicking Below!!

Recent
Memory Chips Are Becoming More Important in the AI Era
Aug 06, 2026

Why Enterprise Web Applications Still Choose Angular for Long-Term Growth
Aug 04, 2026

Due Diligence Decoded: Why Careful Evaluation Still Wins in Business
Jul 11, 2026

How Hydraulic System Design Impacts Equipment Performance
Jul 01, 2026

Related Articles
Risk & Reward: Navigating The Game Of Small Business Insurance For Lasting Peace Of Mind
In a fluctuating abroad of small enterprises, the quest for achievement usually comes with the help of several risk variables. Small enterprise owners are familiar enough with the challenges they have to deal with, but what about those unexpected events that might undermine their hard work? This is where the game of small enterprise coverage comes into use, providing a tactic to avoid dangers and ensure long-term peace of mind. In this edition, we delve into the remarkable ratio of threat and praise in the arena of small commercial coverage. Assessing Small Business Risks Identifying Potential Risks Step one in designing a solid coverage strategy is knowing the unique risks that your enterprise faces. Capability threats facing small groups range from damage to assets to claims for legal responsibility. For instance, a restaurant might further face slip-and-fall accidents, while a tech startup can be at risk of data breaches. Analyzing The Impact Of Risks These risks may have an excessive impact on the financial stability of your commercial enterprise. Take for instance a boutique retail store that is going through a flood, which destroys its stock and disrupts its operations. Without proper coverage coverage, the consequences can be economically catastrophic, perhaps leading to shutdowns. Types Of Small Business Insurance General Liability Insurance General legal responsibility insurance serves as a foundational shield in opposition to diverse risks. It presents coverage for bodily injury and property harm claims, protecting your enterprise from capacity proceedings. Whether a consumer slips on wet ground or there is damage because of your products, trendy legal responsibility coverage is a critical thing of a complete threat management method. Property Insurance Property insurance safeguards your physical assets, such as homes, equipment, and stock. Small corporations invest considerably in those properties, and unforeseen occasions like fires, theft, or herbal screw-ups can pose a great hazard. Property insurance guarantees that the financial burden of such events is alleviated, making an allowance for a fast restoration. Business Interruption Insurance Business interruption insurance is an insurance policy that helps reduce the financial effect of those disrupting your business activities. Be it some natural tragedy or abrupt cases such as pandemics, this policy compensates income loss for your business and helps you to stay financially afloat during these hard periods. Customizing Insurance Coverage Tailoring Policies To Business Needs Every small commercial enterprise is particular, and so are its dangers. Working with insurance vendors, together with Nation North Insurance, to customize insurance guarantees that your precise desires are addressed. Whether you operate in an excessive-legal responsibility enterprise or face specific dangers, tailoring rules to your business's wishes is a proactive step closer to complete safety. Understanding Policy Exclusions While customizing coverage, it is crucial to apprehend policy exclusions. Examining common exclusions allows discover ability gaps in insurance that may leave your enterprise vulnerable. Nation North Insurance, with its knowledge of small business coverage, can guide you through the intricacies of coverage terms and exclusions. Cost-Benefit Analysis Of Small Business Insurance Weighing The Costs Of Insurance Premiums Investing in insurance comes with an economic cost, but the benefits often outweigh the rates paid. When considering coverage, it is crucial to weigh the fees towards the potential risks. While the upfront costs may additionally seem enormous, the lengthy-term financial savings and safety provided by way of coverage offer a precious return on funding. Quantifying The Value Of Peace Of Mind Beyond the economic components, small business insurance contributes to the intangible yet helpful asset of peace of thought. Knowing that your commercial enterprise is included in opposition to unforeseen occasions allows you to recognize growth and success. The experience of safety provided via insurance is a key element in navigating the demanding situations of entrepreneurship. Risk Management Strategies Implementing Proactive Risk Mitigation In addition to insurance, small agencies can implement proactive change mitigation strategies. This consists of employee education, protection protocols, and measures to save you from common dangers. By being proactive, agencies can lessen the chance of incidents that can cause insurance claims. Establishing Emergency Preparedness Creating a contingency plan for sudden occasions is a crucial issue of hazard control. Small corporations ought to establish emergency preparedness protocols that define steps to be taken on the occasion of a disaster. Collaboration with insurance vendors can assist in developing powerful emergency plans. The Role Of Professional Advice Consulting With Insurance Experts Navigating the complexities of small business coverage requires expert steering. Consulting with skilled insurance experts, like the ones at Nation North Insurance, guarantees that you make well-informed selections. Their knowledge lets you understand the nuances of policies, pick the proper coverage, and cope with any concerns particular to your enterprise. Conclusion In the intricate sport of small commercial enterprise, studying the dynamics of hazard and praise is paramount. Small business coverage, with its tailor-made insurance and protection, serves as a strategic device for ensuring lasting peace of thoughts. By assessing dangers, customizing coverage, and weighing the expenses against the benefits, businesses can navigate the challenges with self-assurance. For complete small commercial enterprise coverage solutions, bear in mind partnering with Nation North Insurance – your relied-on ally in the pursuit of chance mitigation and long-term fulfillment. Read More: Malpractice Vs Negligence – Let’s Find Out The Difference Is Startup Business Insurance Necessary For New Businesses? What Is Commercial Insurance? And Its Different Types – Let’s Discuss
Jan 11, 2024
11 Tips For Saving On Business Insurance
You may be involved in setting up and running your business, thinking of ways to improve it, to the extent that you almost forget about the risks that can drive it to the ground. As much as you may not want to push the risk issue at the back of your mind until ‘the appropriate time,’ it’s a factor that you can’t ignore. The only way to ensure that your business is safe is by putting measures in place to take care of any eventualities along the way. Business insurance does just that. Businesses earn profit by minimizing expenses, and business insurance can be costly. However, there are guaranteed ways you can apply to cut business insurance costs without compromising your coverage. Let’s have a look at some of these ways: Shop Around Before settling for an insurance company to cover your business, ask for quotations from several carriers to compare rates so that you may evaluate each offer and see what suits your business. You’ll find that different insurance companies look at and calculate the same risks differently. While at it, use the opportunity to check their work backgrounds. Reputable insurance companies like Bruce Insurance will use their expertise to help you choose the right package and give you peace of mind. Comparing insurance coverage from different companies will help you settle on the best deal. Choose A Higher Deductible A deductible is the difference you’ll be required to top up out of pocket in case of a claim. For instance, if a fire razes down a portion of your premises and the claim is for the amount of USD$2,000, and your deductible is USD$500, the insurance company will only shoulder an amount of USD$1,500. Your business will be required to chip in the difference of USD$500. When choosing a deductible, go with an amount your business can tolerate without affecting its cash flow in case of an incident. This is because you’ll be required to pay the amount upfront before your claim is approved. The higher your deductible, the lower the premium you will pay. Get The Help Of An Expert Business insurance is a bit more complex than home and car insurance. The dynamics are more complicated and need an expert to break them down. Running a business comes with many associated hidden risks, some of which you may not know. Your insurance agent will therefore be valuable when you’re making decisions regarding the coverage of your business. They will help you evaluate your business and advise on the required insurance coverage best suited for your kind of business. They’ll also recommend what you need to fix to lower your premiums. You’ll eventually spend only on what is necessary while being adequately covered. Request For Discounts The insurance market is just as flexible as any other market. Some insurance companies reward their clients with discounts in the form of lower premiums for various reasons. One instance is if the clients haven’t filed any claim for a certain period because they’re considered low risk. Ask your insurer if you are eligible for any discount depending on their offer. Evaluate Your Business’s Protection And Risks All businesses carry different levels of risks depending on their nature. It's essential to evaluate potential risks and implement strategies to minimize them. For example, if you’re in the restaurant business in Tennessee, securing Tennessee Restaurant Insurance can help protect against common risks such as property damage, food spoilage, or customer injuries, shielding your business from financial losses and ensuring a more secure operation. This tailored coverage provides peace of mind while you focus on growing your restaurant. Get A Package Specific To Your Needs All businesses, be they big or small businesses, have different insurance needs. Ensure you get a business cover tailored to suit your specific needs. Know what coverage and limits are required for the size and kind of business you have so that you’re not over- or undercovered. Doing so will ensure that you are only paying for what you need. Pay Premiums Upfront In Full You can save substantially on your insurance premiums if you pay the whole sum upfront. It may not seem like you’re paying much in installments because the extra amount is spread in segments. However, the truth is that calculating the amount you pay over and above translates to a significant amount that can be injected back into your business. Go For Group Rates Some insurance carriers offer lower group rates for businesses in the same industry. You should register your business under the relevant industry’s organization to reap some benefits. Your membership will make you eligible for the reduced insurance rates. You’ll also get the added advantage of expanding your network among people in the same industry. Spread The Risk If your business involves working with third parties or entities independent of your business, ensure that you’re not carrying their insurance burden. For example, if you’re working with independent contractors, let them have their insurance cover. Additionally, never take on board subcontractors who don’t have insurance because you’ll expose your business to liability when a claim is filed against it. This way, you’ll pay less for insurance coverage because your potential risks will be lower. About Bundle Insurance A business requires many insurance covers to shield itself from potential risks effectively. Buying insurance cover separately can be expensive, yet some insurance companies offer better rates if you purchase several covers under one plan. For instance, a business owner’s policy is packaged with several standard insurance covers for small to medium businesses. Bundling your insurance will cut costs and save you some. Review And Update Your Coverage Before Renewal As time goes by, your business will change, and so will your insurance needs. The best time to review your coverage is when it’s due for renewal. This will enable you to identify areas that need upgrades to keep up with the changes in your business, as you also determine what you may be paying for but no longer need. Final Words Although comprehensive business insurance coverage is necessary for every business, you don’t have to pay an arm and a leg to get one. Shopping around can help you find the right coverage for your business at an affordable price. However, while looking to save on business insurance, don’t leave out essential aspects of your business coverage because you may end up paying much more in case of an incident. Additionals Fiscal Sponsorship – Everything You Need To Know About It In 2021
Jun 30, 2022
What Is Indemnity Insurance ? And Its Different Types – Let’s Discover
As an administrator of a business organization or an enterprise, you must be aware of the unforeseen circumstances, and must step up to thwart them as it can happen to your business. Such circumstances can be perilous for the business, and can even lead to many losses for the business. This is where an indemnity insurance comes into play. In this article, you will learn in general about indemnity insurance along with an example of the same. In addition to that, we will also discuss the major types of indemnity insurance that are available for a business. You will also learn how the various types of indemnity insurance options can help you, and in what regard. Hence, to find out more about the topic, read on through to the end of the article. What Is An Indemnity Insurance? According to Wall Street Mojo, “Indemnity insurance refers to the insurance coverage that safeguards an insured against the monetary losses arising out of professional negligence. Like any other insurance, this also provides coverage in exchange for regular premium payments from the insured.” Let’s see an indemnity insurance example, where you are the owner of a wealth management firm, and a client is suing your firm alleging a financial loss, after following the advice of the firm. If the firm had an indemnity insurance beforehand, it would help in covering the monetary damages. These monetary damages including all the legal expenses that were incurred during the lawsuit proceedings. Indemnity insurance is a form of protection that compensates for financial losses or damages, offering various types to cater to different professional needs, including the specialized area of guardian physician disability insurance. This specific type of insurance is designed to safeguard physicians against loss of income due to a disability, recognizing the high stakes of their profession and the intensive training it requires. Guardian physician disability insurance provides tailored coverage options that can be adjusted according to the unique risks and financial implications a physician might face if unable to practice. It's crucial for medical professionals to consider this insurance as it not only covers their personal income but also helps in maintaining their standard of living if they become disabled. Understanding the nuances and benefits of physician disability insurance enables physicians to make an informed choice, ensuring their financial security in the face of unforeseen health challenges. The indemnity insurance policy compensates the insured party for not only the unexpected losses or damages, but also the amount of the loss itself. All these coverages are up to a certain limit. According to USNews.com, “Examples of indemnification include an insurance company paying to repair or replace damaged property, reimbursing medical bills, or covering legal settlements and fees that the insured is held liable for.” These policies are designed in such a way to protect business owners and professionals, after they have made a fault in a particular event, which created the case of malpractice and misjudgment. The case comes in the form of an indemnity letter. Read More: The Types Of Business Insurance Needed For Every Business How Does An Indemnity Insurance Works? An indemnity letter compensates in the case of losses and damages. In a legal situation, this also means an exemption from being liable for the damages made. Here, the party that is insuring promises the party that is getting insured for the coverage of the losses, in exchange for the premiums that the policyholder is paying. According to Investopedia, “Indemnity insurance is a supplemental form of liability insurance specific to certain professionals or service providers. Insurance professionals provide counsel, expertise, or specialized services.” However, you must not confuse this type of insurance with a simple general liability insurance or any other commercial business insurance. A financial indemnity insurance protects you from claims that are arising from the certain negligence or a situation when the business fails to perform, which further results in a financial loss for the client. The policy helps the individual or the business from a looming legal entanglement. This is because, if your client has suffered a loss, he/she has the right to file a civil claim. Your indemnity insurance helps you in this case, by paying the costs associated with the litigation, as well as the cost of damages that the court awarded. What Are The Major Types Of Indemnity Insurance? Indemnity insurances can be of different types. The following are the major types of indemnity insurance options that you will come across: Professional Indemnity Insurance Claim As per the claims of Wall Street Mojo, “Professional indemnity insurance is curated to protect professionals against specific instances such as misjudgment. These insurances help companies deal with legal expenses and settlement costs.” It is the type of commercial indemnity insurance that protects you as a business owner or a professional if there is an alleging complaint against you. For example, if the client thinks that the business actually behaved negligently, and failed to perform as per promise. This is different from a simple commercial liability insurance, which protects your business to cover the injury costs of a client on the premises. Hospital Indemnity Insurance According to Investopedia, “Hospital indemnity insurance is a type of supplemental insurance that pays for hospitalization costs that are not covered by other insurance. This type of insurance is frequently taken out by businesses in case their employees are injured on the job.” Such a type of insurance can be beneficial, as most people in the US do not have enough savings to cover the medical bills that are unplanned. Here, as per the plan, the insurer pays the cash directly to the employees. This acts as a supplemental insurance to pay for the costs associated with admission in a hospital. Fixed Indemnity Insurance - What Is Indemnity Plan? Having a fixed indemnity insurance plan can help you to get fixed benefits for healthcare events, regardless of the actual insurance cost. Such a plan allows you to get a fixed amount of money for every hospital admission, or even a certain amount for each day of admission in a hospital. However, your must also know that a fixed indemnity insurance plan is not covered under the Affordable Care Act. In addition to these, when you purchase premiums of indemnity insurances, you must focus on the aspects of the premium about what the insurance does not cover. This is because you will not get an indemnification outside the parameters set by the policy. Furthermore, you will also not receive restitution at a higher value that what is promised. Read More: Is Startup Business Insurance Necessary For New Businesses? Final Thoughts If you are a business owner, having indemnity insurance can help a lot in dealing with unforeseen situations. Hope this article was helpful for you to get a good idea of what an indemnity insurance is, and what are the major types of indemnity insurance available for you. However, before you purchase your insurance, make sure to read the policy carefully. How do you think indemnity insurance can be helpful for your business? Share your thoughts with us in the comments section below. Read More: 11 Tips For Saving On Business Insurance Guaranteed Issue Life Insurance: Is it Worth It? Maximizing Home Insurance Coverage For Your At-Home Business With Riders
Aug 02, 2023
Health Insurance And Cancer Everything You Need To Know
Receiving a cancer diagnosis can be overwhelming, both emotionally and financially. The cost of cancer treatment can be exorbitant, making it essential to have a comprehensive health insurance policy that covers cancer-related expenses. When it comes to health insurance, understanding the coverage options and exclusions related to cancer is crucial. Dealing with a cancer diagnosis can be emotionally and financially overwhelming, but having the right health insurance policy in place can provide much-needed support during this challenging time. Understanding Health Insurance Coverage for Cancer Health insurance policies differ in their coverage for cancer-related expenses. To ensure that you have the necessary financial protection, it is essential to understand the coverage options available. Here are some key aspects to consider: 1. Cancer Treatment Coverage Most health insurance policies cover cancer treatments, including chemotherapy, radiation therapy, surgery, and targeted therapies. However, the extent of coverage may vary, and it is crucial to review the policy details to understand the specific treatments covered. 2. Pre-Existing Conditions Some health insurance policies have a waiting period for coverage of pre-existing conditions, including cancer. This waiting period can vary from a few months to a few years. It is important to consider this waiting period when choosing a health insurance policy. 3. In-network vs. Out-of-Network Providers Health insurance policies often have networks of healthcare providers, including hospitals and doctors, with whom they have agreements. In-network providers have negotiated rates with the insurance company, resulting in lower out-of-pocket costs for policyholders. It is essential to check if your preferred oncologists and cancer treatment centers are in-network before selecting a health insurance policy. 4. Coverage for Clinical Trials If you are considering participation in a clinical trial for cancer treatment, it is crucial to review your health insurance policy's coverage for such trials. Some policies may cover the costs of certain clinical trials, while others may not. Understanding this coverage can help you make informed decisions about your treatment options. 5. Additional Benefits Health insurance policies may offer additional benefits that can be especially helpful for cancer patients. These benefits may include coverage for counseling services, palliative care, reconstructive surgery after mastectomy, and transportation to and from treatment centers. Review your policy's additional benefits to understand the support available. Health Insurance Policy provides A. Coverage Options: Health insurance policies offer various coverage options for cancer-related treatments. These may include hospitalization expenses, doctor consultations, diagnostic tests (such as biopsies and imaging), surgery costs, chemotherapy sessions, radiation therapy sessions, targeted therapy drugs, immunotherapy drugs, stem cell transplants, rehabilitation services (such as physiotherapy), and palliative care. It's important to carefully review different policies to ensure they cover the specific treatments you may require. B. Exclusions: While health insurance policies provide coverage for many aspects of cancer treatment, it's essential to be aware of any exclusions that may exist within your policy. Common exclusions include experimental or investigational treatments that are not yet approved by regulatory authorities or included in standard treatment guidelines. Some policies may also exclude certain types of cancers or pre-existing conditions related to cancer if they were known before obtaining the policy. C. Claim Procedures: Understanding how to navigate the claim procedures for cancer-related expenses is vital for a seamless reimbursement process. Generally, insurers require detailed documentation from healthcare providers confirming the diagnosis of cancer and outlining the recommended treatment plan. This documentation should include medical reports such as pathology results and treatment invoices from hospitals or clinics. It's advisable to maintain a record of all medical documents related to your cancer diagnosis and treatment journey. Exclusions and Limitations in Health Insurance Policies While health insurance policies provide coverage for cancer-related expenses, it is important to be aware of exclusions and limitations. These can impact your out-of-pocket expenses and the treatments and services covered. Here are some common exclusions and limitations to consider: 1. Experimental and Investigational Treatments Health insurance policies may not cover experimental or investigational treatments for cancer. These treatments are still being studied and may not have sufficient evidence of their effectiveness. It is important to review your policy's position on such treatments and discuss them with your healthcare team if relevant. 2. Alternative and Complementary Treatments Certain health insurance policies may not cover alternative or complementary therapies for cancer, such as acupuncture, herbal medicine, or naturopathy. If you are interested in these treatments, it is important to review your policy's coverage or consider supplemental insurance that specifically covers alternative therapies. 3. Travel Expenses While health insurance policies may cover cancer treatments, they may not cover travel expenses to distant treatment centers. It is essential to consider these costs and explore if your policy offers any coverage for travel expenses. 4. Financial Limits and Maximums Health insurance policies may have financial limits and maximums for cancer-related expenses. These limits can include annual or lifetime maximums for specific treatments or overall costs. Understanding these limits is important to avoid unexpected financial burdens during treatment. Navigating Claim Procedures for Cancer Treatment Submitting claims for cancer treatment can be a complex process. It is important to understand the claim procedures to ensure timely reimbursement and minimize stress. Here are some tips for navigating claim procedures effectively: 1. Maintain Detailed Medical Records Keep a detailed record of all cancer-related treatments, tests, hospital stays, and doctor visits. This documentation is essential when submitting claims and can support the reimbursement process. 2. Understand Out-of-Network Coverage If you need to seek out-of-network care for cancer treatment, understand your health insurance policy's coverage and the claim procedures associated with it. Out-of-network claims may require additional documentation and pre-authorization. 3. Seek Assistance from the Healthcare Providers Hospitals and cancer treatment centers often have dedicated staff who can help navigate the insurance claim process. Seek assistance from these professionals to ensure accurate and timely submission of claims. 4. Follow Up on the Status of Claims Regularly follow up with your health insurance company regarding the status of your claims. If there are any delays or issues, be proactive in resolving them to avoid prolonged reimbursement times. Important Considerations for Cancer Health Insurance Policies When selecting a health insurance policy for cancer coverage, there are several important considerations to keep in mind: A. Cost vs. Coverage Choosing the right health insurance policy involves a balance between cost and coverage. Evaluate the monthly premium, deductibles, co-pays, and out-of-pocket maximums to determine the overall cost of the policy. Compare this cost to the coverage provided to ensure it aligns with your financial capabilities and anticipated medical expenses. B. Network of Providers Consider your preferred oncologists, cancer treatment centers, and hospitals to ensure they are in-network with the health insurance policy you choose. In-network providers offer cost savings and a streamlined claims process. C. Policy Renewal and Changes Understand the policy renewal process and any potential changes to your health insurance policy. Cancer treatment can span several years, and it is crucial to have a policy that offers consistent coverage throughout your treatment journey. D. Supplemental Insurance Consider supplemental insurance options, such as critical illness plans or cancer-specific policies. These can provide additional financial support and coverage for specific cancer-related expenses. E. Supportive Services and Resources Look for health insurance policies that offer supportive services and resources for cancer patients. These can include case management, nurse hotlines, or access to support networks. Such resources can be invaluable during your cancer journey. Tips for Choosing a Policy: When selecting a health insurance policy related to cancer, consider the following tips: 1. Assess your specific needs: Evaluate the coverage options and exclusions of different policies to ensure they align with your anticipated healthcare requirements. 2. Network hospitals and specialists: Check if the policy has tie-ups with reputable hospitals and specialists in your area, as this can facilitate a smooth treatment process. 3. Waiting periods: Understand any waiting periods associated with cancer-related coverage, as some policies may impose waiting periods before covering certain treatments. 4. Premiums and deductibles: Compare premiums and deductibles across different policies to find one that suits your budget while providing adequate coverage. 5. Policy renewal terms: Review the policy's renewal terms, including any changes in premium rates or coverage options that may occur over time. Conclusion: Health insurance policies related to cancer play a crucial role in providing financial support during a challenging period of life. Having a comprehensive health insurance policy that covers cancer-related expenses is crucial for financial security and peace of mind. Understanding your policy's coverage options, exclusions, claim procedures, and important considerations allows you to make informed decisions and navigate the complexities of health insurance effectively. Remember, you don't have to face cancer alone. Reach out to support organizations and professionals who can provide guidance and assistance in finding the right health insurance policy for your needs. Read Also: What Is Indemnity Insurance ? And Its Different Types – Let’s Discover The Types Of Business Insurance Needed For Every Business How To Start An Insurance Company? – Steps You Must Take
Sep 02, 2023